
A three-way salary packaging arrangement
Novated leasing, explained without the sales pitch.
Whether a novated lease beats a car loan depends on your salary, the vehicle and your employer’s arrangements. We show the comparison honestly.
 340 client reviews



One broker from your first call through to funding.
See which novated lease options fit your business.
Tell us what you need. A Lyft Money broker compares 48+ lenders and explains the rate, fees and repayments before you decide.
Access to 21+ novated lease lenders
Lenders on our panel that fund novated lease.





















At a glance
Novated lease: the numbers that matter.
- Amount
- $15,000 – $150,000
- Term
- 12–60 months
- Indicative rates
- 6.9% – 13.5% p.a.
- Typical speed
- 3–10 business days including employer sign-off
- Security
- Secured by the asset
- Repayments
- Deducted each pay cycle from salary
Rates as at Q3 2026. See the rate history →
In plain English
What is a novated lease?
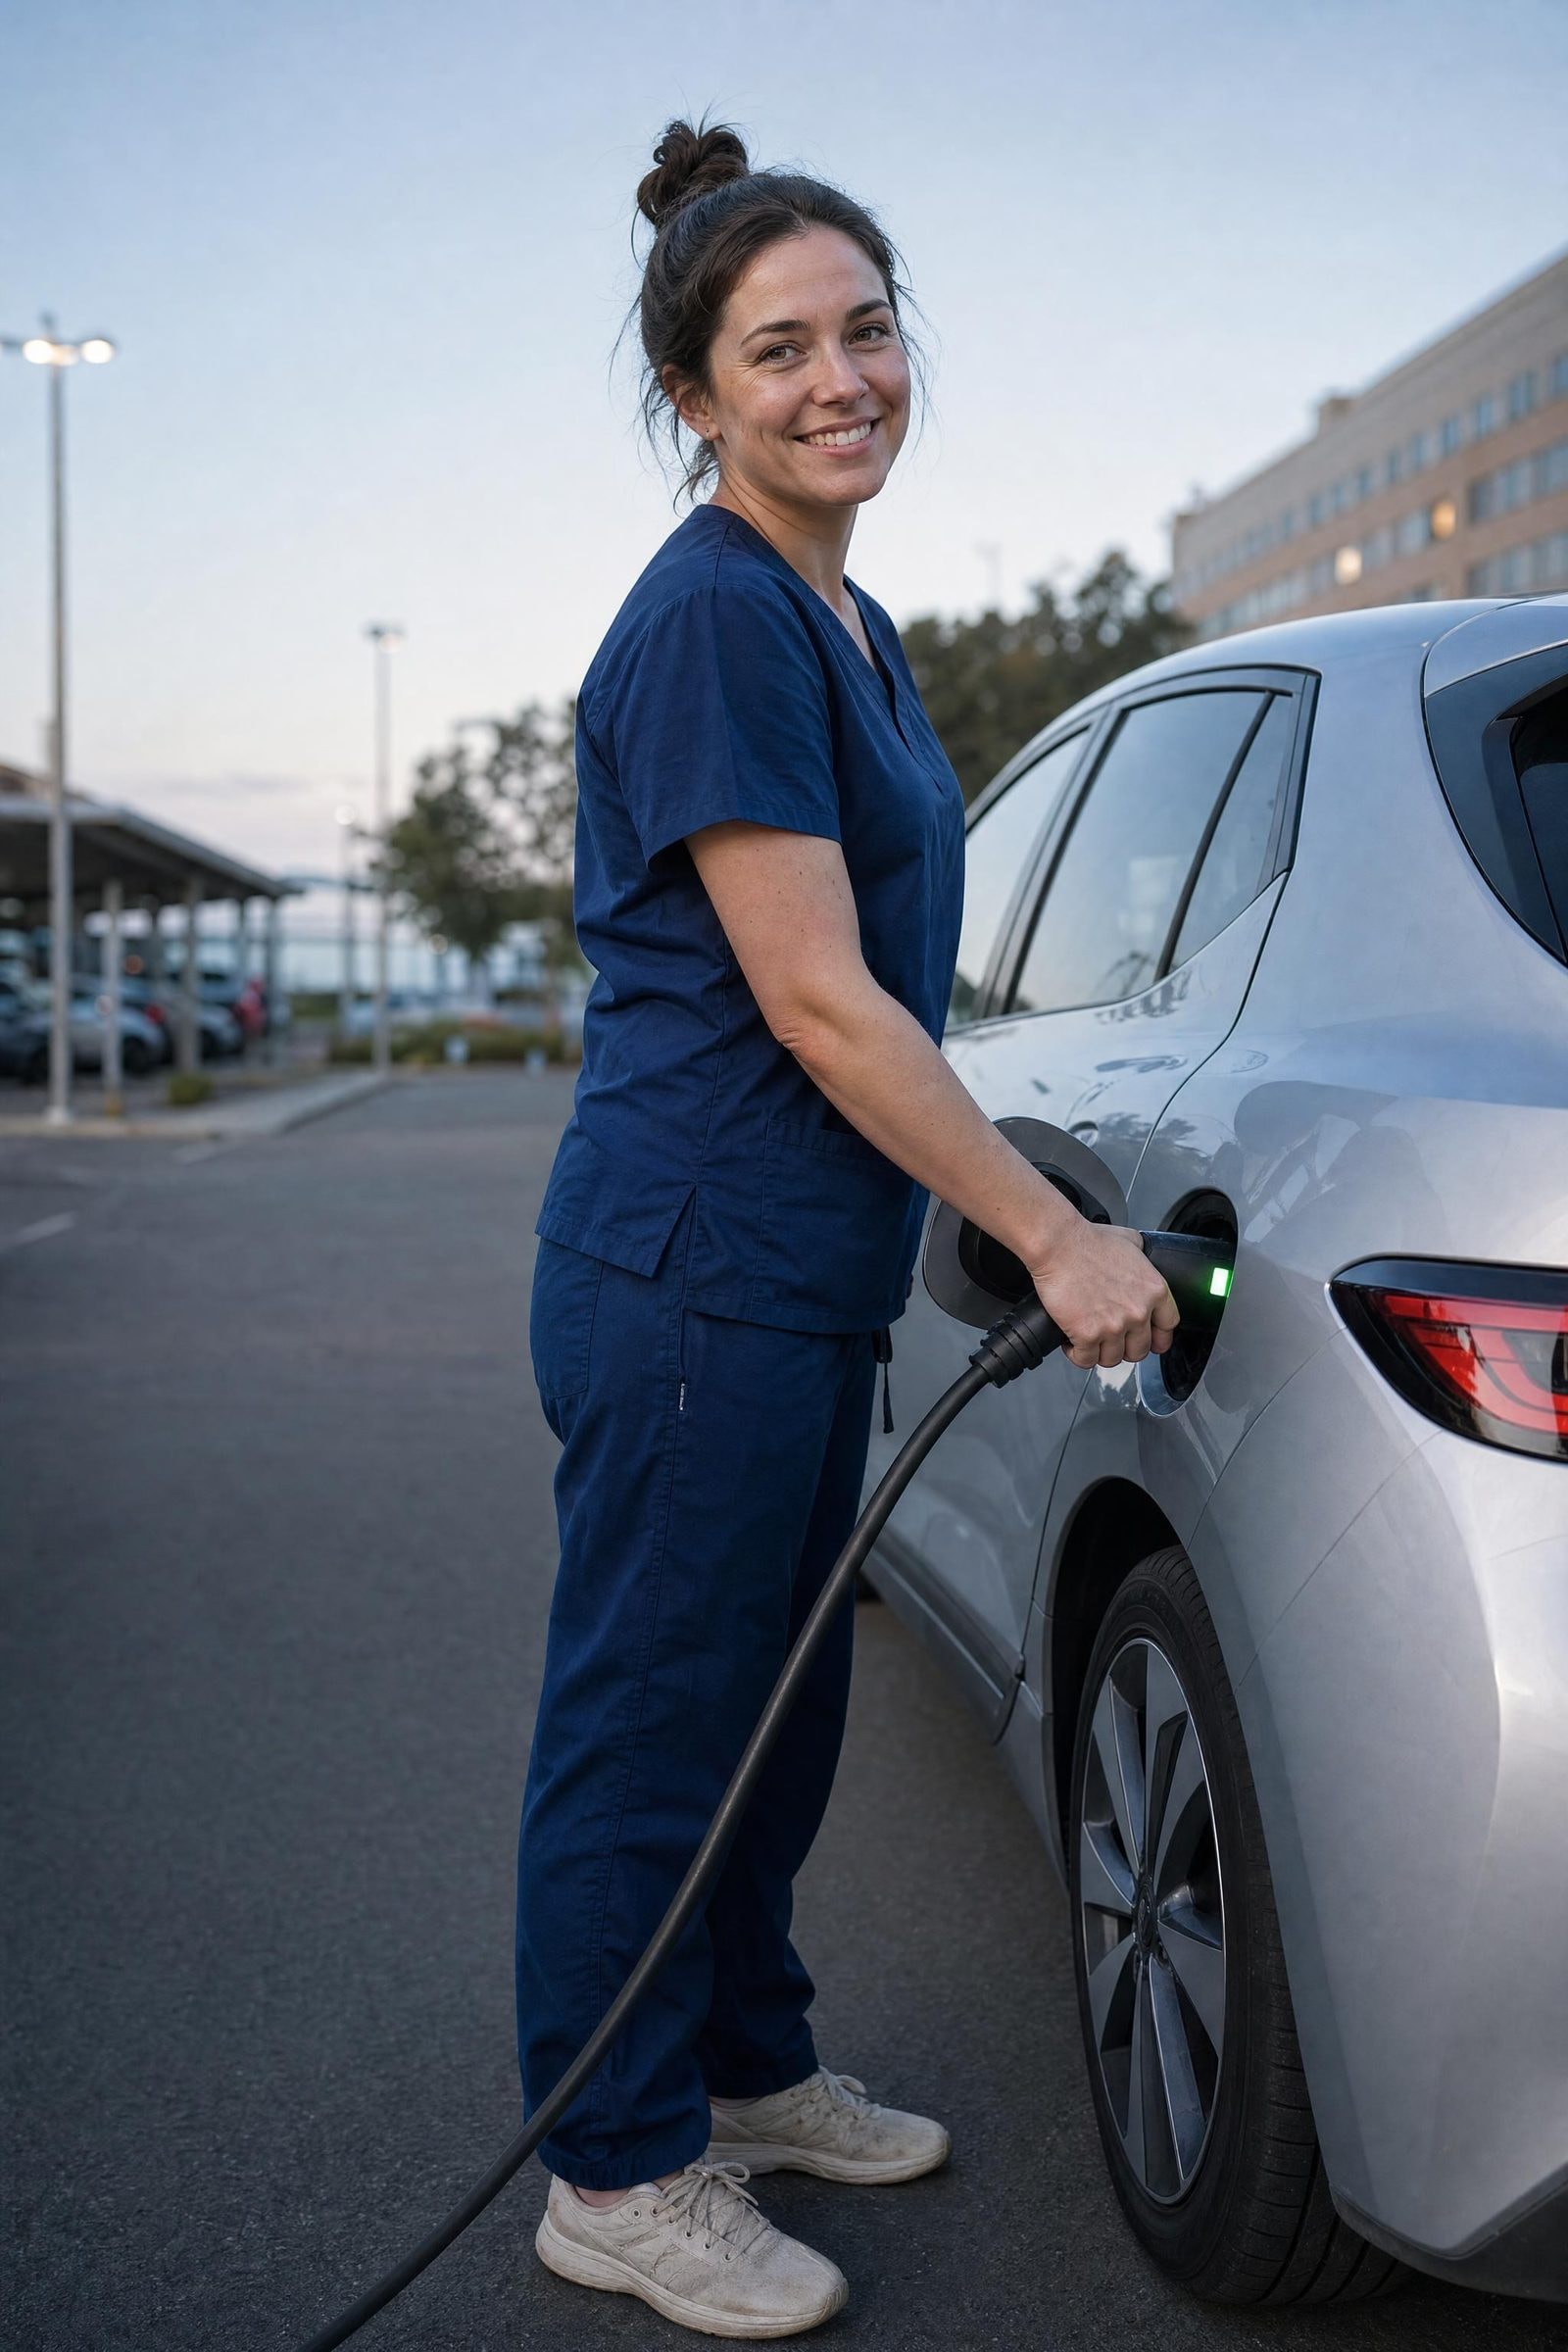
A novated lease is a three-way agreement between an employee, their employer and a financier, where the employer deducts the lease payments and running costs from the employee’s pre-tax salary. The employee chooses and uses the car; the obligation moves with them if they change jobs.
Under a novated lease the employee enters a lease with a financier, and a deed of novation transfers the payment obligation to the employer while the employee remains the end user. The employer deducts payments from pre-tax salary, reducing taxable income. Fully maintained arrangements bundle fuel, servicing, tyres, registration and insurance into the same deduction, so one figure covers the whole cost of running the car.
The tax picture has two moving parts. Salary sacrificing reduces income tax, but providing a car to an employee creates a fringe benefits tax liability, usually managed through the employee contribution method — post-tax contributions that offset the FBT. Eligible battery electric and plug-in hybrid vehicles under the luxury car tax threshold have attracted an FBT exemption that materially improves the outcome; eligibility rules have changed over time, so current advice matters.
Novated leasing is genuinely good value for higher-income earners with stable employment and a supportive employer, and poor value for people on lower marginal rates, in insecure roles, or buying an inexpensive used car. Leaving your job means the obligation reverts to you personally. Your broker will run the numbers against a straightforward consumer car loan rather than assuming the packaged option wins.
A good fit when
Salaried employees on higher marginal tax rates whose employer offers salary packaging
Consider something else if
Contractors, sole traders, people in insecure employment, or low-value used car purchases
Advantages
- Payments and running costs come from pre-tax salary
- GST savings on the vehicle price and running costs
- One bundled payment covers fuel, servicing and insurance
Trade-offs
- Obligation reverts to you if you leave your employer
- Residual must be paid, refinanced or covered by sale at term end
- Benefit shrinks sharply at lower marginal tax rates



A clear next step
How to apply for a novated lease.
Our AI helps check lender fit across 48+ lenders. Your broker reviews the options and explains what they mean for you.
- 01
Check employer arrangements
Confirm your employer offers novated leasing and which packaging providers they work with.
- 02
Model against a car loan
Your broker compares the net after-tax cost of the novated lease with a consumer car loan on the same vehicle.
- 03
Novate and drive
Employer, employee and financier sign the deed of novation, deductions begin, and the vehicle is delivered.
- Recent payslips and employment details
- Vehicle quote and specification
- Employer confirmation of salary packaging arrangements
The lender makes the final credit decision. Available options depend on your business and the lender’s assessment.
Before you make a decision
Estimate your novated lease repayments.
Know what lands and what leaves. Adjust the amount, rate and term to see the repayment and total cost.
- Number of repayments
- 48
- Total interest (est.)
- $14,245
- Total repaid (est.)
- $89,245
This calculator is a guide only. It uses simplified assumptions, excludes fees and charges unless stated, and is not an offer or quote. Actual repayments are confirmed by the lender in its loan contract.
From Lyft Money clients
Clear advice.
People who stay in touch.
Rated 5.0 from 340 Google reviews across the types of finance we arrange. Read them on Google.
“keeping us informed every step of the way”
“He explained all the financing options clearly”
“helped out my business”
What people finance with a novated lease
Lenders we compare for this
Banjo Loans, ScotPac, FlexiCommercial, Shift, Angle Asset Finance, Metro Finance, Pepper Money and others on our panel. See the full panel.
Key terms
What is a novated lease?
A novated lease is a vehicle lease where a deed of novation transfers the employee’s lease payment obligations to their employer, who deducts the payments from the employee’s pre-tax salary. The employee selects and uses the vehicle throughout the term.
What happens to a novated lease if you change jobs?
The novation ends and the lease obligation reverts to the employee personally. It can then be re-novated to a new employer who offers salary packaging, paid from post-tax income, or paid out entirely.
What is the employee contribution method?
The employee contribution method is where an employee makes post-tax contributions towards the running costs of a packaged vehicle, reducing or eliminating the employer’s fringe benefits tax liability on the car.
Is a novated lease better than a car loan?
It depends on marginal tax rate, vehicle choice, employment stability and the employer’s packaging arrangements. Higher-income earners with secure employment often benefit; lower-income earners and those buying inexpensive used cars often do not.
What is a novated lease and who is it for?
A novated lease is a three-way arrangement between an employee, their employer and a financier, where the employer deducts the vehicle payments from the employee's salary. It is only available to employees whose employer offers salary packaging, not to a business buying its own vehicle. The tax treatment involves fringe benefits tax rules, and concessional treatment applies to some eligible electric vehicles. Your payroll department and accountant should confirm the position before you sign.
How does a novated lease work?
A novated lease is a three-way agreement between you, your employer and a finance company. You choose the car, the finance company leases it to you, and your employer takes over the lease payments and running costs, deducting them from your salary, partly before tax. You use the car as your own, and if you leave the job the lease goes with you. It is available to employees whose employer offers salary packaging, which includes most government, health, education and many private employers.
How does a novated lease save tax?
Lease payments and running costs come out of your salary before income tax, which lowers your taxable income. Because a car provided this way is a fringe benefit, fringe benefits tax applies, and most arrangements use the employee contribution method, where part of the cost is paid from after-tax salary to offset the FBT. The result is usually a saving compared with paying for the same car from after-tax income, and the saving is larger at higher incomes and for eligible electric vehicles. We show the comparison against a car loan for your salary and vehicle.
Why are electric vehicles so popular on novated leases?
Eligible electric vehicles under the luxury car tax threshold for fuel-efficient vehicles are exempt from fringe benefits tax when provided through a novated lease. That means the whole lease payment and running costs can come out of pre-tax salary with no FBT to offset, which for many employees makes an EV cheaper to run than a similar petrol car bought with a loan. Plug-in hybrids lost the exemption for new arrangements from April 2025, so check the current rules for the vehicle you have in mind.
What running costs are included in a novated lease?
Most novated leases bundle fuel or charging, servicing, tyres, registration, insurance and roadside assistance into one salary deduction, budgeted from your expected kilometres and reconciled during the year. Some drivers prefer a finance-only novated lease and pay running costs themselves. Bundling is convenient, but the budget should match your real usage so you are not over- or under-deducted.
What happens at the end of a novated lease?
A residual value, set by ATO minimum percentages according to the lease term, remains at the end. You can pay it and keep the car, refinance it into a new lease, or sell the car and use the proceeds to pay the residual, keeping any surplus. Many people trade up to a new car on a fresh novated lease at that point. Your broker explains the residual on each quote and what the options are when it falls due.
What happens to my novated lease if I change jobs?
The lease is yours, not your employer’s. If you leave, the novation with that employer ends and you either novate the lease to your new employer, if they offer salary packaging, or take over the payments personally until you do. Your tax saving pauses while the lease is not novated. It is worth checking that a prospective employer supports novated leasing before you move.
Is a novated lease better than a car loan?
It depends on your salary, the vehicle and how much you drive. Novated leases tend to win for higher earners, for eligible electric vehicles because of the FBT exemption, and for people who value one bundled payment for all running costs. A car loan can be better for lower earners, for very low kilometres, or where the employer’s packaging provider adds high fees. Lyft Money compares the two honestly for your situation rather than assuming one answer.
Chattel mortgage or novated lease for a business car?
A chattel mortgage suits a car owned by the business and used mostly for business: the business owns it, claims GST and depreciation, and the repayments come from business cash. A novated lease suits an employee, including a company director on salary, who wants the car packaged from pre-tax pay with running costs bundled. The right answer depends on who drives the car, how much private use there is and the entity structure, which your accountant and broker work through together.
Is finance for electric vehicles different?
The finance structures are the same — chattel mortgage, lease or novated lease — but a few things change. Some lenders offer specific EV or low-emissions products, residual and balloon settings can be more conservative because resale values are still stabilising, and charging infrastructure can sometimes be financed alongside the vehicle. For employees, eligible electric vehicles under the luxury car tax threshold may attract an FBT exemption on a novated lease. Confirm current rules with your accountant.
Your business. Your decision.
See your options.
Know the costs.
Decide with confidence.
One broker to explain it. Clear numbers before you proceed.
No obligation to proceed.