
Industry guide
Finance for agriculture, shaped around how you get paid.
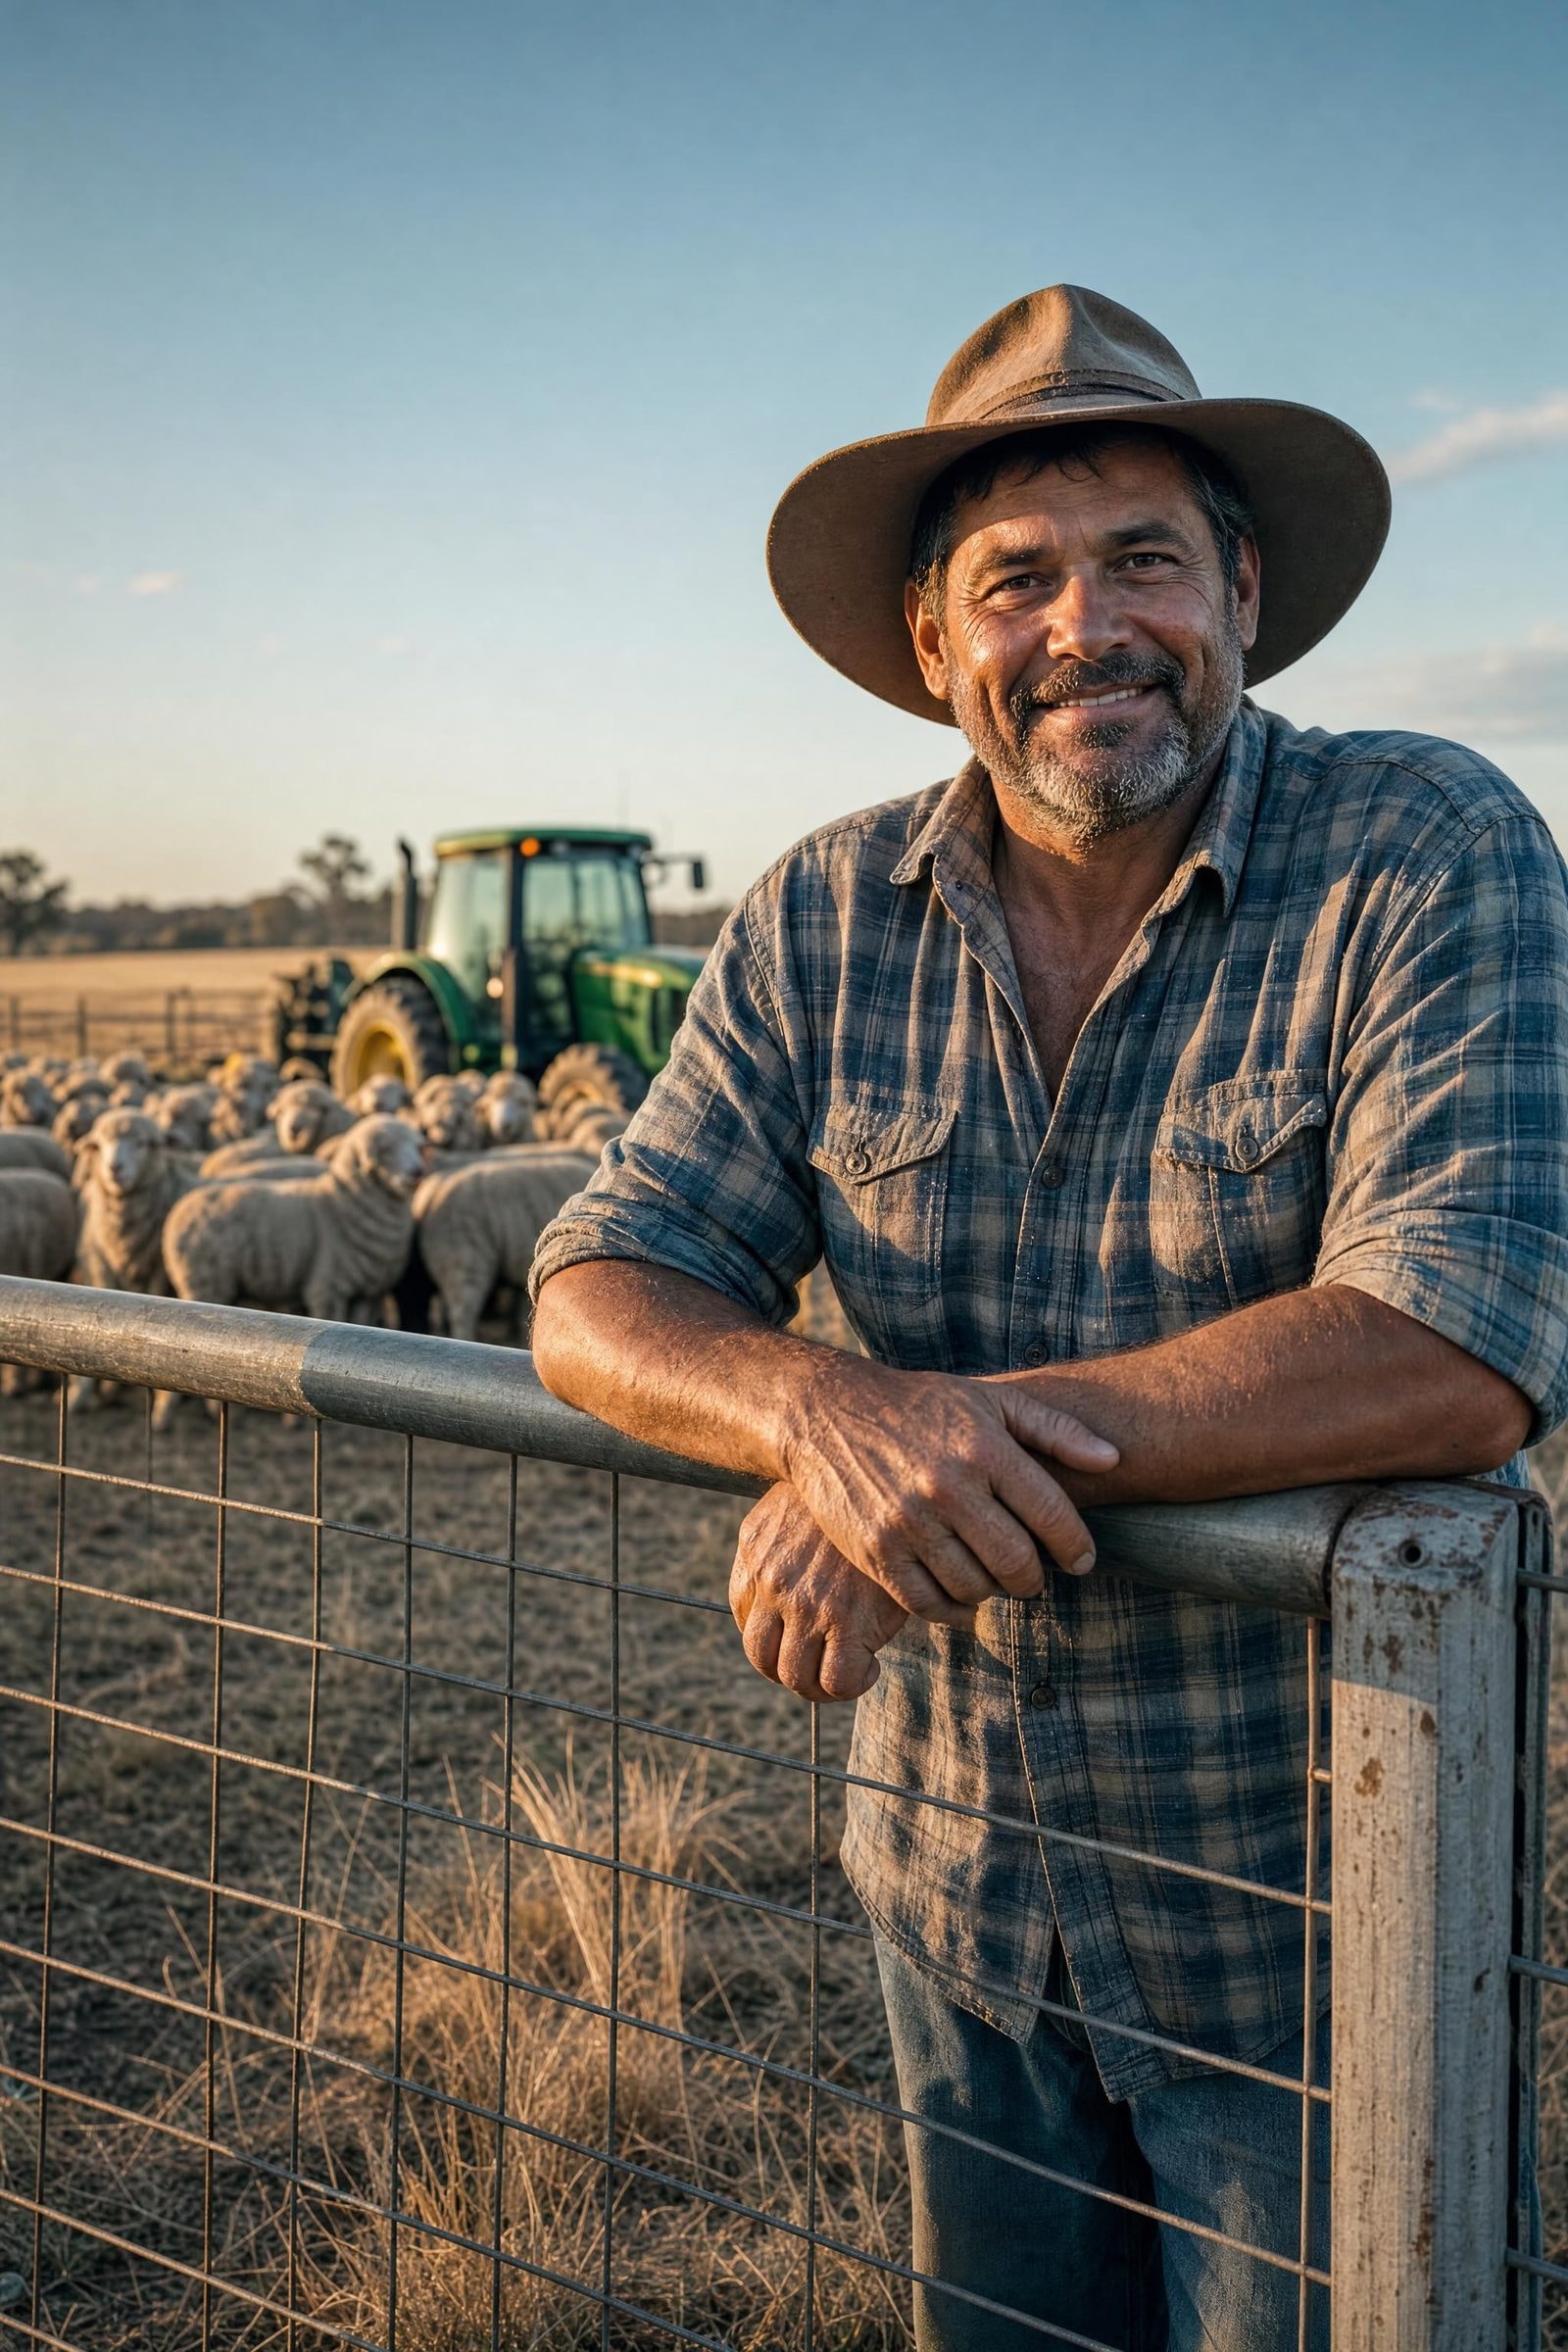
Farming income arrives once or twice a year while costs run every month. Finance for agriculture is mostly about matching repayments to harvest, shearing or the sale of stock.
 340 client reviews



One broker from your first call through to funding.
See which options fit your business.
Tell us what you need. A Lyft Money broker who knows agriculture compares 48+ lenders and explains the rate, fees and repayments before you decide.
Access to 57+ agriculture lenders
Lenders on our panel that fund agriculture.

































At a glance
Agriculture: the numbers that matter.
- Typical amounts
- $20,000 – $3,000,000
- Typical speed
- 2–5 business days
- Indicative rates
- 6.7% – 14% p.a.
- Finance options
- 6 structures compared
- Lenders active here
- 2+ on our panel
- Assets we fund
- Tractor, Header harvester, Irrigation equipment and more
In plain English
Finance for agriculture: how it works.
Agricultural finance is lending structured around a single annual income event, using seasonal repayments, equipment finance for machinery and working capital that carries a farm from planting through to sale.
A cropping farm spends heavily on seed, fertiliser, fuel and chemical between autumn and spring, then receives most of its income within a few weeks of harvest. Livestock producers face the same shape with different timing. A monthly repayment schedule built for a suburban business simply does not fit that pattern, which is why agricultural lenders on our panel offer annual or seasonal repayment structures, deferred first payments and terms that line up with the production cycle rather than the calendar.
Machinery is the other constant. Tractors, headers, sprayers and irrigation infrastructure are expensive, long-lived and hold value well, which makes them good security. Many farms also carry the risk of a season going wrong, so lenders look at more than one year of accounts and consider land equity where it is available. Instant asset write-off and depreciation rules change from year to year, so we work with your accountant on timing rather than promising a tax outcome.
The cash-flow pattern we plan around
Costs spread across the growing season with income concentrated into a harvest, shearing or livestock sale window, sometimes only once a year.
What agriculture typically fund
- Tractors, headers and implements
- Irrigation and water infrastructure
- Seed, fertiliser and chemical before planting
- Livestock purchase and handling equipment
- Silos, sheds and on-farm storage
Documents lenders usually ask for
- ABN and land ownership or lease details
- Two years of tax returns and financials
- Machinery quote or livestock purchase details



A clear next step
How to get finance for agriculture.
Our AI helps check lender fit across 48+ lenders. Your broker reviews the options and explains what they mean for you.
- 01
Machine and calendar
What you are buying, and when income actually lands across your production cycle.
- 02
Build the schedule
Your broker sets annual, seasonal or monthly repayments and any deferred start with lenders that support them.
- 03
Settle before the season
The financier pays the dealer or seller so the machine is on farm when it is needed.
The lender makes the final credit decision. Available options depend on your business and the lender’s assessment.
Before you make a decision
Estimate agricultural equipment finance repayments.
Know what lands and what leaves. Adjust the amount, rate and term to see the repayment and total cost.
- Number of repayments
- 48
- Total interest (est.)
- $13,904
- Total repaid (est.)
- $88,904
This calculator is a guide only. It uses simplified assumptions, excludes fees and charges unless stated, and is not an offer or quote. Actual repayments are confirmed by the lender in its loan contract.
From Lyft Money clients
Clear advice.
People who stay in touch.
Rated 5.0 from 340 Google reviews across the types of finance we arrange. Read them on Google.
“keeping us informed every step of the way”
“He explained all the financing options clearly”
“helped out my business”
Finance options for agriculture
Agricultural equipment finance
Agricultural equipment finance is where the seasonal structures live. A header used for four weeks a year can be written over five to seven years with a single annual repayment timed a month after the crop is sold, so the machine is paid for out of the income it helped produce.
Chattel mortgage
A chattel mortgage suits a farming business that intends to keep a machine for its full working life. You own the tractor or spray rig from settlement, claim the GST on the purchase in the relevant BAS, and depreciate the asset while deducting interest.
Equipment loan
Not every farm purchase is a tractor. Silos, augers, cattle crushes, sheds and pumps are all financeable under a general equipment loan, often at smaller amounts and shorter terms.
Business line of credit
Input costs for a cropping season land months before income does. A line of credit lets a farm draw for fertiliser and chemical at planting, add fuel and contractor costs through the season, then clear the balance after the crop is sold.
Secured business loan
Where a farm carries land equity, a secured business loan is generally the cheapest money available for a larger purpose — buying an adjoining paddock, building storage, or consolidating a mix of machinery debts onto one longer term. Rates sit well below unsecured lending because the property backs the facility.
Commercial property loan
Buying additional farmland, a set of silos with an access agreement, or a commercial shed on a nearby industrial block usually falls under a commercial property loan rather than a residential one. Deposits are larger than for a house — often 30% or more on rural land — and lenders assess the income the property will generate alongside the farm accounts.
Assets we finance for agriculture
Lenders active in this space
Metro Finance, FlexiCommercial — among others on our panel of 48+. Your broker checks fit before anything is submitted.
Key terms
Agricultural equipment finance
Agricultural equipment finance is secured lending for farm machinery such as tractors, headers, sprayers and irrigation systems, commonly written over three to seven years with annual or seasonal repayments aligned to harvest income.
Seasonal repayment structure
A seasonal repayment structure is a loan schedule where repayments fall due when farm income arrives — annually after harvest or in set months — rather than in equal monthly instalments.
Can farm finance repayments be matched to harvest or livestock sales?
Yes. Agricultural lenders offer seasonal, half-yearly and annual repayments so machinery and working capital are paid for when grain, wool, livestock or milk income arrives rather than monthly, and some allow a repayment holiday while a crop is in the ground. Tell your broker when income arrives and the structure is built around it.
How do farmers fund inputs between planting and harvest?
A seasonal line of credit or a working capital loan secured against the farm covers seed, fertiliser, chemicals, fuel and contractors through the growing season and is repaid from the harvest. Some input suppliers offer finance, and a broker compares it against the panel. Livestock producers use the same structure across the sale cycle.
Can I finance machinery bought at a clearing sale?
Yes. Clearing sale and private purchases are financed with a PPSR clearance, an inspection and a signed sale agreement, and lenders are relaxed about the age of tractors and headers from major brands. Pre-approval before the sale lets you bid with confidence and settle to the vendor within days.
Can I buy the neighbouring farm or more land with finance?
Yes. Rural property loans fund land purchases, water entitlements and farm improvements against the value of the land and the enterprise’s earnings, usually over 15 to 30 years. Lenders look at the farm’s history, the combined operation’s cash flow and equity. Lyft Money works with agribusiness lenders as well as the major banks.
How do seasonal repayments work on farm equipment finance?
Seasonal repayments schedule the bulk of the annual repayment to land after harvest, sale of livestock or other income events, with smaller or no payments in the months when cash is going out. A cropping operation might make one or two large payments a year after grain is delivered, while a dairy might pay monthly. Lenders that specialise in agriculture offer annual, half-yearly, quarterly and stepped structures. Your broker builds the schedule around your calendar.
What farm equipment can be financed?
Tractors, headers and harvesters, seeders and planters, sprayers, balers and hay equipment, irrigation pivots and pumps, grain handling and storage, livestock handling and shearing equipment, dairy plant, orchard and viticulture machinery, farm vehicles, drones and precision agriculture technology. New equipment from dealers and used machinery from dealers, clearing sales and private sellers are all financed.
Can I finance used farm machinery from a clearing sale or private seller?
Yes. Used tractors, headers and implements hold value well and are financed routinely, including from clearing sales and private sales with a PPSR check and an inspection or valuation. Most lenders allow machinery to be 15 to 20 years old at the end of the term, longer than for vehicles. For a clearing sale, a pre-approval lets you bid knowing what you can settle.
Should I set a balloon on farm equipment finance?
Headers, tractors and self-propelled machinery hold value well, so a balloon of 20 to 40 per cent is common and keeps the annual repayment down, with the machine traded to clear the balloon at the end. Implements and irrigation infrastructure that stay on the farm for their full life suit a low or zero balloon. Your broker sets the balloon against the machine’s expected value and your replacement plan.
How do lenders assess a farming business for equipment finance?
Specialist agricultural lenders look at the enterprise as a whole: land owned or leased, the history of yields or livestock sales, forward contracts, existing debt and the equipment’s role in production. Established farming families with a track record are generally well regarded, and lenders understand that income arrives in lumps. Low-doc equipment finance is available for established operations within limits, and larger purchases use financials.
Can irrigation and on-farm infrastructure be financed?
Yes. Centre pivots, lateral movers, pumps, pipelines, grain silos, sheds, solar systems and water infrastructure can be financed, often over longer terms of up to seven years or more because they have long working lives. Because some of this becomes a fixture of the land, lenders may take it as part of a broader agribusiness facility rather than as standalone equipment. Your broker structures whichever suits.
Your business. Your decision.
See your options.
Know the costs.
Decide with confidence.
One broker to explain it. Clear numbers before you proceed.
No obligation to proceed.