
Industry guide
Finance for mining services, shaped around how you get paid.
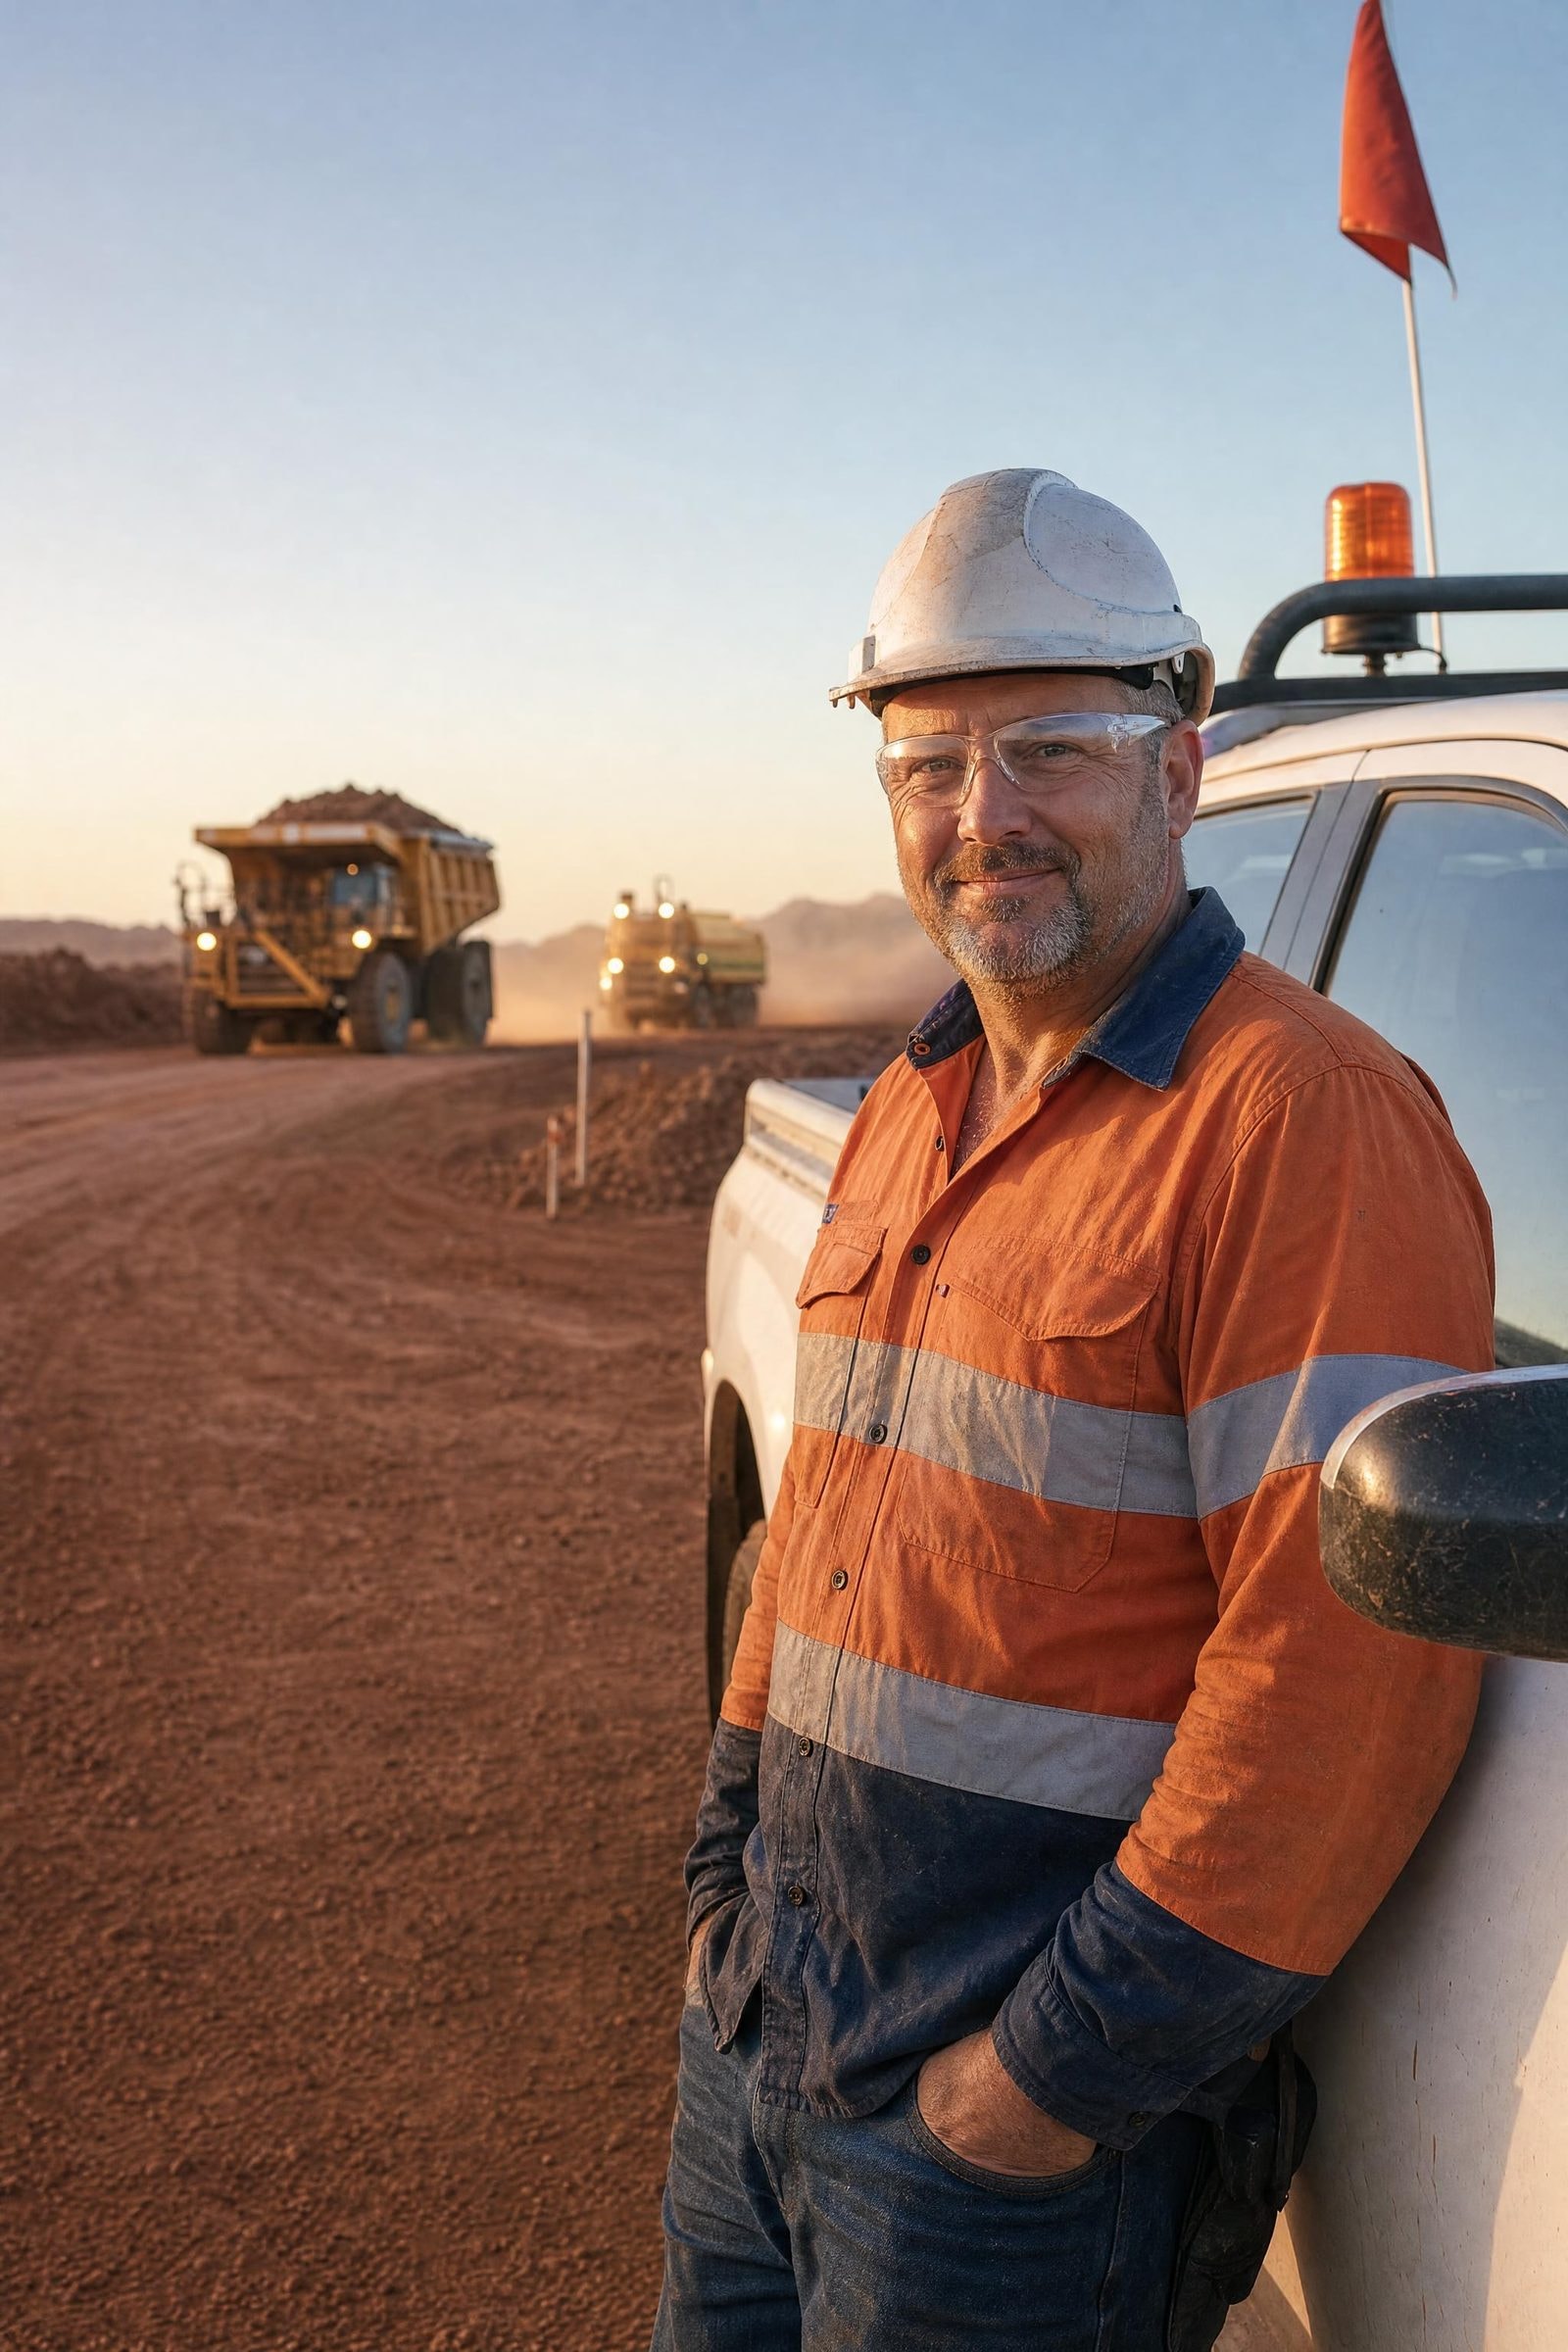
Mining services businesses win contracts that demand fleet on site within weeks. The finance question is almost always how to fund mobilisation without over-committing past the end of the contract.
 340 client reviews



One broker from your first call through to funding.
See which options fit your business.
Tell us what you need. A Lyft Money broker who knows mining services compares 48+ lenders and explains the rate, fees and repayments before you decide.
Access to 33+ mining services lenders
Lenders on our panel that fund mining services.
































At a glance
Mining services: the numbers that matter.
- Typical amounts
- $5,000 – $5,000,000
- Typical speed
- Same day to 48 hours for low-doc
- Indicative rates
- 6.9% – 16% p.a.
- Finance options
- 6 structures compared
- Lenders active here
- 3+ on our panel
- Assets we fund
- Wheel loader, Ute, Generator and more
In plain English
Finance for mining services: how it works.
Mining services finance is contract-driven lending for the plant, haulage and light vehicle fleets that support mine sites, structured so repayments and asset terms line up with the length of the contract being serviced.
A contractor awarded work at a Hunter Valley coal operation or a Pilbara iron ore site typically needs compliant, mine-spec vehicles and plant available on a fixed start date. That means light vehicles fitted out to site standard, water carts, loaders, service trucks and often accommodation and generators. The spend lands months before the first monthly claim is paid, and the client is usually a large miner with rigid procurement and 45-day terms.
Contract length drives everything. A three-year term contract supports three-to-five-year asset finance comfortably; a twelve-month scope with an option to extend does not, and a business that finances a fleet over five years against a one-year contract is taking a real risk. Lenders on our panel that are active in mining services will ask to see the contract or letter of award. Commodity cycles also matter — appetite tightens quickly when prices fall — so having a facility in place before you need it is worth more in this sector than most.
The cash-flow pattern we plan around
Large mobilisation spend up front, then monthly claims to a major mining client on 30–45 day terms for the life of the contract.
What mining services typically fund
- Mine-spec light vehicle fleets
- Loaders, water carts and support plant
- Service trucks and workshop equipment
- Mobilisation and camp establishment costs
Documents lenders usually ask for
- ABN and contract or letter of award
- 12 months of bank statements and latest financials
- Fleet or plant schedule with quotes



A clear next step
How to get finance for mining services.
Our AI helps check lender fit across 48+ lenders. Your broker reviews the options and explains what they mean for you.
- 01
Asset and supplier details
Quote or invoice, asset age and condition.
- 02
Match the lender
Specialist vs bank, low-doc vs full-doc.
- 03
Settle
Funds paid to the supplier; you take delivery.
The lender makes the final credit decision. Available options depend on your business and the lender’s assessment.
Before you make a decision
Estimate equipment loan repayments.
Know what lands and what leaves. Adjust the amount, rate and term to see the repayment and total cost.
- Number of repayments
- 48
- Total interest (est.)
- $15,443
- Total repaid (est.)
- $90,443
This calculator is a guide only. It uses simplified assumptions, excludes fees and charges unless stated, and is not an offer or quote. Actual repayments are confirmed by the lender in its loan contract.
From Lyft Money clients
Clear advice.
People who stay in touch.
Rated 5.0 from 340 Google reviews across the types of finance we arrange. Read them on Google.
“keeping us informed every step of the way”
“He explained all the financing options clearly”
“helped out my business”
Finance options for mining services
Equipment loan
Loaders, water carts, lighting towers and service plant for mine sites are financed against the asset, which keeps pricing sensible even for a business with a short trading history but a strong contract. The key decision is term: a five-year loan on a machine dedicated to a two-year scope leaves you with repayments and no revenue if the contract is not extended.
Fleet finance
Mine-spec light vehicles come in batches — ten or twenty utes fitted with roll bars, beacons, isolators and radios — and financing them one by one is slow and expensive. A fleet facility gives you an approved limit to draw against as vehicles are delivered, with one credit assessment covering the lot.
Chattel mortgage
A chattel mortgage gives your business ownership of the vehicle or machine from day one, with the GST on the purchase price generally claimable upfront and interest and depreciation deductible. For mining services this suits core plant you expect to redeploy across multiple contracts — a service truck or a workshop crane — rather than gear bought for one specific scope.
Invoice finance
Mining clients pay reliably but slowly, and their invoices are exactly what invoice finance is built for. A facility advancing against claims to a listed miner turns a 45-day wait into same-week cash, which funds the next payroll and the next mobilisation.
Business line of credit
A revolving limit covers the awkward months: demobilising one site while establishing another, or funding a shutdown crew before the claim goes in. Draw when the spend hits, repay when the monthly claim clears, keep the facility available for the next award.
Operating lease
An operating lease keeps the asset off your balance sheet and hands the residual value risk to the financier, which is the right shape when plant is bought for a defined contract with no certainty of renewal. Payments are fully deductible as an operating expense and you return the asset at the end rather than trying to sell mine-worn gear into a soft market.
Assets we finance for mining services
Lenders active in this space
Metro Finance, FlexiCommercial, ScotPac — among others on our panel of 48+. Your broker checks fit before anything is submitted.
Key terms
Mining services equipment finance
Mining services equipment finance is secured lending for the vehicles and plant used to service mine sites, where the finance term is set against the length of the client contract rather than the maximum life of the asset.
Contract-matched term
A contract-matched term is a finance term deliberately set no longer than the contract generating the income, reducing the risk of carrying repayments on idle plant after a scope ends.
How is mining services equipment financed against a contract?
Lenders match the finance term to the length of the mining contract being serviced, with balloons or operating leases used so the repayment fits the contract and the equipment can be returned or refinanced at the end. Plant, haulage, light vehicle fleets and site accommodation are all financed this way. The signed contract is the key document.
What do lenders want to see from a mining services business?
The contract or purchase order with the mine, a history of claims paid in the bank statements, financials for larger amounts, the equipment list and evidence of site compliance. Lenders like contracted work with major miners, so a broker presenting the contract and margins clearly speeds approval.
Can I finance a fleet of mine-spec utes and light vehicles?
Yes. Fleet finance covers mine-spec utes, buses and light trucks with the safety fit-out included, under a master facility that lets vehicles be added as crews grow, often with fleet pricing and a rental or lease option so vehicles are replaced at the end of each contract.
How do mining contractors fund mobilisation and monthly claims?
A working capital facility or invoice finance against monthly claims to the mining client covers wages, fuel and accommodation until claims are paid 30 to 45 days later. Because the debtors are large miners, invoice finance is well priced and can advance up to 90 per cent of each claim within a day or two.
Do I need a deposit for equipment finance?
Often no deposit is required, particularly for established businesses buying standard assets from a dealer. A deposit is more likely where the business is new, the asset is older or specialised, the credit profile is weaker, or the amount is large relative to turnover. Deposits typically range from around 10% to 30% in those cases. Putting money in reduces the amount financed and can improve the terms offered, but it is not always necessary.
Can I finance equipment I already own to release cash?
Yes, that is a sale and leaseback. You sell an unencumbered asset to a financier and lease or finance it back, receiving the sale proceeds as working capital while keeping the asset in use. Lenders will want proof you own it outright, a valuation, and evidence the funds are for a legitimate business purpose. It is a useful option when capital is tied up in plant, but it converts an owned asset into a monthly commitment, so the cash flow effect needs checking first.
How long can I finance equipment for?
Terms usually run from 12 to 84 months. The ceiling is generally set by the expected working life of the asset: heavy earthmoving and trucks often stretch to five or seven years, while IT hardware and point-of-sale systems are commonly kept to two or three. Lenders also look at the age of the asset at the end of the term, so a ten-year-old machine will attract a shorter term than a new one. Longer terms lower repayments and raise total interest.
Can one facility cover several pieces of equipment?
Yes. A master facility agreement lets a lender approve an overall limit, then draw down individual assets against it using a commitment schedule for each one. Each drawdown has its own term and repayment, but you avoid re-applying every time you buy. It suits businesses buying regularly through the year. Limits are usually reviewed annually and the lender can decline a particular asset even where the limit is available.
How long does my ABN need to be active?
It varies by lender and product. Many unsecured business lenders want at least six to twelve months of trading, while some asset finance lenders will consider a new ABN where the director has industry experience, a clean credit file and often property ownership or a deposit. Registration for GST is frequently expected once turnover reaches the threshold. A short ABN history is not an automatic decline, but it narrows the panel and usually affects the rate and structure offered.
Do I have to own property to get business finance?
No. Plenty of finance is written for non-property owners, especially asset finance where the equipment itself is the security, and unsecured lending assessed on cash flow. That said, property ownership widens the panel and often improves pricing, because it gives a lender an additional avenue if things go wrong. If you do not own property, expect more weight on trading history, bank conduct and the quality of the asset being financed.
Your business. Your decision.
See your options.
Know the costs.
Decide with confidence.
One broker to explain it. Clear numbers before you proceed.
No obligation to proceed.