
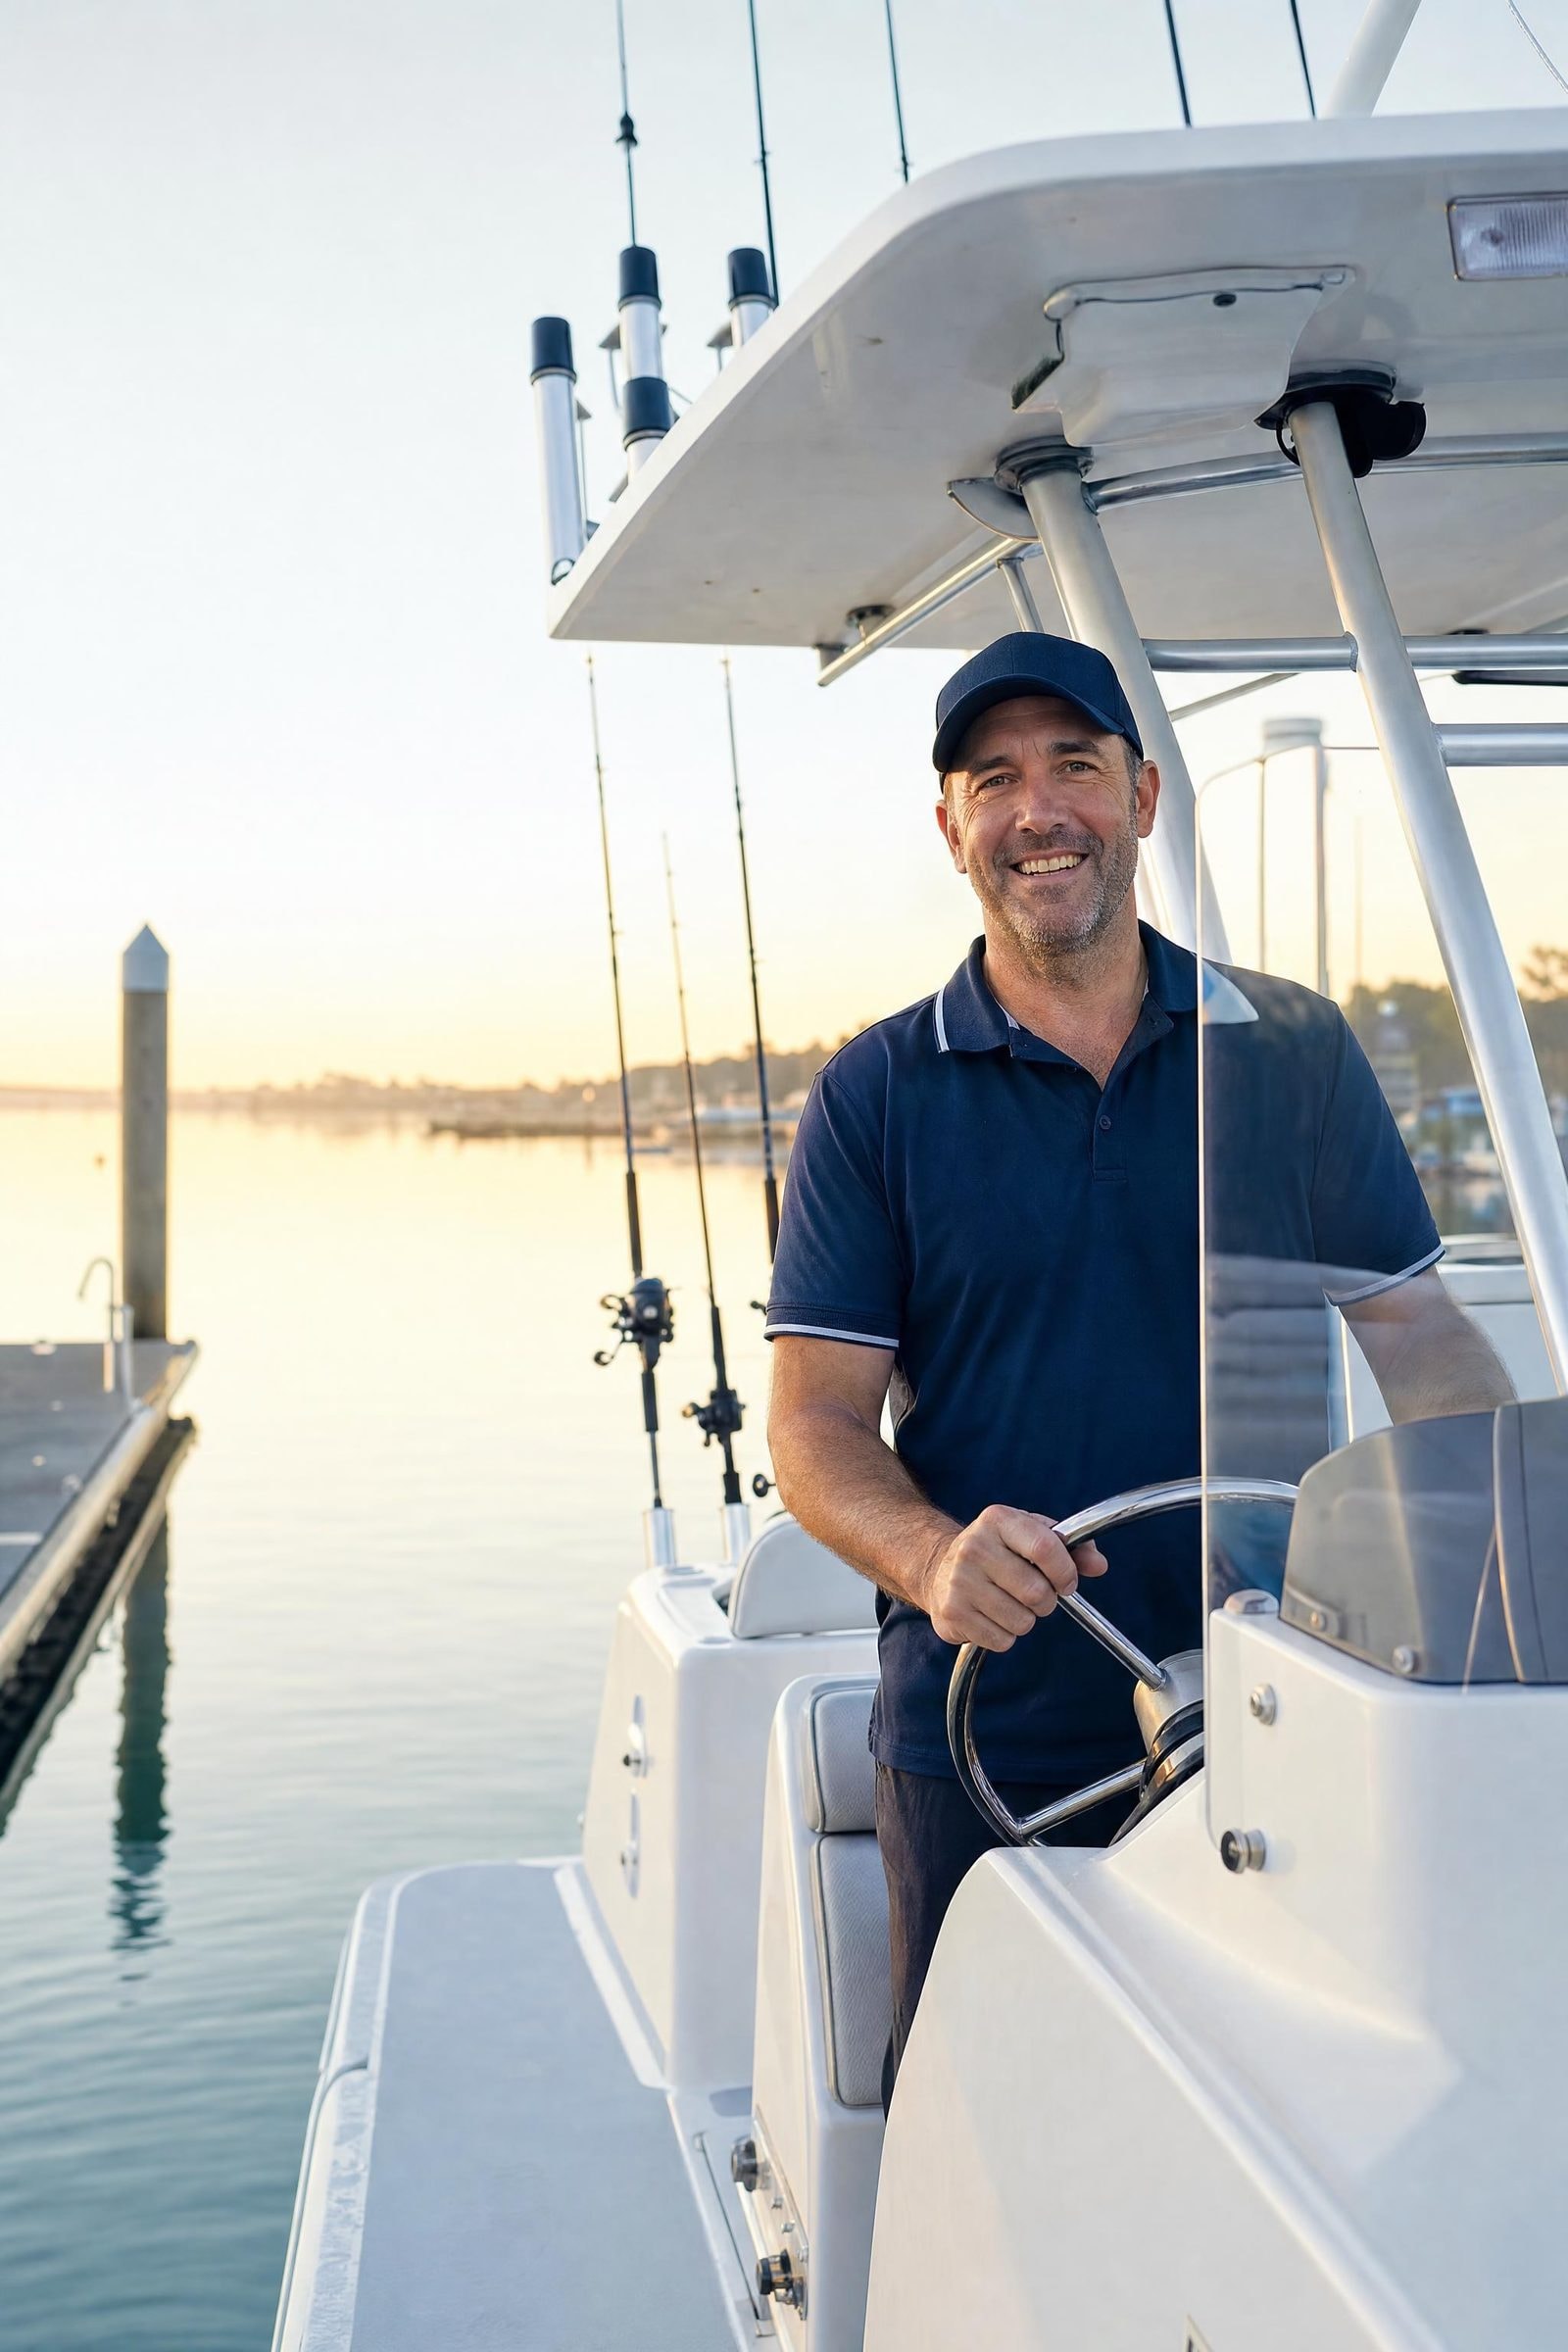
Personal and leisure assets
Boat finance from 48+ Australian lenders.
A boat loan is regulated consumer credit, which means proper disclosure and a suitability assessment. We compare lenders and explain exactly what you will pay.
 340 client reviews



One broker from your first call through to settlement.
See which boat finance options fit you.
Tell us what you need. A Lyft Money broker compares options across our lender panel and explains the comparison rate, fees and repayments before you apply. We are a credit assistance provider, not a lender.
Access to 25+ boat finance lenders
Lenders on our panel that fund boat finance.












At a glance
Boat finance: the numbers that matter.
- Typical price
- $20,000 – $300,000
- Terms
- Up to 84 months
- Indicative rates
- 8% – 22% p.a.
- Typical speed
- 2–5 business days
- Usual structure
- Leisure asset loan
- Useful life
- About 20 years
In plain English
What is boat finance?
Boat finance is a consumer loan used to buy a recreational vessel — a runabout, half cabin, plate alloy boat, cruiser or yacht — secured against the boat. In Australia it is regulated consumer credit, so the lender must assess the loan as suitable for your circumstances and disclose the rate and fees before you sign.
Australia has one of the highest rates of recreational boat ownership in the world, and the market splits clearly. Trailer boats — plate alloy and fibreglass runabouts in the five to seven metre range — dominate by volume and are used for fishing and family boating. Above that sit cruisers and yachts, which involve mooring or marina costs and a very different ownership commitment.
Because a boat loan is consumer credit, the process is different to business equipment finance. The lender must verify your income and living expenses and assess that the loan is not unsuitable for you. That is a protection, not an obstacle. Your broker will explain the comparison rate, any fees, and the total cost over the term, and will not present a loan you cannot comfortably afford.
How lenders assess boat finance
Boat loans are consumer credit, so lenders verify income and expenses and assess whether the repayments are affordable for you. Age matters: many lenders want the vessel under 15 to 20 years old at the end of the term, and older or timber vessels narrow the panel considerably. Trailer boats are simpler than moored vessels because they are easier to recover and value. Private sales need a PPSR check and payment to the registered owner. Rates are typically lower than an unsecured personal loan because the boat is security.
New or used
Used boats make up most sales and are widely financed; new boats attract sharper rates but depreciate significantly in the first few years.
Before you buy
- Budget for the whole picture — mooring or storage, insurance, servicing, antifoul and registration add up quickly after purchase.
- Get a marine survey on any used vessel over about $50,000; hull and engine issues are expensive and easy to hide.
- Check engine hours and service history; a repower on a large outboard or inboard can cost a third of the boat’s value.
Commonly financed
- Quintrex Renegade and Freestyler
- Stacer Ocean Ranger
- Haines Hunter 565R
- Bar Crusher 615C
- Sea Ray Sundancer



A clear next step
How to finance a boat.
Your broker checks lender fit across our panel, explains the comparison rate and total cost, and completes a responsible lending assessment before anything is submitted.
- 01
Identify the asset
Type, make, model, year and condition, and whether the purchase is from a dealer or a private seller.
- 02
Set deposit and term honestly
Your broker models negative equity across the term so the deposit and length reflect how long you will keep it.
- 03
Verify and settle
Income and expenses are verified under responsible lending rules, the PPSR is cleared, and the seller is paid directly.
- Photo ID and proof of address
- Payslips and 3 months of bank statements
- Sale contract or dealer invoice with HIN or VIN
The lender makes the final credit decision. Available options depend on your circumstances and the lender’s assessment.
Before you make a decision
Estimate your boat repayments.
Adjust the price, rate and term to see the repayment and total cost. Consumer loans are quoted with a comparison rate that includes most fees; your broker provides it before you apply.
- Number of repayments
- 60
- Total interest (est.)
- $55,980
- Total repaid (est.)
- $215,980
This calculator is a guide only. It uses simplified assumptions, excludes fees and charges unless stated, and is not an offer or quote. Actual repayments are confirmed by the lender in its loan contract.
From Lyft Money clients
Clear advice.
People who stay in touch.
Rated 5.0 from 340 Google reviews across the types of finance we arrange. Read them on Google.
“keeping us informed every step of the way”
“He explained all the financing options clearly”
“helped out my business”
Ways to finance a boat
Key terms
What is boat finance?
Boat finance is a consumer loan secured against a recreational vessel. Terms usually run 36 to 84 months, rates are lower than unsecured personal lending because the boat is security, and the loan is regulated under Australian consumer credit law.
What is a marine survey?
A marine survey is an independent inspection of a vessel’s hull, structure, systems and engine by a qualified surveyor. It identifies defects, confirms condition and supports the valuation. Many lenders and insurers require one on higher-value or older vessels.
Can I get a boat loan for a new or used boat?
Yes. Boat loans cover new and used trailer boats, cruisers, yachts and jet boats from dealers, brokers and private sellers, secured against the boat, with terms of up to seven years and amounts from around $10,000. The trailer and motor are included in the loan when bought together, and private sales need a PPSR check and inspection.
Are boat loan rates higher than car loans?
Slightly, on average, because boats depreciate less predictably and are used less often, but secured boat loans are still far cheaper than unsecured personal loans or credit cards. Rates depend on your credit profile, the boat’s age and value, the deposit and the term. A broker compares specialist marine lenders with the banks.
How old can a used boat be for finance?
Most lenders finance boats up to about 15 to 20 years old at the end of the term, with older or wooden boats handled by specialist lenders on shorter terms and a deposit. Condition, brand and a survey for larger vessels matter more than age alone.
Can I have a balloon on a boat loan?
Some lenders offer balloons of up to 30 per cent on new boats to lower the monthly repayment, with the balloon paid, refinanced or covered by selling the boat at the end. A balloon costs more in total interest, so it suits buyers who expect to upgrade. Your broker shows both repayments.
Can I finance a caravan, boat or motorbike for private use?
Yes. Leisure asset lending is available for caravans, camper trailers, boats, jet skis, motorbikes and horse floats, secured against the asset itself. Because these are bought for private use, the loan is regulated consumer credit with responsible lending obligations and a comparison rate. Terms are commonly up to seven years, sometimes longer for larger caravans and boats. Lenders consider the asset's age and type as well as your income and existing commitments.
How does boat or caravan finance work?
A leisure asset loan is a secured consumer loan where the boat, caravan, motorbike, jet ski or camper trailer is the security, which keeps the rate lower than an unsecured personal loan. Terms run from one to seven years, repayments are fixed, and a balloon can be set to lower the monthly cost. Lenders quote a comparison rate and assess affordability under responsible lending rules, and the asset must be insured for the term.
How much can I borrow for a boat, caravan or motorbike?
Leisure asset loans commonly range from $5,000 to $150,000 or more for large caravans and boats, with lenders financing up to the full purchase price for well-qualified borrowers and often including registration, insurance and accessories. The amount depends on your income and commitments under responsible lending rules and on the asset’s value. A deposit lowers the repayment and can improve the rate.
Can I finance a used boat or caravan from a private seller?
Yes. Private-sale boats, caravans and bikes are financed with a PPSR check to confirm no finance is owing, verification of the seller, and usually an inspection or valuation. Most lenders set an age limit at the end of the loan, which varies by asset type and is often longer for caravans than for jet skis. Allow a few extra days compared with a dealer purchase for the checks.
Do I have to insure the boat or caravan?
Yes. Lenders require comprehensive insurance on a secured leisure asset for the life of the loan, with the lender’s interest noted on the policy, and evidence is needed before settlement. Premiums can often be included in the amount financed. Your broker can point you to insurers who cover the asset type.
How quickly can boat or caravan finance be approved?
Conditional approval is often given within 24 to 48 hours of a complete application, with settlement to the dealer within a day or two of signing. Private sales take a few days longer for the PPSR check and inspection. If you are buying at a boat show or from a dealer with a deadline, tell your broker and approval can be arranged in advance.
Your money. Your decision.
See your options.
Know the costs.
Decide with confidence.
One broker to explain it. Clear numbers before you proceed.
No obligation to proceed.