
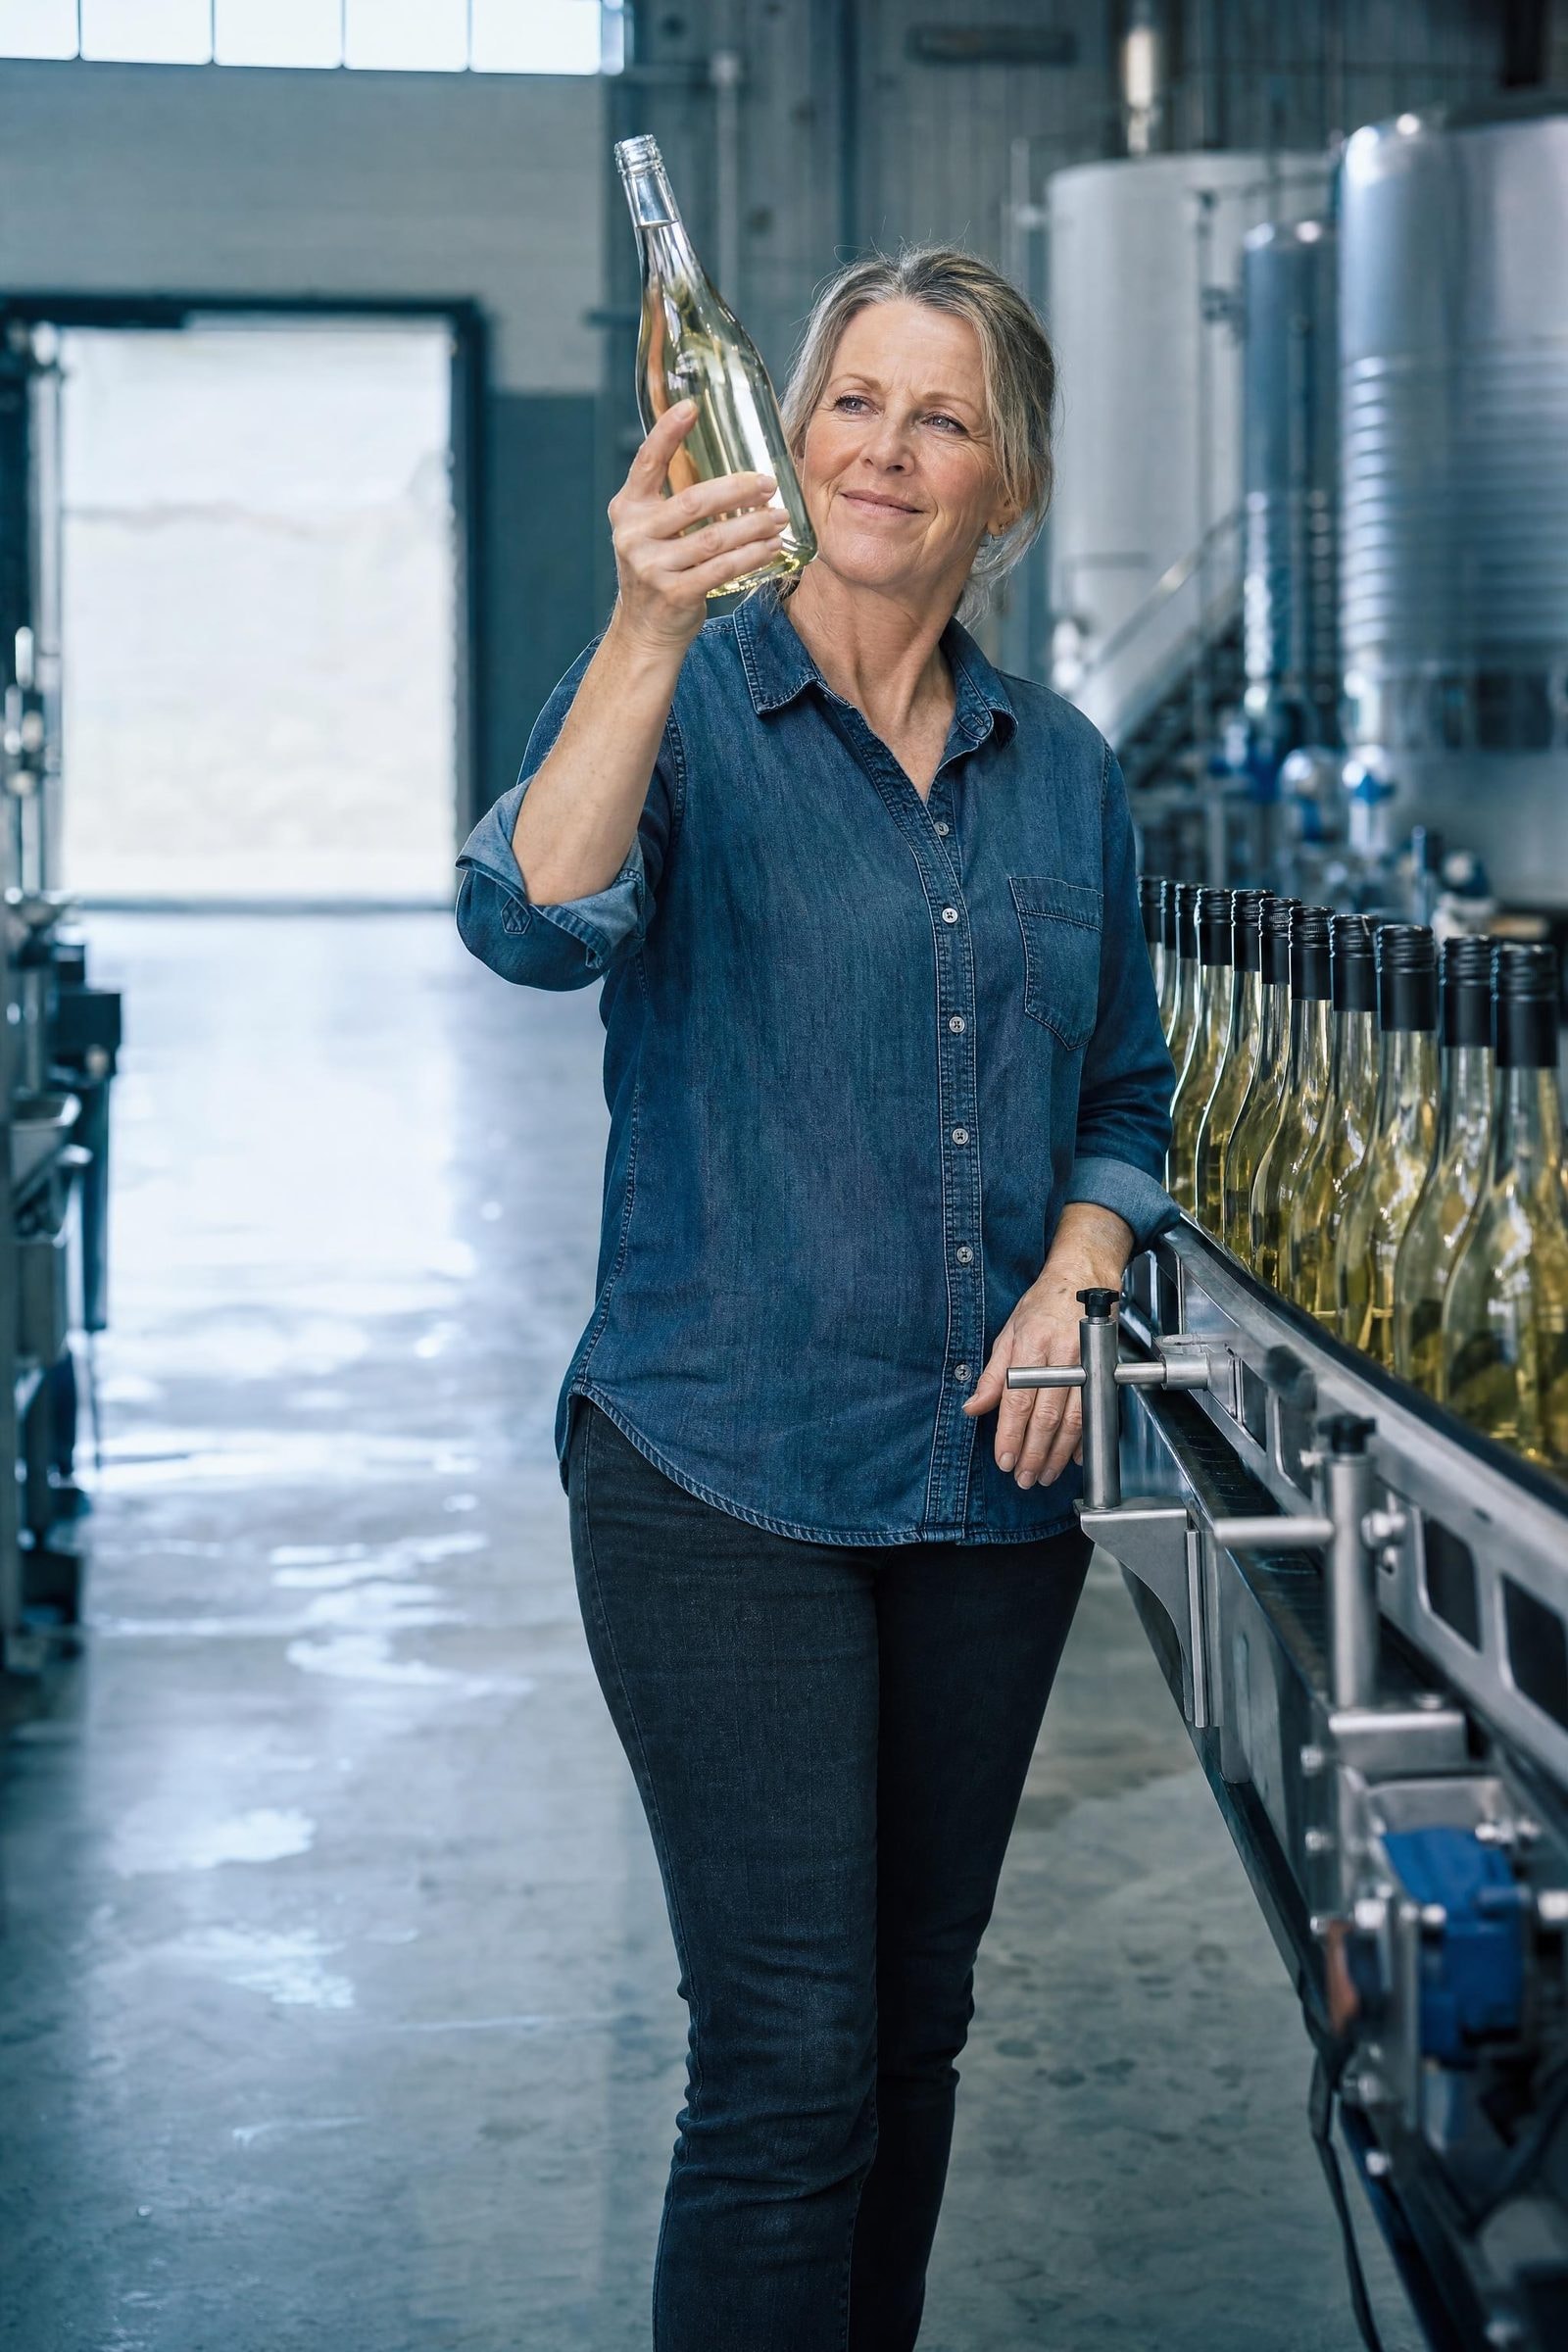
Release cash from gear you already own
Release the cash sitting in equipment you already own.
Sell owned plant to a financier, keep using it, and free up capital for the next contract. Your broker explains valuation, tax consequences and total cost first.
 340 client reviews



One broker from your first call through to funding.
See which sale and leaseback options fit your business.
Tell us what you need. A Lyft Money broker compares 48+ lenders and explains the rate, fees and repayments before you decide.
Access to 21+ sale and leaseback lenders
Lenders on our panel that fund sale and leaseback.





















At a glance
Sale and leaseback: the numbers that matter.
- Amount
- $20,000 – $2,000,000
- Term
- 12–60 months
- Indicative rates
- 8.5% – 18% p.a.
- Typical speed
- 3–10 business days including valuation
- Security
- Secured by the asset
- Repayments
- Monthly
Rates as at Q3 2026. See the rate history →
In plain English
What is a sale and leaseback?
Sale and leaseback is an arrangement where you sell equipment your business already owns to a financier for its market value and immediately lease or finance it back, releasing cash while keeping the asset in daily use. It converts equity locked in plant into working capital.
Plenty of businesses are asset-rich and cash-poor: two paid-off excavators in the yard and a payroll problem in the office. Sale and leaseback releases that equity without selling the gear that earns the revenue. The financier pays you an agreed value for the asset, registers its interest, and you continue operating it under a lease or chattel mortgage with regular repayments.
Financiers typically advance 60–80% of assessed market value, not the price you paid, and they want assets that are clearly identifiable, in good condition and free of existing encumbrances — a PPSR search will confirm that quickly. Most lenders limit leasebacks to equipment purchased within the last few years, and some restrict it to assets bought outright for cash rather than refinanced from another financier.
Two consequences deserve attention. The sale itself can trigger a balancing adjustment for tax if the sale price differs from the written-down value, so speak to your accountant before committing. And an asset that was previously cost-free now carries a monthly repayment — the capital is only worth releasing if it will earn more than the finance costs.
A good fit when
Asset-rich businesses needing working capital for growth, a contract or a tax liability
Consider something else if
Older, low-value or specialised equipment with a thin resale market
Advantages
- Releases capital without losing the use of the asset
- Priced as secured finance, not unsecured lending
- No property security required
Trade-offs
- Advance is based on market value, often well below cost
- A previously cost-free asset now carries repayments
- Potential tax balancing adjustment on the sale



A clear next step
How to apply for a sale and leaseback.
Our AI helps check lender fit across 48+ lenders. Your broker reviews the options and explains what they mean for you.
- 01
List the assets
Make, model, year, hours or kilometres, condition and proof that each is owned outright.
- 02
Valuation and offer
The financier assesses market value and runs a PPSR search, then confirms the amount it will advance.
- 03
Settle and continue trading
Funds are paid to your business, the security interest is registered, and the equipment keeps working.
- Original purchase invoices proving ownership
- Asset schedule with serial numbers, hours and condition
- Bank statements and financials
The lender makes the final credit decision. Available options depend on your business and the lender’s assessment.
Before you make a decision
Estimate your sale and leaseback repayments.
Know what lands and what leaves. Adjust the amount, rate and term to see the repayment and total cost.
- Number of repayments
- 48
- Total interest (est.)
- $19,802
- Total repaid (est.)
- $94,802
This calculator is a guide only. It uses simplified assumptions, excludes fees and charges unless stated, and is not an offer or quote. Actual repayments are confirmed by the lender in its loan contract.
From Lyft Money clients
Clear advice.
People who stay in touch.
Rated 5.0 from 340 Google reviews across the types of finance we arrange. Read them on Google.
“keeping us informed every step of the way”
“He explained all the financing options clearly”
“helped out my business”
What people finance with a sale and leaseback
Lenders we compare for this
Banjo Loans, ScotPac, FlexiCommercial, Shift, Angle Asset Finance, Metro Finance, Pepper Money and others on our panel. See the full panel.
Key terms
What is sale and leaseback?
Sale and leaseback is a transaction where a business sells an asset it owns to a financier and simultaneously leases or finances it back, retaining full use of the asset while converting its value into cash.
How much can you raise through equipment leaseback?
Financiers generally advance 60–80% of an asset’s assessed market value, based on age, condition, hours and resale demand rather than the original purchase price. A valuation or inspection is usually required.
What is a PPSR search?
A PPSR search checks the Personal Property Securities Register for existing security interests over an asset. Financiers run one before a leaseback to confirm the equipment is genuinely unencumbered and can be sold.
How does a sale and leaseback work?
A sale and leaseback releases cash from equipment your business already owns outright. A financier buys the asset from you at an agreed value, pays you the cash, and leases or finances it straight back so you keep using it without interruption. You then make regular repayments over a term, typically one to five years, and at the end you own the asset again or clear a residual. It turns idle equity in trucks, machinery or plant into working capital for a contract, growth or a tax liability.
What equipment qualifies for a sale and leaseback?
Equipment that is owned outright or nearly paid off, has a clear resale market and a reasonable remaining life: trucks and trailers, excavators and earthmoving plant, manufacturing machinery, bottling and production lines, agricultural machinery, medical equipment and fleets of vehicles. Lenders check the PPSR to confirm there is no finance owing and value the asset. Very old, specialised or low-value equipment is harder to fund because the lender relies on the asset’s resale value.
What are the tax consequences of a sale and leaseback?
Selling the asset to the financier is a disposal for tax purposes, which can trigger GST on the sale price and a balancing adjustment if the sale price differs from the asset’s written-down value. The lease or finance payments that follow are generally deductible, and GST on them can be claimed. The net effect depends on how the asset has been depreciated, so the arrangement should be reviewed with your accountant before you proceed; your broker provides the figures they need.
Is a sale and leaseback cheaper than an unsecured business loan?
Usually, yes. Because the financier holds security over the equipment, sale and leaseback is priced like asset finance rather than unsecured lending, which can be materially cheaper for a business that would otherwise be quoted unsecured rates. It also allows longer terms, so the repayment is lower. The costs to weigh against that are the valuation, the establishment fee and any tax consequences of the sale.
Can I use a sale and leaseback to pay an ATO debt or fund a new contract?
Yes, both are common uses. Because the funds are unrestricted working capital, businesses use them to clear a tax debt, fund the mobilisation costs of a new contract, buy stock, or consolidate more expensive short-term debt. Lenders will ask what the funds are for and may want to see that the business is trading profitably.
How long does a sale and leaseback take?
Three to ten business days, mostly for the valuation and the PPSR and ownership checks. Once the valuation is agreed, documents are signed, the financier pays the agreed amount to your account and the repayments begin. If the funds are for a deadline such as a tax payment or contract start, tell your broker and the valuation is booked immediately.
Can I finance equipment I already own to release cash?
Yes, that is a sale and leaseback. You sell an unencumbered asset to a financier and lease or finance it back, receiving the sale proceeds as working capital while keeping the asset in use. Lenders will want proof you own it outright, a valuation, and evidence the funds are for a legitimate business purpose. It is a useful option when capital is tied up in plant, but it converts an owned asset into a monthly commitment, so the cash flow effect needs checking first.
Can I refinance machinery I already own to release cash?
Yes. Unencumbered machinery can be refinanced through a sale-and-leaseback or a loan secured on the equipment, releasing a proportion of its value as working capital while you keep using it. Lenders value the machine and lend against it, typically 50 to 80 per cent of value depending on age and type. It is a useful way to fund growth without selling the gear that earns the income.
Can I refinance a fit-out I have already paid for?
Sometimes. Equipment bought in the last few months can often be refinanced with a sale-and-leaseback, releasing the cash back into the business. Fixed works already paid for are harder to refinance because there is no asset to secure, though a business loan can be considered for an established business. It is usually cheaper to arrange the finance before paying, so speak to your broker before the build starts.
How much cash can I release from my equipment?
Typically 50 to 80 per cent of the asset’s valued amount, depending on its type, age and how readily it could be resold. Newer trucks and yellow goods sit at the higher end; older or more specialised machinery at the lower end. The lender arranges an independent valuation, and the amount is agreed before you commit. Several assets can be bundled into one arrangement to release a larger sum.
Your business. Your decision.
See your options.
Know the costs.
Decide with confidence.
One broker to explain it. Clear numbers before you proceed.
No obligation to proceed.