
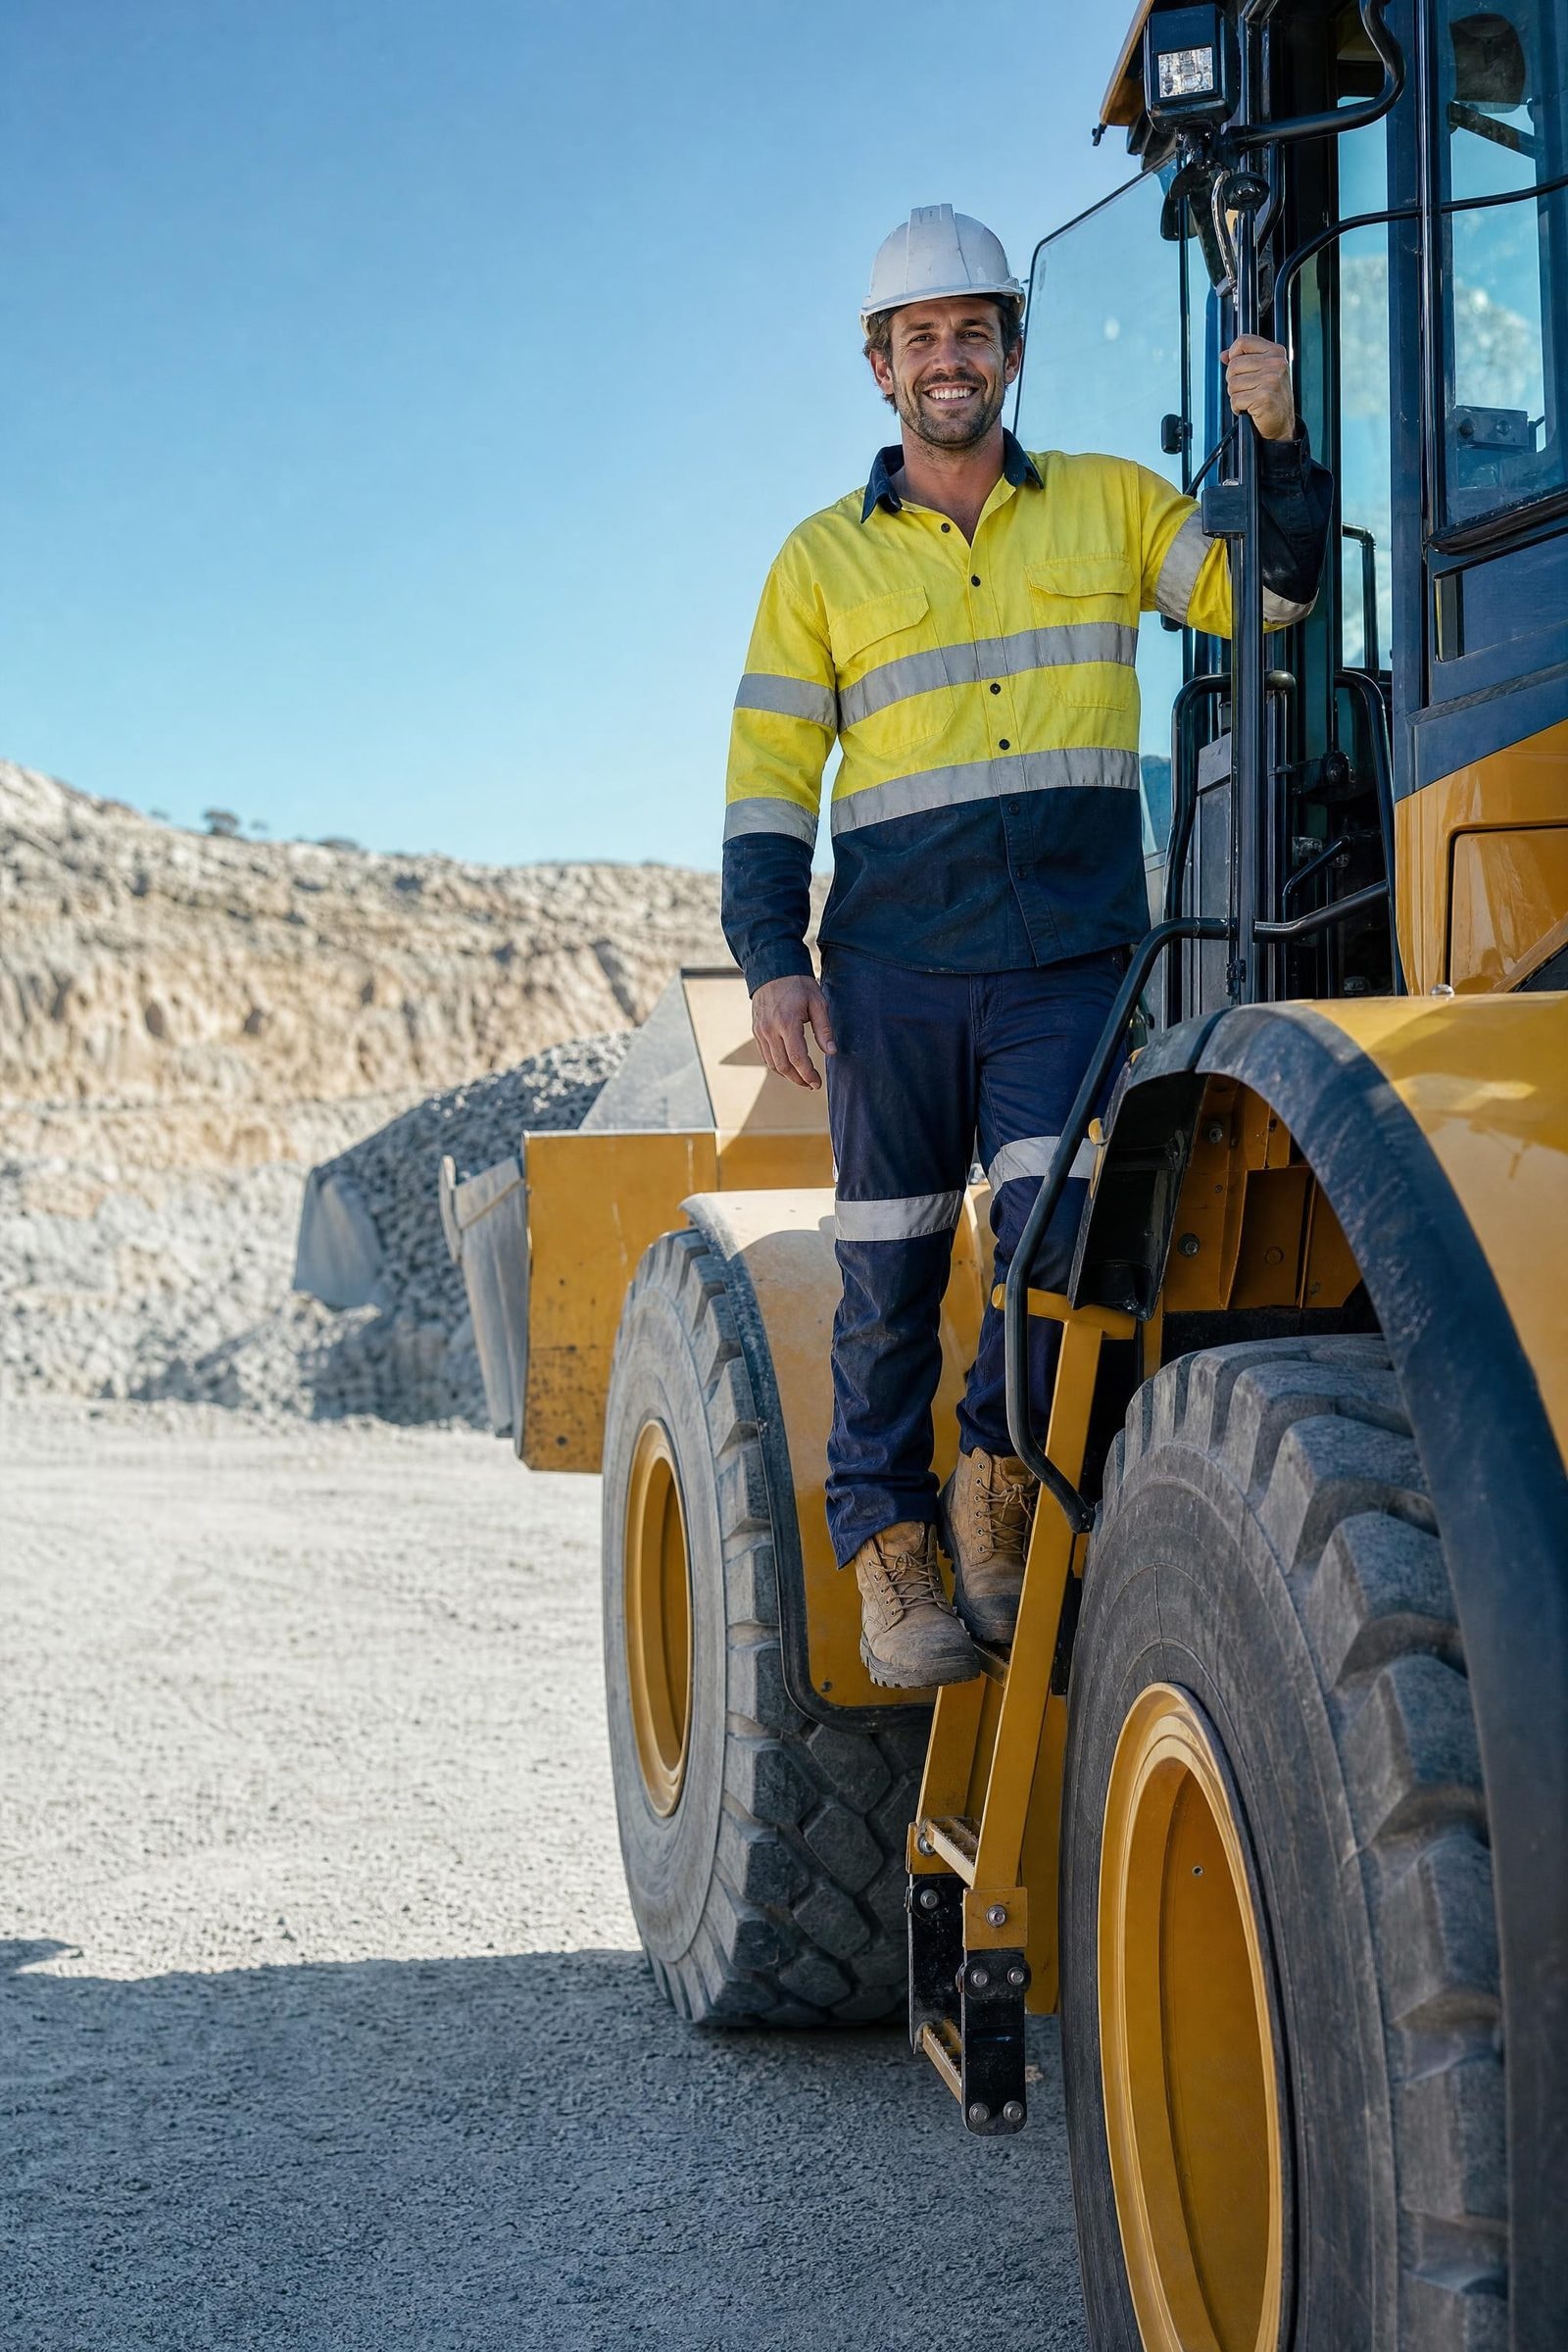
Yellow goods, plant and production machinery
Machinery finance for excavators, loaders, CNC plant and production lines.
Specialist lenders that understand hours, attachments and resale values. Your broker structures the term around the work the machine is winning.
 340 client reviews



One broker from your first call through to funding.
See which machinery finance options fit your business.
Tell us what you need. A Lyft Money broker compares 48+ lenders and explains the rate, fees and repayments before you decide.
Access to 21+ machinery finance lenders
Lenders on our panel that fund machinery finance.





















At a glance
Machinery finance: the numbers that matter.
- Amount
- $20,000 – $3,000,000
- Term
- 12–84 months
- Indicative rates
- 7.2% – 16.5% p.a.
- Typical speed
- 24–72 hours for low-doc, up to a week for full-doc or private sales
- Security
- Secured by the asset
- Repayments
- Monthly
Rates as at Q3 2026. See the rate history →
In plain English
What is machinery finance?
Machinery finance is secured lending used to buy earthmoving plant, construction equipment and production machinery, with the machine itself as security over terms of one to seven years. Lenders assess the machine’s age, hours and resale demand as closely as they assess the business.
Heavy machinery holds value differently from vehicles. A well-maintained twenty-tonne excavator with 6,000 hours can be worth more than a five-year-old ute, which is why specialist financiers will fund machines a mainstream lender would refuse. They price on hours, brand, attachments and how deep the second-hand market is — a common-spec Komatsu or Caterpillar is easier to fund than a rare import with limited parts support.
Term structure matters as much as rate. A machine bought for a three-year civil contract should generally not be financed over seven years with a large balloon, because the revenue stops before the debt does. Conversely, financing a long-life machine over two years can create repayments the job cannot carry. Your broker sets the term against the work the machine is actually winning and the hours it will accumulate.
Private sales and auction purchases are well supported on our panel, with the usual conditions: PPSR clear, a proper inspection, and funds paid to the seller on settlement rather than in advance. Attachments — buckets, hammers, tilt hitches, GPS systems — can usually be included in the same facility if they are on the same invoice.
A good fit when
Civil, construction, mining services and manufacturing businesses buying productive plant
Consider something else if
Highly specialised one-off machines with no established resale market
Advantages
- Specialist lenders fund older machines mainstream banks decline
- Auction and private-sale purchases supported
- Attachments can be included in the same facility
Trade-offs
- High-hour machines attract shorter terms and higher rates
- Private sales require inspection and PPSR clearance before settlement
- Term mismatched to contract length creates repayment risk



A clear next step
How to apply for machinery finance.
Our AI helps check lender fit across 48+ lenders. Your broker reviews the options and explains what they mean for you.
- 01
Machine and job details
Make, model, year, hours, attachments and the contract or work the machine will service.
- 02
Structure to the work
Your broker sets term, deposit and balloon against the machine’s life and the revenue it will generate.
- 03
Inspection and settlement
PPSR search, inspection where required, then the financier pays the seller directly.
- Invoice or auction contract with serial number
- Service history and hour meter reading for used machines
- Bank statements or financials depending on the amount
The lender makes the final credit decision. Available options depend on your business and the lender’s assessment.
Before you make a decision
Estimate your machinery finance repayments.
Know what lands and what leaves. Adjust the amount, rate and term to see the repayment and total cost.
- Number of repayments
- 48
- Total interest (est.)
- $16,651
- Total repaid (est.)
- $91,651
This calculator is a guide only. It uses simplified assumptions, excludes fees and charges unless stated, and is not an offer or quote. Actual repayments are confirmed by the lender in its loan contract.
From Lyft Money clients
Clear advice.
People who stay in touch.
Rated 5.0 from 340 Google reviews across the types of finance we arrange. Read them on Google.
“keeping us informed every step of the way”
“He explained all the financing options clearly”
“helped out my business”
What people finance with machinery finance
Lenders we compare for this
Banjo Loans, ScotPac, FlexiCommercial, Shift, Angle Asset Finance, Metro Finance, Pepper Money and others on our panel. See the full panel.
Key terms
What is machinery finance?
Machinery finance is asset-backed business lending for plant and production equipment such as excavators, loaders, telehandlers, CNC machines and packaging lines. The machine secures the loan, usually under a chattel mortgage or finance lease.
Can you finance used machinery?
Yes. Most specialist lenders fund used plant, including auction and private-sale purchases. Machine hours, service history and a clear PPSR search matter more than age alone, though many lenders cap the asset’s age at the end of the term.
How do hours affect machinery finance?
Hours are the primary measure of a machine’s remaining life and resale value. High-hour machines attract shorter terms, larger deposits and higher rates because the security depreciates faster and sells for less.
Can attachments and delivery be included in machinery finance?
Yes. Buckets, rippers, tilt hitches, augers, GPS machine-control systems, installation, commissioning and delivery can all be included in the amount financed when they are on the supplier’s invoice. Bundling them keeps the whole cost of putting the machine to work on one repayment rather than draining cash for the extras.
Should I set a balloon on machinery finance?
A balloon of 20 to 40 per cent is common on machinery with strong resale value, such as excavators and loaders, because it lowers the monthly repayment and the machine can be sold or traded to clear the balloon at the end. Production machinery that will stay in the factory for its full life usually suits a low or zero balloon. Your broker sets the balloon against the machine’s expected value at the end of the term.
Can I get low-doc machinery finance?
Yes, for established businesses. Low-doc machinery finance is generally available up to around $150,000 to $250,000 for an ABN of two years or more with a clean credit file, often without financials, and some specialist lenders go higher for standard yellow goods. Larger amounts or newer businesses provide recent financials or bank statements, and a contract for the work the machine will do strengthens any application.
How quickly can machinery finance be approved?
Low-doc applications for standard machines are often approved within 24 to 72 hours. Full-doc applications, larger amounts and private sales requiring inspection take up to a week. For machines on order with a supplier, approval can be arranged ahead of delivery so settlement happens the day the machine is ready.
How long can I finance equipment for?
Terms usually run from 12 to 84 months. The ceiling is generally set by the expected working life of the asset: heavy earthmoving and trucks often stretch to five or seven years, while IT hardware and point-of-sale systems are commonly kept to two or three. Lenders also look at the age of the asset at the end of the term, so a ten-year-old machine will attract a shorter term than a new one. Longer terms lower repayments and raise total interest.
What machinery can be financed?
Earthmoving and civil plant such as excavators, loaders, dozers, graders and rollers; manufacturing plant such as CNC mills and lathes, presses, laser cutters and production lines; cranes, forklifts and telehandlers; concrete, asphalt and crushing equipment; woodworking, printing and packaging machinery; and agricultural machinery. New and used machines are financed, with lenders that specialise in yellow goods and in manufacturing plant.
Can I finance a used excavator or other used machine?
Yes. Used yellow goods and plant are financed routinely, from dealers, private sellers and auctions. Lenders look at the machine’s age, hours and condition, and most allow it to be 15 to 20 years old at the end of the term for well-maintained equipment. Private and auction purchases need a PPSR check and usually an inspection. Machines with very high hours or heavy modification may attract a shorter term or a deposit.
How long can machinery be financed over?
One to seven years. Yellow goods and heavy plant are commonly financed over five years, sometimes seven for new machines with long working lives. Production machinery is often matched to the contract or the expected technology cycle. A term that lines up with the work the machine is winning keeps the repayment covered by the income it generates.
Can I refinance machinery I already own to release cash?
Yes. Unencumbered machinery can be refinanced through a sale-and-leaseback or a loan secured on the equipment, releasing a proportion of its value as working capital while you keep using it. Lenders value the machine and lend against it, typically 50 to 80 per cent of value depending on age and type. It is a useful way to fund growth without selling the gear that earns the income.
Can I finance an imported CNC machine before it lands?
Yes. Many CNC machines are built to order overseas and need a deposit at order and the balance before shipping. Lenders can fund the supplier’s progress payments and convert the whole amount to a chattel mortgage when the machine is installed and commissioned, or a trade finance facility covers the purchase until delivery. Tell your broker the payment schedule early so the structure is in place before the deposit is due.
Your business. Your decision.
See your options.
Know the costs.
Decide with confidence.
One broker to explain it. Clear numbers before you proceed.
No obligation to proceed.