
Industry guide
Finance for manufacturing, shaped around how you get paid.
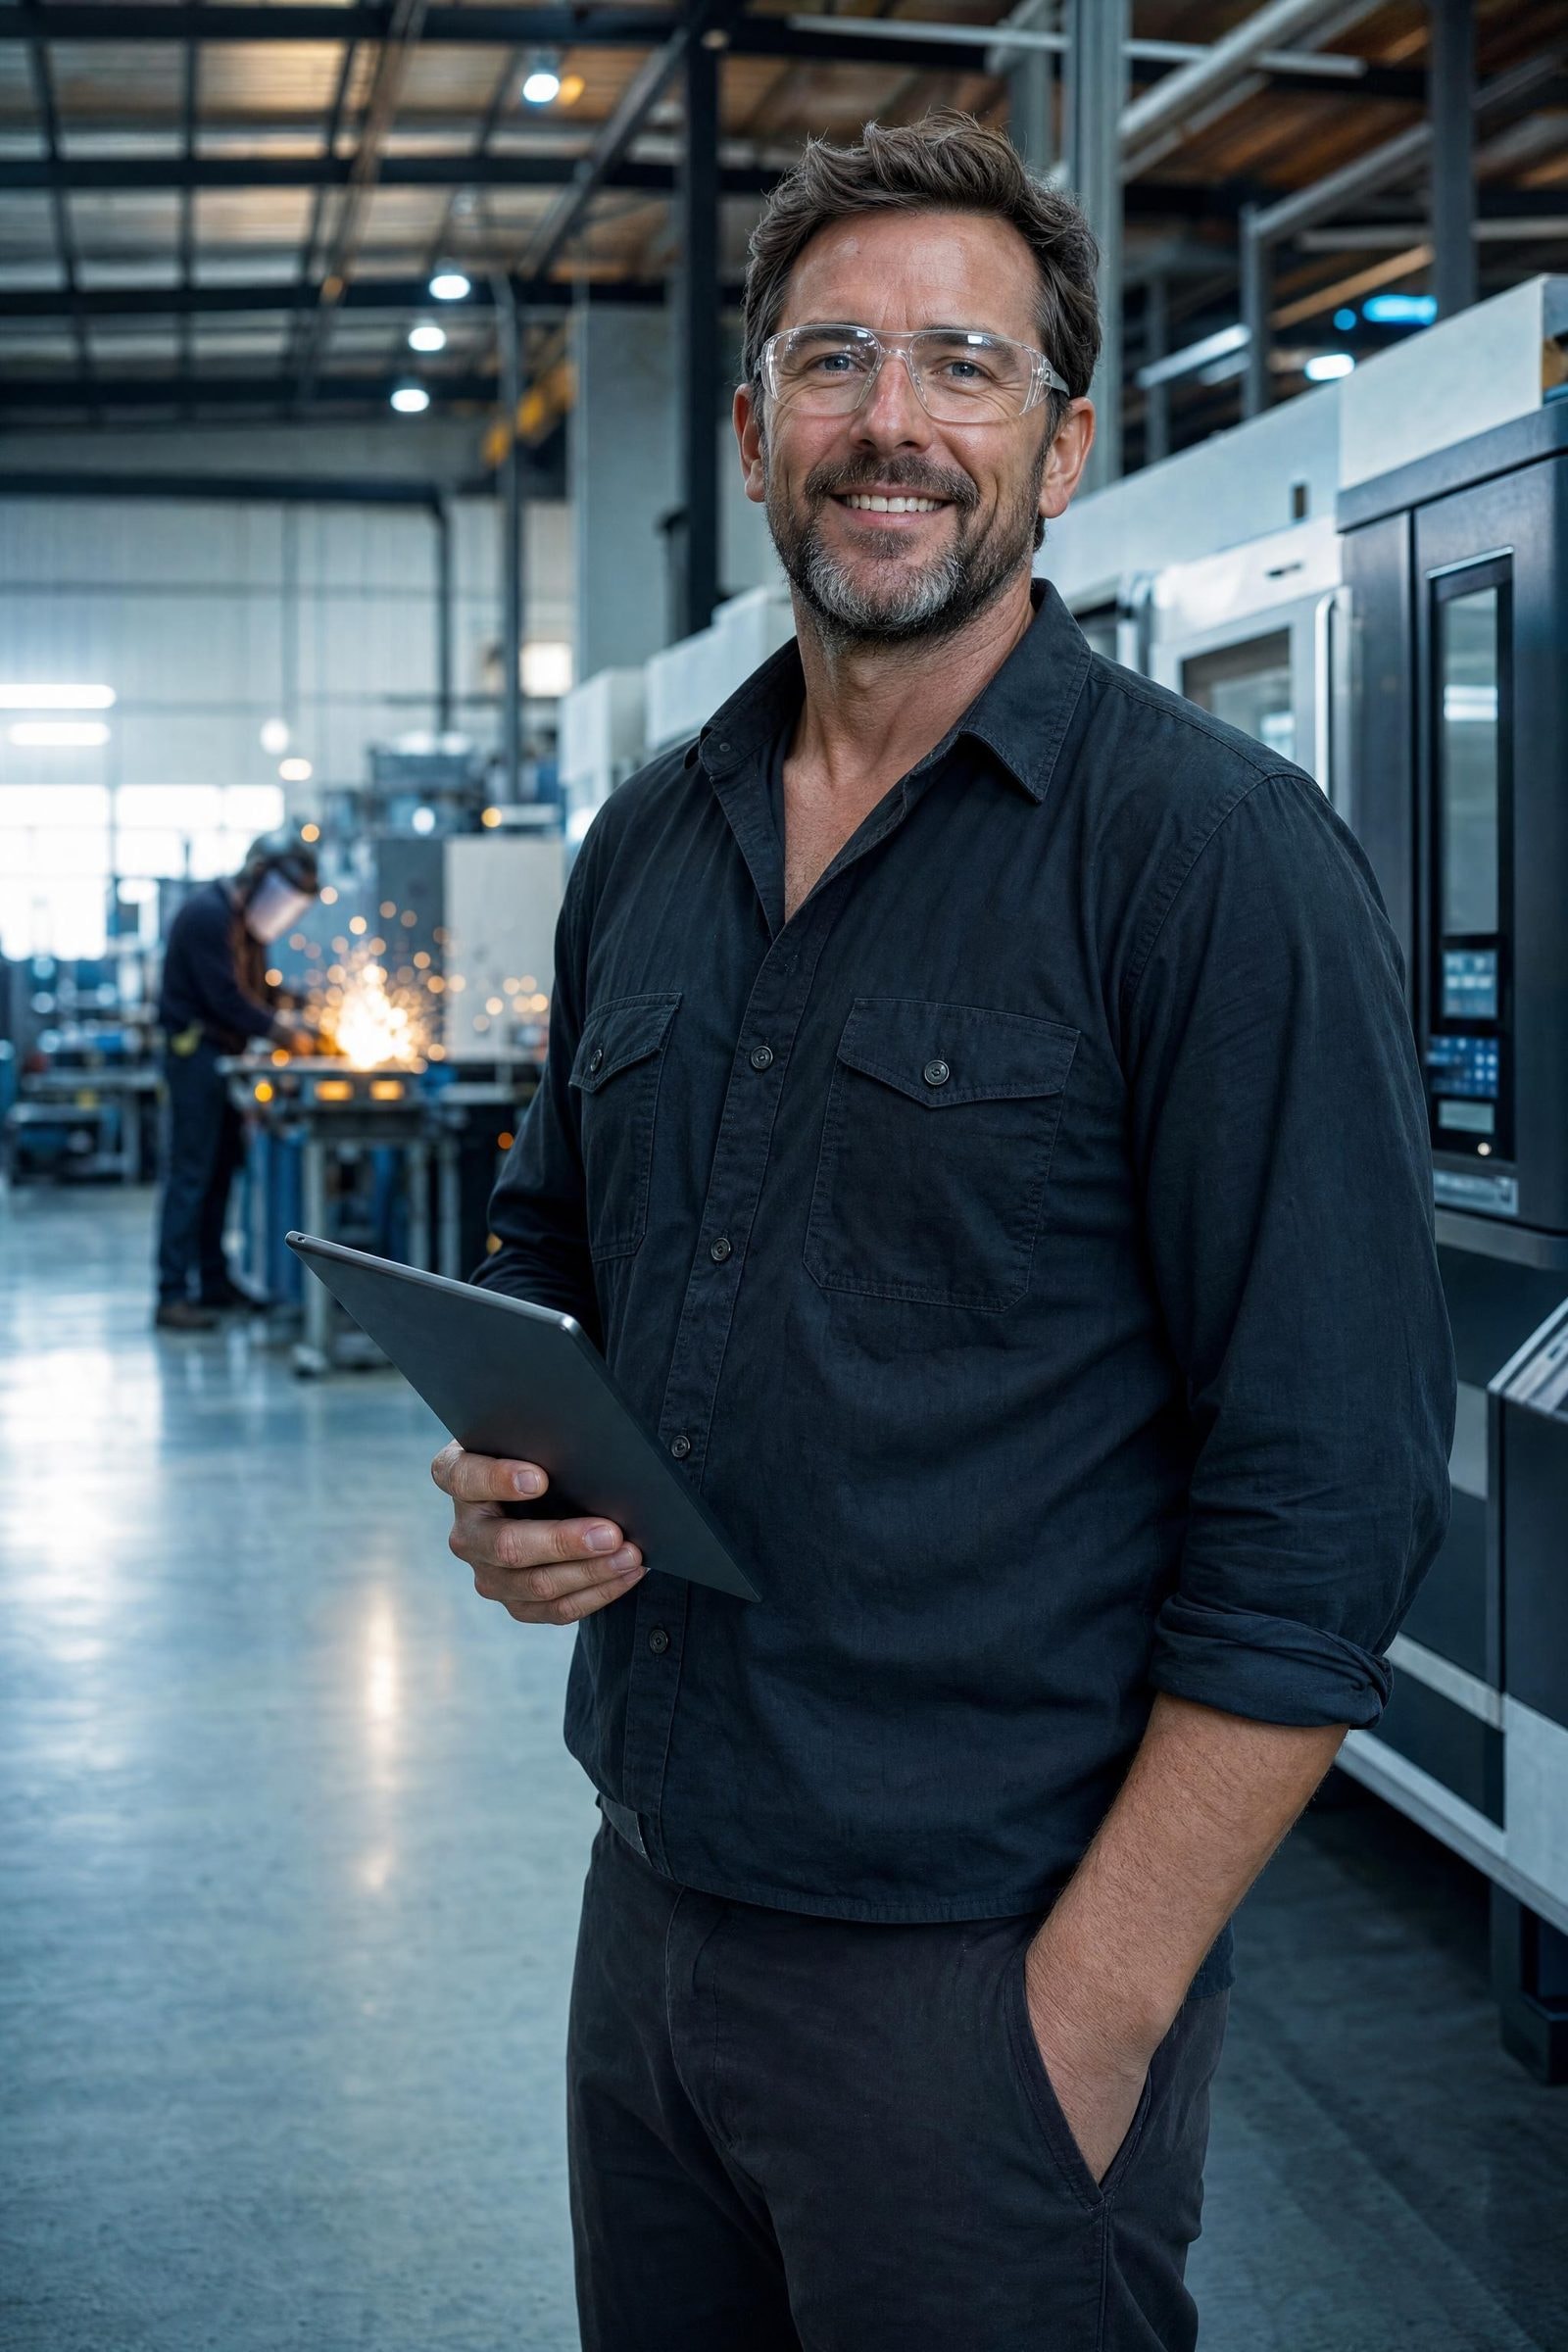
Manufacturers buy materials, convert them, then wait to be paid — often three separate cash-flow events across a couple of months. Finance covers both the machines and the gap in between.
 340 client reviews



One broker from your first call through to funding.
See which options fit your business.
Tell us what you need. A Lyft Money broker who knows manufacturing compares 48+ lenders and explains the rate, fees and repayments before you decide.
Access to 33+ manufacturing lenders
Lenders on our panel that fund manufacturing.
































At a glance
Manufacturing: the numbers that matter.
- Typical amounts
- $20,000 – $3,000,000
- Typical speed
- 24–72 hours for low-doc, up to a week for full-doc or private sales
- Indicative rates
- 7.2% – 16.5% p.a.
- Finance options
- 6 structures compared
- Lenders active here
- 4+ on our panel
- Assets we fund
- CNC machine, Laser cutter, Packaging machinery and more
In plain English
Finance for manufacturing: how it works.
Manufacturing finance is capital equipment lending combined with working capital for raw materials, covering CNC machines, presses and packaging lines as well as the gap between buying stock and being paid for finished goods.
The working capital cycle in manufacturing is long by nature. Steel, resin or componentry is purchased and paid for, sits as raw material, moves through production as work in progress, then becomes finished goods that are invoiced on 30 to 60-day terms. A business growing 30% a year needs 30% more cash tied up in that cycle simply to stand still. This is why profitable manufacturers routinely run out of money during growth, and why trade finance and invoice facilities matter as much as machine finance.
On the capital side, Australian manufacturing has moved toward automation: CNC machining centres, laser cutters, robotic welders and automated packaging lines. These are expensive, long-lived, and often imported, which brings currency, deposit and shipping-lead-time complications that general lenders handle badly. Lenders on our panel who specialise in manufacturing plant will fund progress payments to an overseas supplier and settle on commissioning rather than on the bill of lading, which can be the difference between a deal working and not.
The cash-flow pattern we plan around
Cash out for raw materials, then weeks of work in progress, then 30–60 day terms on finished goods — a cycle that lengthens as the business grows.
What manufacturing typically fund
- CNC machines, lasers and press equipment
- Packaging and materials handling lines
- Raw materials and imported componentry
- Forklifts and factory logistics
- Factory fit-out, power upgrades and compliance works
Documents lenders usually ask for
- ABN, GST registration and two years of financials
- Supplier quote or proforma invoice for the machine
- Debtor ledger and aged receivables report



A clear next step
How to get finance for manufacturing.
Our AI helps check lender fit across 48+ lenders. Your broker reviews the options and explains what they mean for you.
- 01
Machine and job details
Make, model, year, hours, attachments and the contract or work the machine will service.
- 02
Structure to the work
Your broker sets term, deposit and balloon against the machine’s life and the revenue it will generate.
- 03
Inspection and settlement
PPSR search, inspection where required, then the financier pays the seller directly.
The lender makes the final credit decision. Available options depend on your business and the lender’s assessment.
Before you make a decision
Estimate machinery finance repayments.
Know what lands and what leaves. Adjust the amount, rate and term to see the repayment and total cost.
- Number of repayments
- 48
- Total interest (est.)
- $16,651
- Total repaid (est.)
- $91,651
This calculator is a guide only. It uses simplified assumptions, excludes fees and charges unless stated, and is not an offer or quote. Actual repayments are confirmed by the lender in its loan contract.
From Lyft Money clients
Clear advice.
People who stay in touch.
Rated 5.0 from 340 Google reviews across the types of finance we arrange. Read them on Google.
“keeping us informed every step of the way”
“He explained all the financing options clearly”
“helped out my business”
Finance options for manufacturing
Machinery finance
A CNC machining centre or fibre laser is a five-to-ten-year asset and should be financed like one. Machinery finance funds the purchase against the machine itself, and specialist lenders will handle the awkward parts of an imported capital purchase: a deposit to the manufacturer, a progress payment before shipping, and final settlement once the machine is installed and commissioned in your factory.
Chattel mortgage
For a GST-registered manufacturer a chattel mortgage over a press, router or packaging line means ownership from settlement and a GST claim on the full purchase price in the next BAS. On a $400,000 machine that is a meaningful cash injection at the exact moment you have just committed capital.
Trade finance
Trade finance funds the gap between paying an overseas supplier and being paid by your customer. For a manufacturer importing steel, resin, electronics or components, a facility can settle the supplier at shipment and give you 90 to 150 days to convert and sell.
Invoice finance
Once goods are shipped and invoiced, invoice finance converts that receivable to cash immediately instead of in 45 days. For manufacturers this is the natural companion to trade finance: one funds the input, the other releases the output.
Business line of credit
A line of credit handles the smaller irregularities a manufacturer faces — a tooling run, a maintenance shutdown, a bulk material buy at a good price. Draw it, repay it, leave it available.
Sale and leaseback
Manufacturers often hold significant equity in machines bought outright in better years. A sale and leaseback converts that equity into working capital while the machines keep running — useful when a large order requires materials you cannot fund from the current balance.
Assets we finance for manufacturing
Lenders active in this space
Metro Finance, Moneytech, ScotPac, FlexiCommercial — among others on our panel of 48+. Your broker checks fit before anything is submitted.
Key terms
Manufacturing equipment finance
Manufacturing equipment finance is secured lending for production machinery such as CNC machining centres, laser cutters and packaging lines, often structured to fund supplier progress payments and to commence repayments on commissioning.
Working capital cycle
The working capital cycle is the time between paying for raw materials and receiving payment for the finished goods made from them, during which the business funds the value of that inventory itself.
Does a supply contract help a manufacturing finance application?
Yes. A contract or purchase orders from a major customer for the product the machine will make are strong evidence of earnings and often move an application from a deposit to no deposit, or from full financials to a lighter assessment. Include them with the machine quote.
How do manufacturers finance machinery that is built to order overseas?
Progress payments to the manufacturer are funded through a trade finance facility or by the equipment lender, and the whole amount converts to a chattel mortgage when the machine is installed and commissioned. Tell your broker the payment schedule early so the structure is in place before the deposit is due.
How do manufacturers fund raw materials and work in progress?
Trade finance pays suppliers for raw materials with 90 to 180 days to repay, invoice finance advances against finished goods invoices on 30 to 60 day terms, and a line of credit fills the gaps. Together they fund the whole cycle from materials to payment, and the facilities grow with turnover.
Can I release capital from machinery I already own?
Yes. A sale and leaseback or refinance secured on unencumbered CNC machines, presses, lasers and lines can release 60 to 80 per cent of their valuation for working capital or expansion, with the machines staying on your floor. Lenders like recognised brands with strong secondary markets.
How long can I finance equipment for?
Terms usually run from 12 to 84 months. The ceiling is generally set by the expected working life of the asset: heavy earthmoving and trucks often stretch to five or seven years, while IT hardware and point-of-sale systems are commonly kept to two or three. Lenders also look at the age of the asset at the end of the term, so a ten-year-old machine will attract a shorter term than a new one. Longer terms lower repayments and raise total interest.
What machinery can be financed?
Earthmoving and civil plant such as excavators, loaders, dozers, graders and rollers; manufacturing plant such as CNC mills and lathes, presses, laser cutters and production lines; cranes, forklifts and telehandlers; concrete, asphalt and crushing equipment; woodworking, printing and packaging machinery; and agricultural machinery. New and used machines are financed, with lenders that specialise in yellow goods and in manufacturing plant.
Can I finance a used excavator or other used machine?
Yes. Used yellow goods and plant are financed routinely, from dealers, private sellers and auctions. Lenders look at the machine’s age, hours and condition, and most allow it to be 15 to 20 years old at the end of the term for well-maintained equipment. Private and auction purchases need a PPSR check and usually an inspection. Machines with very high hours or heavy modification may attract a shorter term or a deposit.
Can attachments and delivery be included in machinery finance?
Yes. Buckets, rippers, tilt hitches, augers, GPS machine-control systems, installation, commissioning and delivery can all be included in the amount financed when they are on the supplier’s invoice. Bundling them keeps the whole cost of putting the machine to work on one repayment rather than draining cash for the extras.
Should I set a balloon on machinery finance?
A balloon of 20 to 40 per cent is common on machinery with strong resale value, such as excavators and loaders, because it lowers the monthly repayment and the machine can be sold or traded to clear the balloon at the end. Production machinery that will stay in the factory for its full life usually suits a low or zero balloon. Your broker sets the balloon against the machine’s expected value at the end of the term.
How long can machinery be financed over?
One to seven years. Yellow goods and heavy plant are commonly financed over five years, sometimes seven for new machines with long working lives. Production machinery is often matched to the contract or the expected technology cycle. A term that lines up with the work the machine is winning keeps the repayment covered by the income it generates.
Your business. Your decision.
See your options.
Know the costs.
Decide with confidence.
One broker to explain it. Clear numbers before you proceed.
No obligation to proceed.