
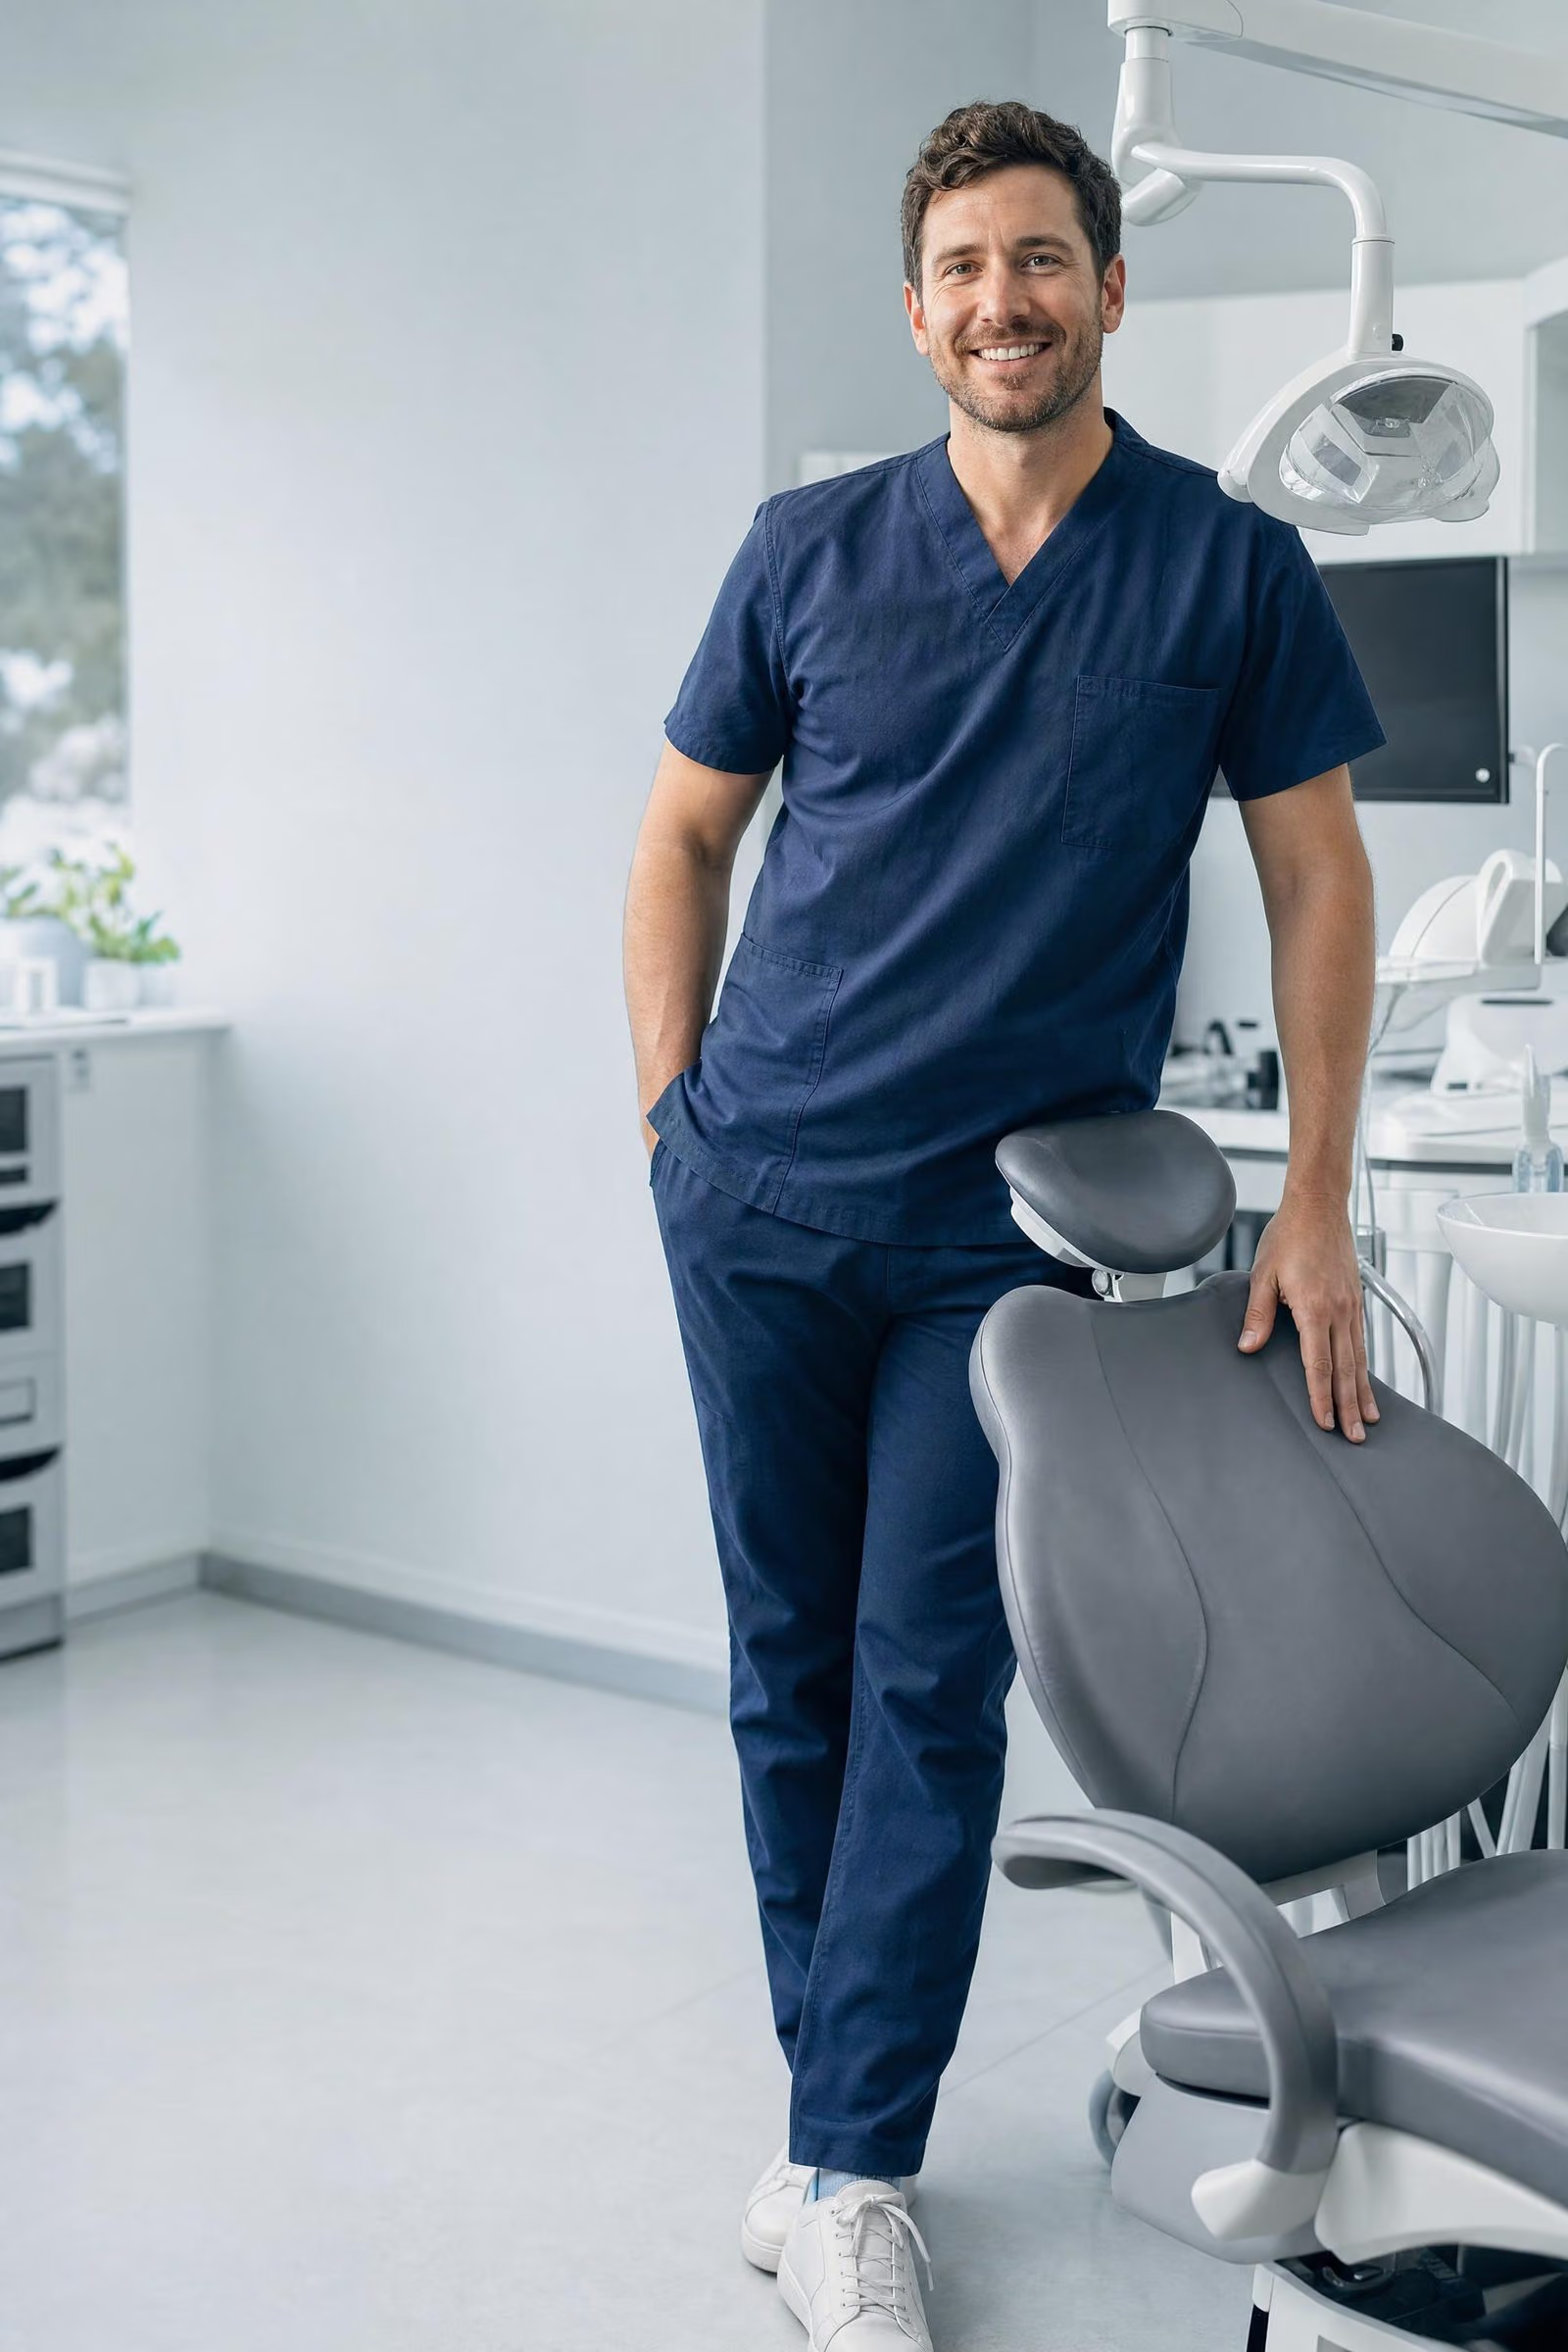
Medical and clinical equipment
Dental chair finance from 48+ Australian lenders.
A chair is rarely bought alone. We look at the whole surgery — chair, compressor, suction, imaging and fit-out — and fund it in a way that suits a practice ramping up.
 340 client reviews



One broker from your first call through to funding.
See which dental chair finance options fit your business.
Tell us what you are buying. A Lyft Money broker compares 48+ lenders and explains the rate, balloon, fees and total cost before you decide.
Access to 31+ dental chair finance lenders
Lenders on our panel that fund dental chair finance.































At a glance
Dental chair finance: the numbers that matter.
- Typical price
- $25,000 – $80,000
- Terms
- Up to 84 months
- Indicative rates
- 6.6% – 13.5% p.a.
- Typical speed
- 24–72 hours for low-doc within practice limits
- Usual structure
- Medical equipment finance
- Useful life
- About 15 years
In plain English
What is dental chair finance?
Dental chair finance is funding for a dental treatment unit including the chair, delivery system, light and often the operator stool, secured against the equipment. Australian dentists commonly finance chairs as part of a wider surgery fit-out, and lenders in this space are used to funding practices with limited trading history.
A dental chair is the centre of the surgery, but it is only one component of a working operatory. Around it sit the compressor, suction plant, autoclave, cabinetry, x-ray and increasingly an intraoral scanner. Buying and financing these piecemeal is common and usually more expensive than treating the surgery as one project with one funding facility. Planning the full operatory upfront also avoids the plant capacity problems that appear when a second chair is added later.
Lenders that specialise in medical and dental equipment take a different view of risk to general business lenders. A qualified dentist opening a first practice can often be funded on the strength of the profession and the business plan rather than on years of trading figures. Some will also structure lower repayments for the first six to twelve months while the patient base builds. Your broker will identify which panel lenders offer that.
How lenders assess dental chair finance
Medical and dental lenders treat qualified practitioners as low risk and will often fund equipment for a new practice with little or no trading history, sometimes without property security. Chairs, compressors, suction plant, autoclaves and imaging can be funded on one facility, and practice fit-out costs are frequently included. Repayment holidays or reduced initial repayments while a practice builds its patient base are available from some lenders. Terms of five to seven years suit equipment with a long service life.
New or used
New chairs are the norm because infection control, warranty and ergonomics matter; refurbished units from major brands are financeable and common in second surgeries.
Before you buy
- Decide on delivery style — over-the-patient, cart or rear delivery — based on how you and your assistant actually work, since it is hard to change later.
- Check the compressor and suction plant capacity against the number of chairs you plan to run, including future expansion.
- Confirm local service support and parts availability; a chair out of action stops the surgery entirely.
Commonly financed
- A-dec 500 and A-dec 300
- Planmeca Compact i5
- Sirona Intego and Teneo
- KaVo Estetica E70
- Belmont Clesta



A clear next step
How to finance a dental chair.
Our AI helps check lender fit across 48+ lenders. Your broker reviews the options and explains what they mean for you.
- 01
Quote and timeline
Supplier quote including installation and training, plus the expected delivery and commissioning dates.
- 02
Choose ownership or rental
Your broker compares chattel mortgage against operating lease based on the equipment’s replacement cycle.
- 03
Settle with a deferred start
The financier pays the supplier; repayments can be timed to begin once the equipment is billing.
- AHPRA registration and practice ABN
- Supplier quote with installation and training itemised
- Practice financials or bank statements depending on the amount
The lender makes the final credit decision. Available options depend on your business and the lender’s assessment.
Before you make a decision
Estimate your dental chair repayments.
Adjust the price, rate, term and balloon to see the repayment and the total cost over the term.
- Number of repayments
- 60
- Balloon at end of term
- $10,600
- Total interest (est.)
- $14,124
- Total repaid (est.)
- $67,124
This calculator is a guide only. It uses simplified assumptions, excludes fees and charges unless stated, and is not an offer or quote. Actual repayments are confirmed by the lender in its loan contract.
From Lyft Money clients
Clear advice.
People who stay in touch.
Rated 5.0 from 340 Google reviews across the types of finance we arrange. Read them on Google.
“keeping us informed every step of the way”
“He explained all the financing options clearly”
“helped out my business”
Ways to finance a dental chair
Key terms
What is dental chair finance?
Dental chair finance is a loan or lease used to buy a dental treatment unit, with the equipment as security. Terms commonly run 60 to 84 months and the chair is often funded alongside compressors, suction, autoclaves and surgery fit-out on one facility.
Can a new dental practice finance equipment?
Often yes. Specialist medical and dental lenders assess qualified practitioners on their profession, registration and business plan as well as trading history, so a start-up practice can frequently be funded. Some lenders also offer reduced initial repayments while the practice builds patient numbers.
How long should I finance dental chairs for?
Five years is typical, with up to seven available on new chairs from major brands given their 15-year working lives. A longer term keeps the monthly repayment low against the chair’s earnings; a balloon of 10 to 20 per cent suits practices that update rooms regularly.
Can a whole dental surgery fit-out be financed with the chairs?
Yes. Chairs, delivery units, cabinetry, sterilisation, imaging, compressors and suction can be financed together under one contract or a master facility, and installation and fit-out costs can usually be included when quoted by the supplier. Lenders like dental practices, so terms of five to seven years and no deposit are common for established practitioners.
Can a newly registered dentist finance equipment?
Yes. Several lenders offer professional packages for dentists and other registered health practitioners, funding equipment and even practice purchases with little or no trading history because the profession’s income is reliable. AHPRA registration, a practice plan and a clean personal credit file are the key documents.
Can I finance used or refurbished dental equipment?
Yes. Refurbished chairs from dealers with warranty are accepted by most lenders, and used equipment from a practice sale can be financed with an inspection and evidence of service history. Terms are usually shorter than new. Ask your broker before committing so the lender is matched to the equipment.
What medical and clinical equipment can be financed?
Almost any clinical asset: ultrasound and imaging, dental chairs and CAD/CAM systems, surgical and sterilisation equipment, veterinary diagnostic and surgical gear, physiotherapy and rehabilitation machines, optometry and audiology instruments, cosmetic lasers, practice management software and IT, and the clinic fit-out itself. New equipment from suppliers is the simplest; refurbished equipment from recognised dealers is financed by many lenders too.
What does a practice-friendly finance structure look like?
Several lenders offer structures built for practices: deferred first payments so the equipment starts earning before repayments begin, terms matched to the equipment’s clinical life, seasonal or stepped repayments for practices that are still building patient numbers, and pre-approved equipment limits for established practitioners. Medical, dental and veterinary professionals are treated as low-risk borrowers, so pricing and documentation are usually favourable.
Can I get low-doc finance as a doctor, dentist or vet?
Yes. Registered health practitioners are often eligible for low-doc or no-doc equipment finance up to practice limits, commonly $150,000 to $500,000 depending on the lender and profession, based on registration, time in practice and credit history rather than financials. Larger amounts and new practices provide recent financials or a business plan. Your broker knows which lenders run professional programs for each discipline.
Should I lease or buy medical equipment?
Buy with a chattel mortgage when the equipment will serve the practice for years and you want to own and depreciate it, such as dental chairs or sterilisers. Lease when the technology moves quickly and you expect to upgrade, such as imaging, lasers or IT, because a lease with a residual makes the upgrade cycle simpler. Your accountant advises on the tax outcome for your practice entity, and your broker structures either option.
Can I finance equipment for a new practice?
Yes. Lenders regularly fund new practices for registered practitioners with a track record as an employee or associate, because the profession itself gives them confidence. A business plan, the lease on the premises and evidence of qualifications are the main requirements, and the fit-out, equipment and working capital can be funded together as a package so the practice opens fully equipped.
Is medical equipment finance tax deductible?
Generally, yes. For a chattel mortgage the interest and the depreciation of the equipment are deductible, and GST on the purchase can usually be claimed on the next BAS. For a lease the rental payments are deductible and GST is claimed on each payment. Instant asset write-off rules may apply in some years. Confirm the treatment with your accountant, since practices are often run through companies or trusts with their own considerations.
Your business. Your decision.
See your options.
Know the costs.
Decide with confidence.
One broker to explain it. Clear numbers before you proceed.
No obligation to proceed.