
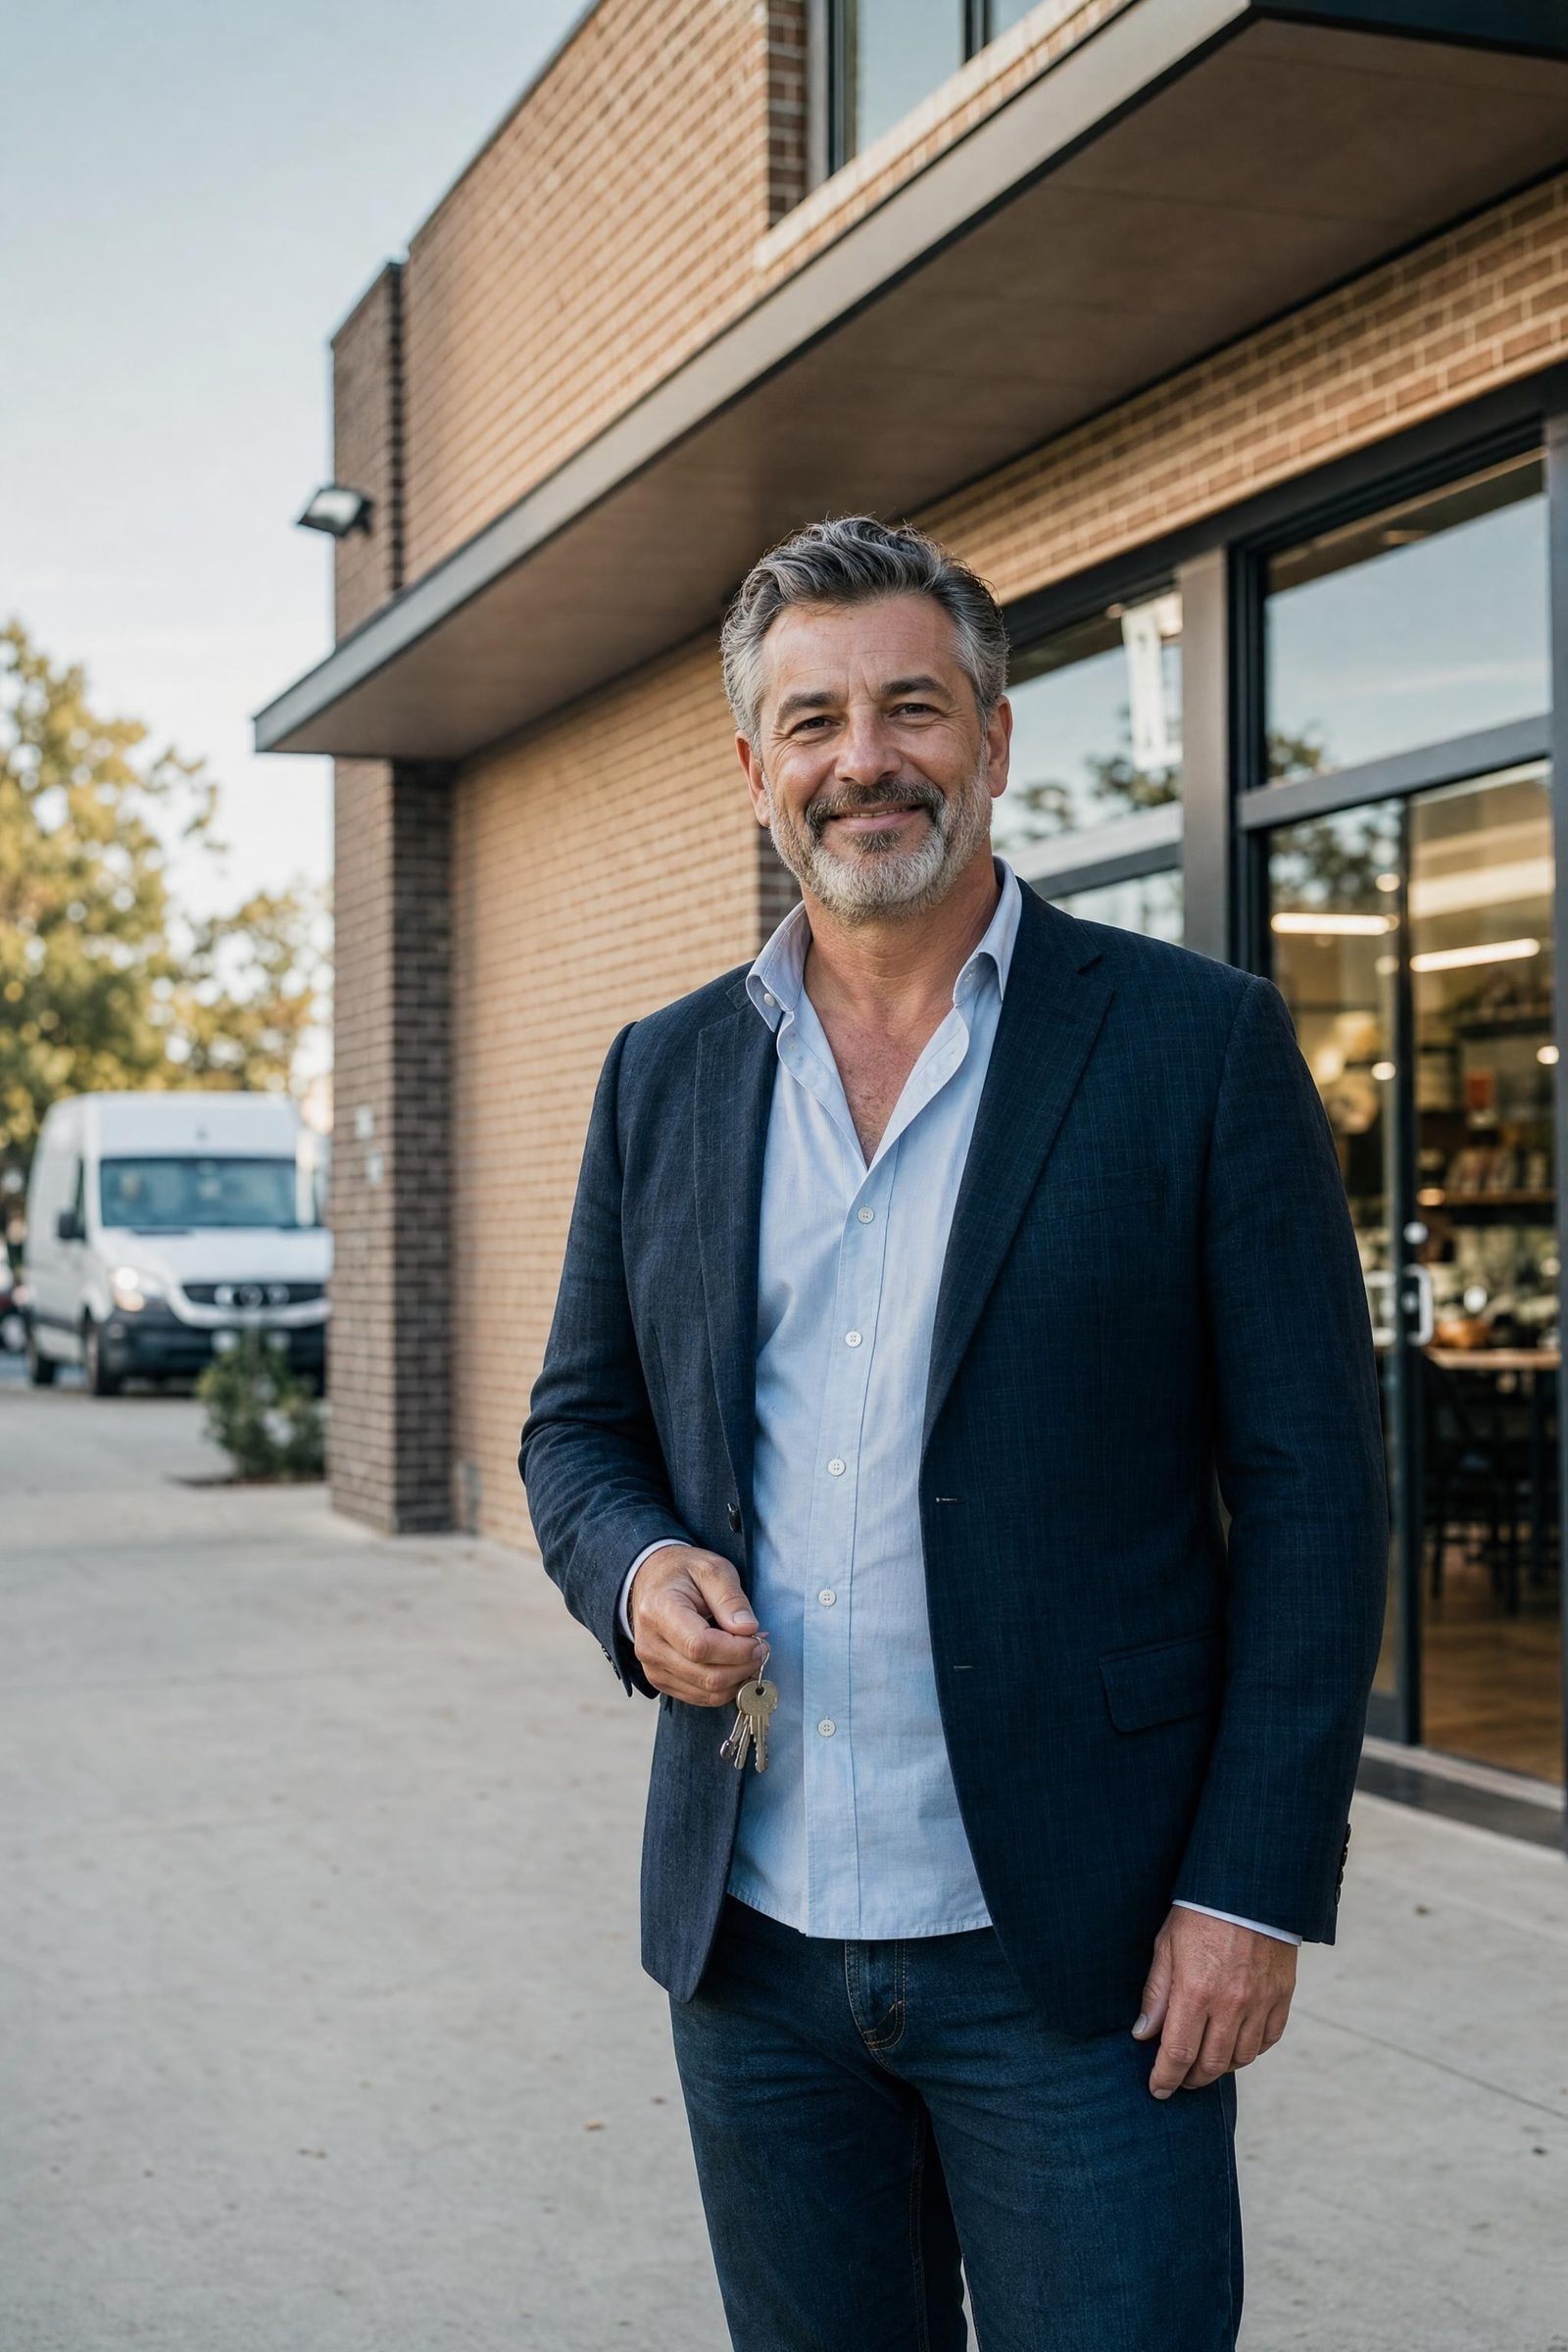
Business situation
Finance for property owners, shaped around how you get paid.
Owning property changes what a business can borrow and what it pays. Sometimes the property is used as security; often it simply signals stability to the lender.
 340 client reviews



One broker from your first call through to funding.
See which options fit your situation.
Tell us what you need. A Lyft Money broker who knows property owners compares 48+ lenders and explains the rate, fees and repayments before you decide.
Access to 44+ property owners lenders
Lenders on our panel that fund property owners.




















At a glance
Property owners: the numbers that matter.
- Typical amounts
- $50,000 – $5,000,000
- Typical speed
- 2–6 weeks including valuation
- Indicative rates
- 6.8% – 13.5% p.a.
- Finance options
- 6 structures compared
- Lenders active here
- 1+ on our panel
In plain English
Finance for property owners: how it works.
Property owner business finance is lending where the applicant or director owns residential or commercial real estate, which widens the lender panel and lowers pricing even when the property is not offered as security.
Australian business lenders draw a hard line between property-owning and non-property-owning applicants, and the difference in outcome is larger than most business owners expect. Many unsecured lenders price property owners a several points cheaper and lend materially higher amounts, even where no mortgage or caveat is taken. The reasoning is straightforward: a director with equity in real estate has more to lose and more capacity to resolve a problem, and statistically defaults less.
Where the property is actually offered as security, an entirely different tier of lending opens up: longer terms, lower rates, larger amounts, and lenders who would otherwise not participate. That comes with a real cost. Secured business lending puts your home or investment property at risk if the business fails, and the decision deserves proper thought and often independent advice. There is also a middle path worth knowing about, where a lender takes a second mortgage or caveat rather than a first, giving some of the pricing benefit without refinancing your existing home loan.
The cash-flow pattern we plan around
Business cash flow assessed alongside personal property equity, which lenders treat as a buffer even where no security is taken over the property.
What property owners typically fund
- Larger facility limits than an unsecured position allows
- Lower-cost funding for expansion or acquisition
- Consolidating expensive short-term business debt
- Buying commercial premises for the business
Documents lenders usually ask for
- ABN and business financials or bank statements
- Rates notice and current mortgage statements for the property
- Personal asset and liability statement



A clear next step
How to get finance for property owners.
Our AI helps check lender fit across 48+ lenders. Your broker reviews the options and explains what they mean for you.
- 01
Identify the security
What you can pledge, its estimated value and what is already owing against it.
- 02
Test servicing and LVR
Your broker checks lender appetite for the security type and confirms the amount that works at their LVR limits.
- 03
Valuation and settlement
The lender orders a valuation, issues formal approval, and your solicitor handles settlement.
The lender makes the final credit decision. Available options depend on your business and the lender’s assessment.
Before you make a decision
Estimate secured business loan repayments.
Know what lands and what leaves. Adjust the amount, rate and term to see the repayment and total cost.
- Number of repayments
- 48
- Total interest (est.)
- $14,415
- Total repaid (est.)
- $89,415
This calculator is a guide only. It uses simplified assumptions, excludes fees and charges unless stated, and is not an offer or quote. Actual repayments are confirmed by the lender in its loan contract.
From Lyft Money clients
Clear advice.
People who stay in touch.
Rated 5.0 from 340 Google reviews across the types of finance we arrange. Read them on Google.
“keeping us informed every step of the way”
“He explained all the financing options clearly”
“helped out my business”
Finance options for property owners
Secured business loan
Using property as security gives access to the cheapest business lending available, with longer terms and larger amounts than any unsecured facility. For a business with a clear, productive use for the money — buying a competitor, funding an expansion, replacing high-cost debt — the arithmetic is usually compelling.
Commercial property loan
Business owners who already hold residential property are often well positioned to buy the premises their business occupies, using existing equity toward the deposit. Commercial loans generally require 20–30% down, and owner-occupied facilities are assessed on the trading business rather than on market rent.
Business line of credit
A property-secured line of credit sits at the low end of revolving facility pricing and is typically offered with a larger limit than an unsecured equivalent. Draw when cash is needed, repay when it comes in, pay interest only on the drawn balance.
Unsecured business loan
Property owners are worth quoting for unsecured lending even when they have no intention of offering the property as security. Many lenders on our panel apply a lower rate and a higher limit purely on the basis of director property ownership, because the statistics support it.
Business debt consolidation loan
Where a business has accumulated several short-term facilities with daily or weekly repayments, property security allows those to be refinanced onto a single longer-term loan at a fraction of the cost. The improvement in weekly cash flow is often dramatic.
Development finance
Property owners with development experience and equity sometimes move from occupying commercial property to developing it — a small industrial subdivision, a few townhouses, or an extension to an existing site. Development finance is drawn progressively against construction milestones and assessed on feasibility, builder capability, presales and exit strategy rather than on trading cash flow.
Lenders active in this space
Pepper Money — among others on our panel of 48+. Your broker checks fit before anything is submitted.
Key terms
Property-backed business lending
Property-backed business lending is finance secured by residential or commercial real estate owned by the business or its directors, offering longer terms and lower rates than unsecured lending in exchange for putting that property at risk.
Property ownership pricing benefit
The property ownership pricing benefit is the lower rate and higher limit many Australian lenders offer a director who owns real estate, applied even when no security is taken over that property.
Does owning property get me a better business loan rate?
Usually, yes, even when the property is not used as security. Lenders treat a director’s property equity as a buffer, which widens the lender panel, lifts limits and lowers pricing on unsecured loans and equipment finance. Offering the property as security lowers the rate further and extends the term, at the cost of tying the property to the debt.
Should I secure a business loan against my home?
It depends on the amount, the term and your appetite for risk. A secured loan is the cheapest and longest-term business money available, which suits large, long-lived purposes such as buying premises, a business or consolidating debt. For shorter needs, an unsecured facility priced with your property in the background often costs little more and keeps the home separate.
Can I use equity in my home or investment property for the business?
Yes. An equity release or a business loan secured against residential or commercial property can fund expansion, equipment, a deposit on premises or working capital, typically up to 80 per cent of the property’s value less existing loans. Interest on the business-use portion is generally deductible. Your accountant confirms the treatment.
Can I buy my business premises instead of renting?
Yes. A commercial property loan funds an owner-occupied premises at typically 70 to 80 per cent of the value, with the business paying rent to itself or to a self-managed super fund that owns the property. Owning existing property helps with the deposit and pricing. Lyft Financial handles commercial property lending.
What is a secured business loan?
A secured business loan is a term loan backed by an asset the lender can claim if the loan is not repaid, most commonly residential or commercial property, and sometimes equipment, vehicles or a general security agreement over the business. Because the lender’s risk is lower, secured loans offer larger amounts, longer terms and lower rates than unsecured lending. They suit established purposes such as expansion, refinancing, buying premises or consolidating debts, rather than urgent short-term gaps.
What can I use as security for a business loan?
Residential property is the most widely accepted security and attracts the best pricing, followed by commercial property. Some lenders also take unencumbered equipment, vehicles or trucks, term deposits, or a general security agreement over all business assets. The lender values the security and lends a proportion of that value, typically up to 80 per cent for residential property and less for commercial property or equipment. Your broker matches the security you have to lenders that accept it.
How much cheaper is a secured business loan than an unsecured one?
Materially. Secured business loans backed by property in Australia are typically priced in the single digits, while unsecured business loans commonly run from around 10 per cent to well over 20 per cent because the lender carries more risk. Secured loans also run over longer terms, up to 15 years or more, so the repayment is lower again. The trade-off is time and cost to set up: a valuation, legal work and a slower approval, so the saving needs to outweigh those for smaller or short-term amounts.
Can I use my home as security for a business loan?
Yes, and it is the most common form of security for small business borrowing in Australia. The lender takes a mortgage over the home, usually behind your existing home loan as a second mortgage or by refinancing the home loan and adding the business borrowing. The equity available is generally the property value less existing loans, up to a lending limit of around 80 per cent. Using your home puts it at risk if the business cannot repay, so your broker explains the implications and any alternatives before you proceed.
How long does a secured business loan take to approve?
Allow two to six weeks. The lender needs a valuation of the security, which takes one to two weeks for residential property and longer for commercial, then reviews financials and prepares mortgage documents. Non-bank lenders can be faster, sometimes within a week where a recent valuation exists. If the funding is urgent, your broker may arrange a short-term unsecured facility first and refinance it into the secured loan once it settles.
What documents are needed for a secured business loan?
Full-doc secured loans typically need two years of business financials and tax returns, recent BAS, business bank statements, a statement of your assets and liabilities, and details of the security property including any existing mortgage. Low-doc secured loans replace the financials with an accountant’s declaration or bank statements and are priced a little higher. The lender also requires identification for all directors and guarantors and evidence that the business purpose is genuine.
Your business. Your decision.
See your options.
Know the costs.
Decide with confidence.
One broker to explain it. Clear numbers before you proceed.
No obligation to proceed.