
Trailers
Tipper trailer finance from 48+ Australian lenders.
Adding a tipper trailer is often the cheapest way to lift payload without buying another truck. We compare lenders and structure the term around the extra tonnes it carries.
 340 client reviews



One broker from your first call through to funding.
See which tipper trailer finance options fit your business.
Tell us what you are buying. A Lyft Money broker compares 48+ lenders and explains the rate, balloon, fees and total cost before you decide.
Access to 21+ tipper trailer finance lenders
Lenders on our panel that fund tipper trailer finance.





















At a glance
Tipper trailer finance: the numbers that matter.
- Typical price
- $40,000 – $180,000
- Terms
- Up to 84 months
- Indicative rates
- 6.9% – 14.5% p.a.
- Typical speed
- 24–48 hours for low-doc up to $150k; longer for full-doc
- Usual structure
- Chattel mortgage
- Useful life
- About 20 years
In plain English
What is tipper trailer finance?
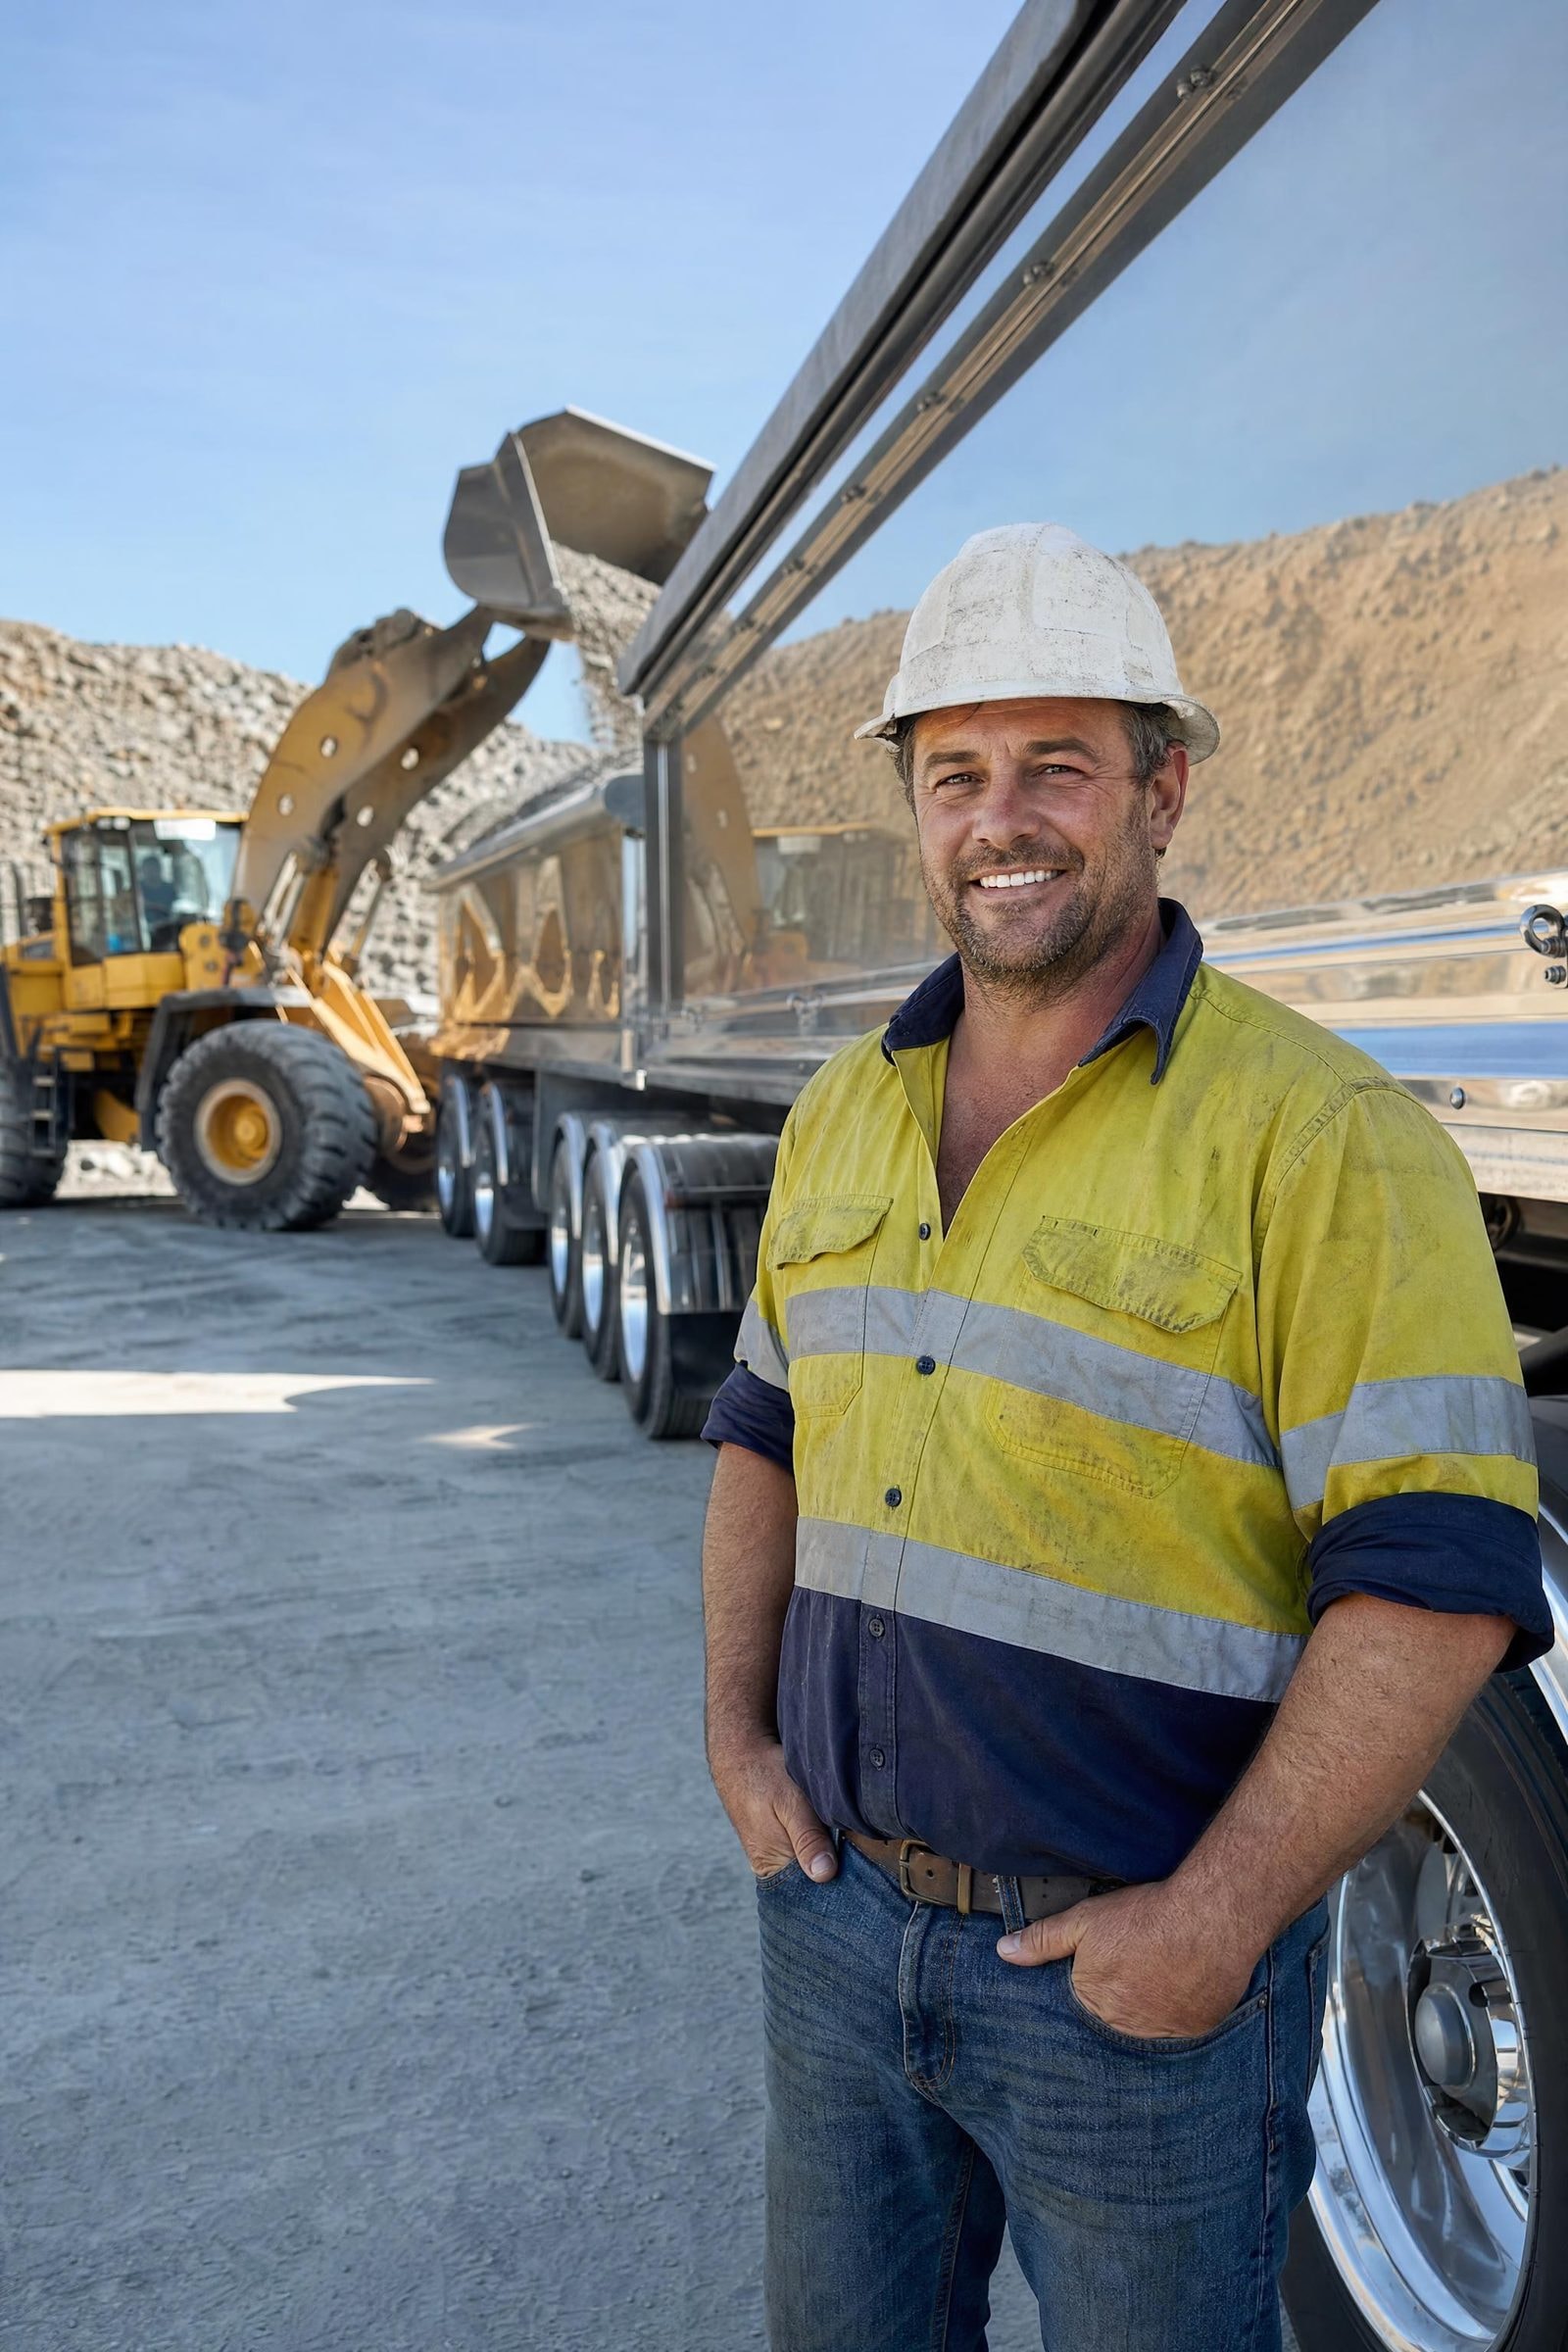
Tipper trailer finance is funding for a tipping semi-trailer used to cart bulk material such as quarry product, grain, sand and spoil, secured against the trailer. Tipper trailers are long-life assets in Australia and are commonly bought to increase payload behind an existing prime mover.
Tipper trailers do the bulk cartage that keeps quarries, farms and civil sites moving. In Australia the two main styles are end tippers, which lift the front of the body to discharge at the rear, and side tippers, which roll the body sideways. Side tippers are increasingly preferred in quarry and mining service work because they are more stable and can discharge without lifting high into overhead hazards.
For an operator who already owns a prime mover, adding a trailer is a straightforward way to increase revenue without a second driver or a second truck. The finance is usually modest relative to a truck, terms are long because the asset lasts, and lenders are comfortable with the security. Where you already own trailers outright, they can also support a sale and leaseback if the business needs working capital.
How lenders assess tipper trailer finance
Lenders treat tipper trailers as mainstream trailer security with reliable resale, especially in quarry and grain regions. Valuation looks at body material, hoist condition, chassis integrity and suspension. Aluminium bodies command a premium because they carry more payload. Side tippers narrow the buyer pool slightly but are still well understood. Operators adding a trailer to an existing truck are usually assessed on trading history and the current fleet. Private sales require PPSR clearance and payment direct to the registered owner.
New or used
Used tipper trailers are readily available from cartage fleets; new aluminium bodies are popular where tare weight and payload matter most.
Before you buy
- Weigh the tare before you buy — an aluminium body can carry a tonne or more extra payload on every load compared with steel.
- Test the hoist and check the sub-frame and pivot points, as these carry all the tipping load.
- Decide between end tip and side tip based on where you unload; side tippers are safer under power lines and in windy quarry conditions.
Commonly financed
- Hercules side tipper
- Muscat tipper trailer
- Roadwest end tipper
- Bruce Rock Engineering side tipper
- Howard Porter tipper



A clear next step
How to finance a tipper trailer.
Our AI helps check lender fit across 48+ lenders. Your broker reviews the options and explains what they mean for you.
- 01
Confirm the asset
Dealer or private sale, new or used, price and age of the asset.
- 02
Structure the loan
Term, deposit and balloon matched to cash flow and asset life.
- 03
Settle and collect
Lender pays the supplier directly; you take delivery.
- ID and ABN
- Invoice or quote for the asset
- Bank statements or financials depending on amount
The lender makes the final credit decision. Available options depend on your business and the lender’s assessment.
Before you make a decision
Estimate your tipper trailer repayments.
Adjust the price, rate, term and balloon to see the repayment and the total cost over the term.
- Number of repayments
- 60
- Balloon at end of term
- $22,000
- Total interest (est.)
- $31,138
- Total repaid (est.)
- $141,138
This calculator is a guide only. It uses simplified assumptions, excludes fees and charges unless stated, and is not an offer or quote. Actual repayments are confirmed by the lender in its loan contract.
From Lyft Money clients
Clear advice.
People who stay in touch.
Rated 5.0 from 340 Google reviews across the types of finance we arrange. Read them on Google.
“keeping us informed every step of the way”
“He explained all the financing options clearly”
“helped out my business”
Ways to finance a tipper trailer
Key terms
What is tipper trailer finance?
Tipper trailer finance is a secured loan or lease used to buy a tipping semi-trailer, with the trailer as security. Terms commonly run 48 to 84 months, reflecting the long working life of the asset.
End tipper or side tipper?
An end tipper discharges rearwards by raising the front of the body and suits confined tip sites and hoppers. A side tipper rolls the body sideways, stays more stable, and is preferred where overhead clearance or ground conditions make raising a body risky.
Can I finance a tipper trailer with my prime mover?
Yes. A tipping semi-trailer or a truck-and-dog combination can settle on one contract with the truck, or on separate contracts with terms matched to each asset. Trailers last longer than trucks, so a longer term with a modest balloon on the trailer often gives the best overall repayment.
Are alloy and steel tipper trailers financed the same way?
Yes. Lenders finance both, and alloy trailers often hold value better because of their payload advantage and resistance to corrosion. Lenders look at brand, build year, suspension, hoist condition and body wear. A recognised Australian builder makes the trailer easier to finance and resell.
Can a new cartage business finance a tipper trailer?
Yes. New ABNs usually need a deposit of 10 to 20 per cent, a clean personal credit file and evidence of work such as a cartage agreement with a quarry or civil contractor. Established operators are often approved low-doc with no deposit. Tipper trailers are strong security because civil and quarry demand is steady.
Can I finance a used tipper trailer?
Yes. Used tippers are financed with a PPSR clearance, a current registration or roadworthy and an inspection for private and auction purchases. Because trailers work for 20 years or more, lenders are relaxed about age and focus on condition and brand. Terms of three to five years are common on used units.
Do I need a deposit for equipment finance?
Often no deposit is required, particularly for established businesses buying standard assets from a dealer. A deposit is more likely where the business is new, the asset is older or specialised, the credit profile is weaker, or the amount is large relative to turnover. Deposits typically range from around 10% to 30% in those cases. Putting money in reduces the amount financed and can improve the terms offered, but it is not always necessary.
What fees are normally charged on equipment finance?
The common ones are an establishment or documentation fee charged at settlement, a monthly account-keeping fee, and a PPSR registration fee for recording the lender's interest in the asset. A brokerage fee may also apply, which we disclose to you in writing before anything is submitted. Some agreements include an early termination or break cost. Fees vary by lender and are typically a modest part of total cost compared with the interest, but they should still be compared.
How large a balloon can I set?
Lenders publish maximum residual or balloon percentages that fall as the term lengthens, because the asset is worth less at the end of a longer term. For a vehicle, a common pattern is up to roughly 50% on a two-year term, reducing to around 20% to 30% on a five-year term. The ATO also sets minimum residual values for finance leases. A larger balloon lowers monthly repayments but increases total interest and leaves a lump sum to deal with at the end.
Is hire purchase still used in Australia?
It is far less common than it once was. Under hire purchase the financier owns the asset and you hire it, with ownership transferring automatically after the final instalment. Since the GST changes that made chattel mortgage more attractive for businesses accounting on a cash basis, most equipment lending is written as a chattel mortgage or lease instead. Some lenders still offer commercial hire purchase, and your accountant can advise whether it suits your circumstances.
What is PPSR registration and why does the lender do it?
The Personal Property Securities Register is the national register of security interests in personal property, including vehicles and equipment. When a lender finances an asset, it registers its interest so the security is publicly recorded and its priority is protected if the asset is sold or the business fails. It also means a buyer searching the register will see the finance. The registration is released once the contract is paid out, and a small registration fee is usually passed on to you.
How does a balloon payment work on a chattel mortgage?
A balloon is a lump sum left to pay at the end of a chattel mortgage, which lowers the regular repayments during the term. For example, a 30 per cent balloon on a $100,000 vehicle leaves $30,000 to pay at the end, so the monthly amount is calculated on $70,000 plus interest on the full balance. Balloons are commonly set between 0 and 40 per cent depending on the asset and term, and at the end you can pay it out, refinance it or sell the asset to clear it. A balloon reduces monthly cost but increases total interest, so your broker shows both figures side by side.
Your business. Your decision.
See your options.
Know the costs.
Decide with confidence.
One broker to explain it. Clear numbers before you proceed.
No obligation to proceed.