
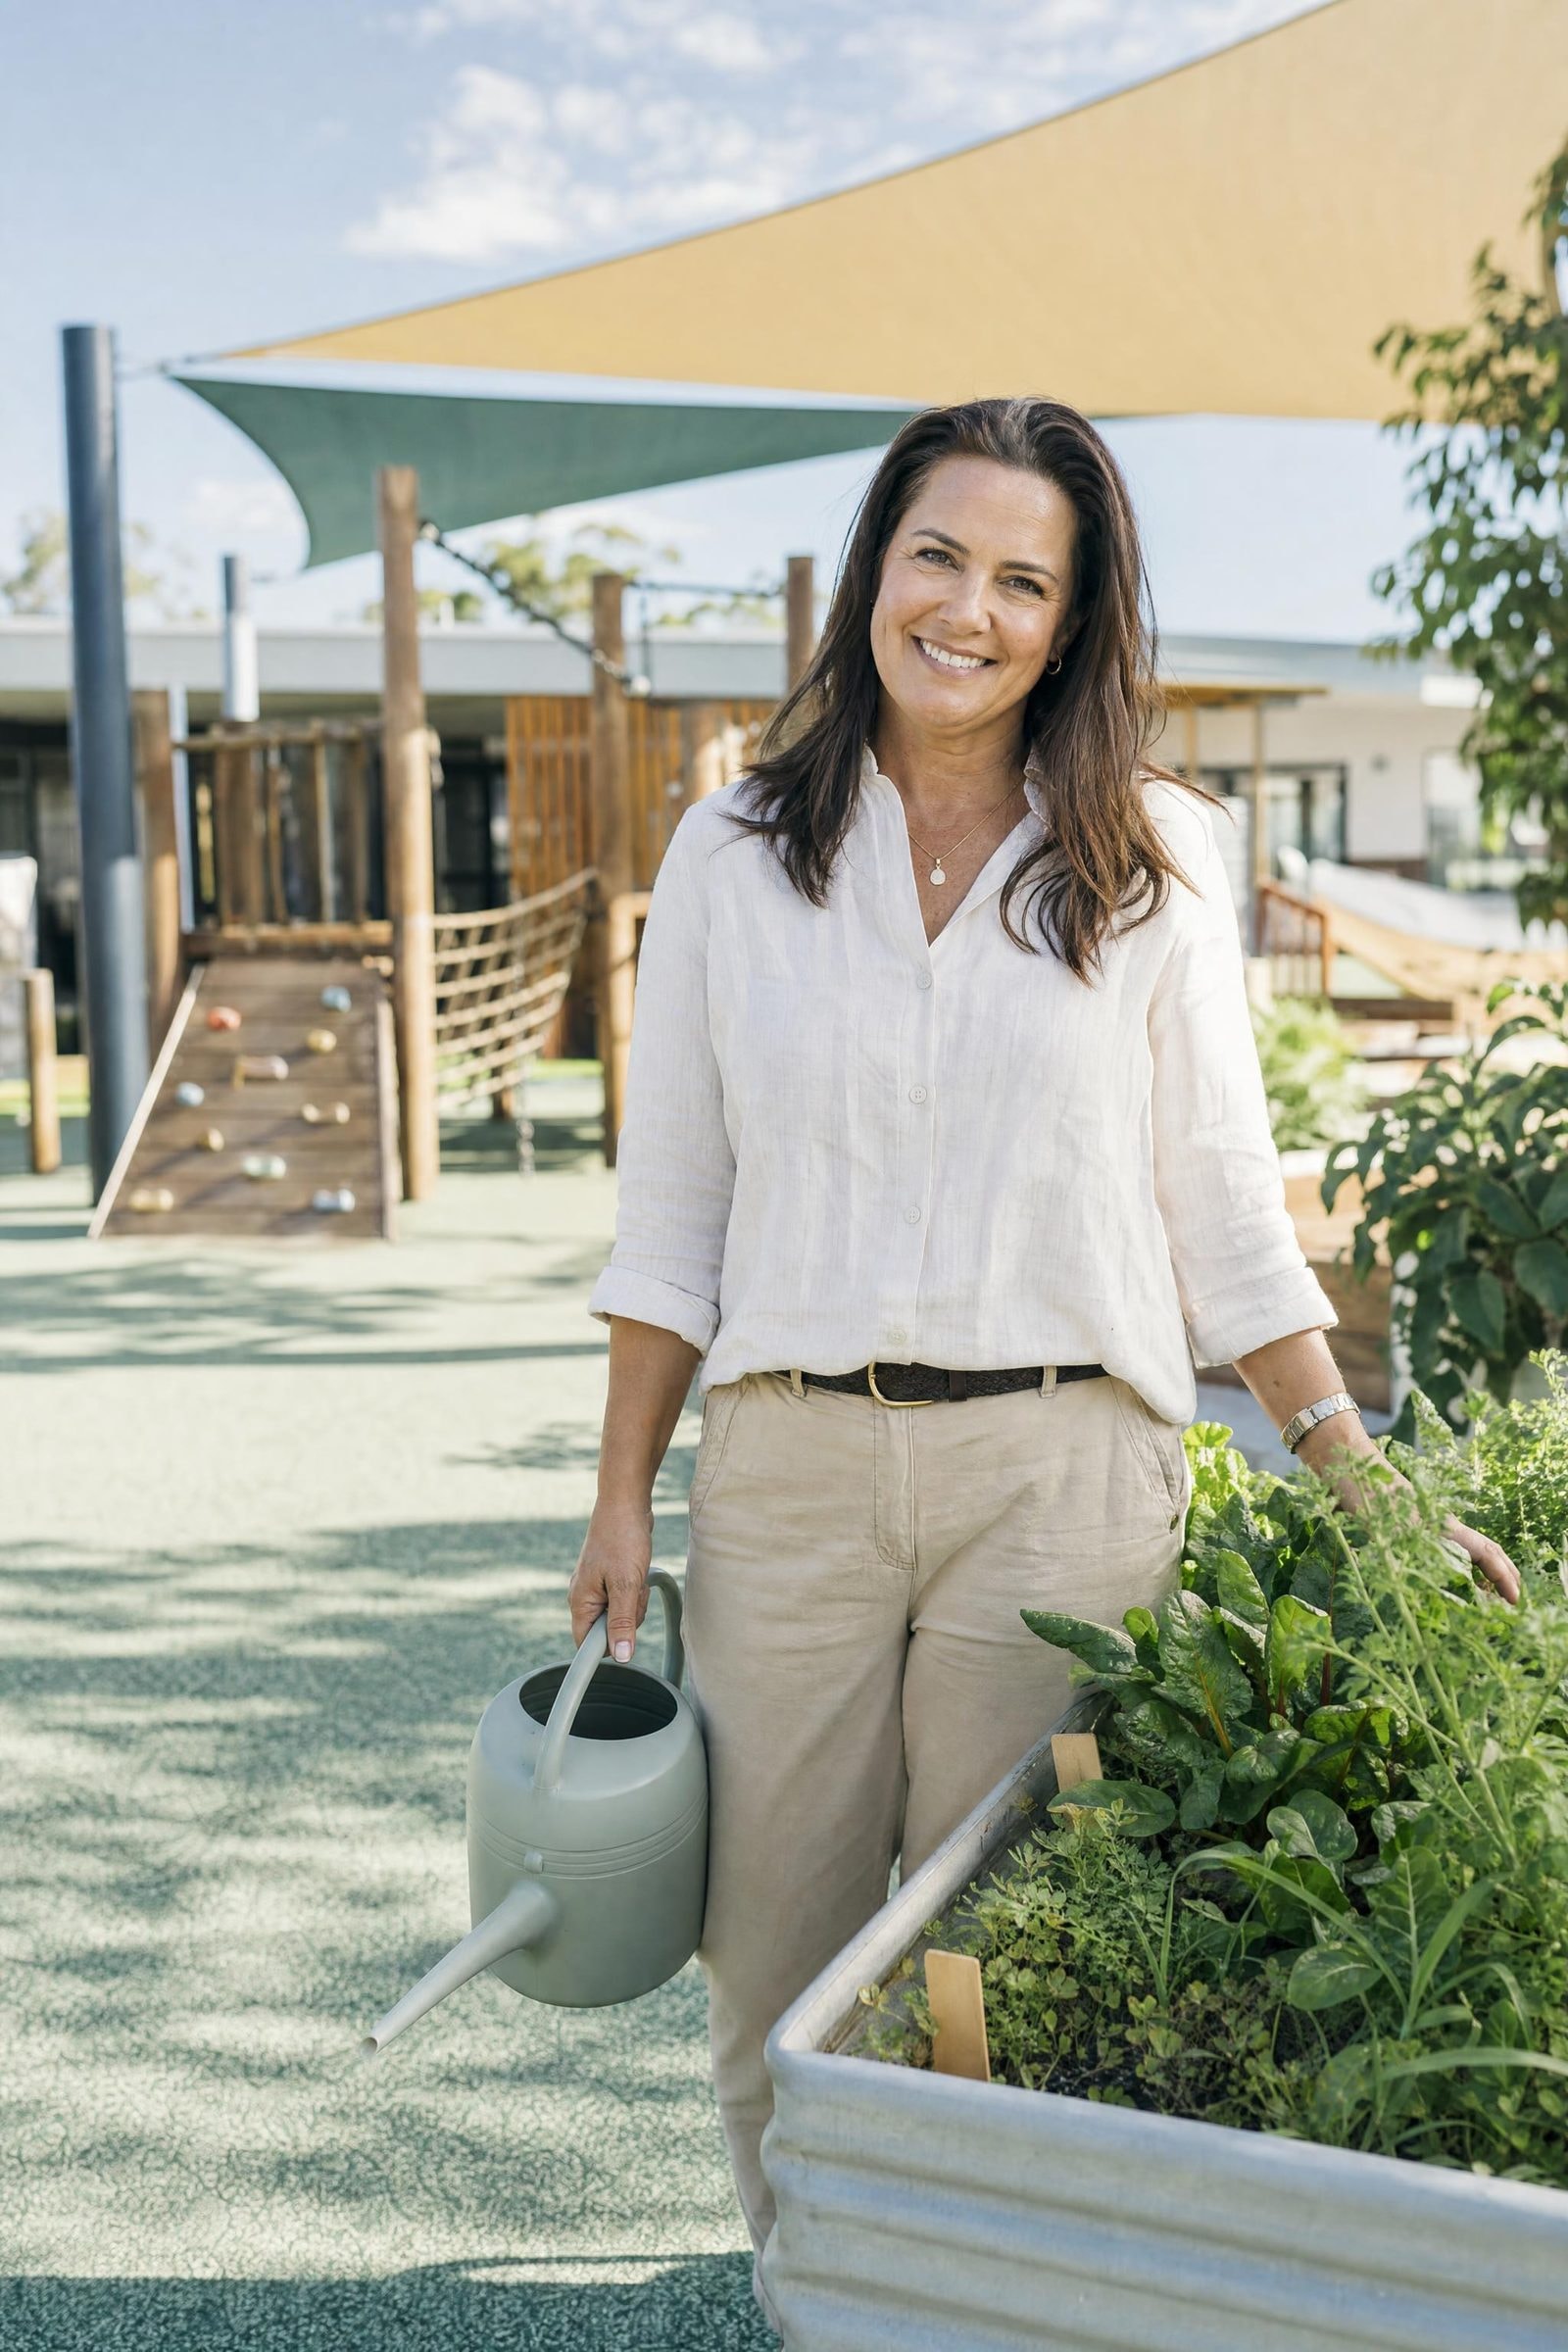
Industry guide
Finance for childcare centres, shaped around how you get paid.
Childcare income is subsidised, recurring and highly regulated. Finance decisions hinge on licensed places, occupancy and the lease or freehold under the centre.
 340 client reviews



One broker from your first call through to funding.
See which options fit your business.
Tell us what you need. A Lyft Money broker who knows childcare centres compares 48+ lenders and explains the rate, fees and repayments before you decide.
Access to 57+ childcare centres lenders
Lenders on our panel that fund childcare centres.

































At a glance
Childcare centres: the numbers that matter.
- Typical amounts
- $250,000 – $20,000,000
- Typical speed
- 2–6 weeks
- Indicative rates
- 6.2% – 9.9% p.a.
- Finance options
- 6 structures compared
- Lenders active here
- 1+ on our panel
- Assets we fund
- Commercial kitchen, Shop fit-out, Security system and more
In plain English
Finance for childcare centres: how it works.
Childcare finance is lending to long day care and early learning centres, covering centre fit-outs, playground and equipment upgrades, centre acquisitions and the property the service operates from.
A long day care service earns from a combination of the Child Care Subsidy paid to the provider and parent gap fees, both flowing on a weekly or fortnightly cycle. Revenue is therefore unusually predictable, driven almost entirely by licensed places multiplied by occupancy. Costs are dominated by wages under an award with mandated educator-to-child ratios, which are not flexible. That combination — steady income, fixed cost structure — makes lenders comfortable, provided occupancy is solid and the service has a clean regulatory record.
Capital needs are concentrated in the physical service. Compliant indoor and outdoor learning environments, shade structures, soft-fall, playground equipment, commercial kitchens, laundries and bathrooms scaled for children all require significant investment, and the National Quality Standard assessment gives centres a strong reason to keep the environment current. Centre acquisitions are common as operators consolidate, and the deal is usually assessed on licensed places, occupancy history, assessment rating and the security of the lease or the value of the freehold.
The cash-flow pattern we plan around
Weekly or fortnightly Child Care Subsidy payments plus parent gap fees against a fixed award wage bill, with occupancy dipping over January and school holiday periods.
What childcare centres typically fund
- Centre fit-out and compliant learning environments
- Playground, shade and soft-fall works
- Commercial kitchen and laundry equipment
- Acquiring an existing centre
- Purchasing the centre premises
Documents lenders usually ask for
- ABN, service approval and provider approval details
- Two years of financials with occupancy and enrolment data
- Lease or contract of sale, plus works or equipment quotes



A clear next step
How to get finance for childcare centres.
Our AI helps check lender fit across 48+ lenders. Your broker reviews the options and explains what they mean for you.
- 01
Property and purpose
Owner-occupied, investment or SMSF; purchase or refinance.
- 02
Servicing assessment
Financials, leases or rental income depending on doc type.
- 03
Valuation and settlement
Lender valuation, approval and settlement with your solicitor.
The lender makes the final credit decision. Available options depend on your business and the lender’s assessment.
Before you make a decision
Estimate commercial property loan repayments.
Know what lands and what leaves. Adjust the amount, rate and term to see the repayment and total cost.
- Number of repayments
- 48
- Total interest (est.)
- $11,541
- Total repaid (est.)
- $86,541
This calculator is a guide only. It uses simplified assumptions, excludes fees and charges unless stated, and is not an offer or quote. Actual repayments are confirmed by the lender in its loan contract.
From Lyft Money clients
Clear advice.
People who stay in touch.
Rated 5.0 from 340 Google reviews across the types of finance we arrange. Read them on Google.
“keeping us informed every step of the way”
“He explained all the financing options clearly”
“helped out my business”
Finance options for childcare centres
Commercial property loan
Childcare freehold is a distinct asset class. A purpose-built centre on a long lease to an approved provider is attractive to lenders and to investors, and operators who own their premises remove the single largest risk in the business — a landlord declining to renew after you have invested in a compliant fit-out.
Fit-out finance
Bringing a tenancy up to a compliant early learning environment is substantial construction: children’s bathrooms, nappy change facilities, a commercial kitchen, sleep rooms, storage, and outdoor areas with shade, soft-fall and natural play elements. None of it is removable.
Business acquisition finance
Buying a centre is assessed on licensed places, historical occupancy, the assessment and rating outcome, the educator team and the remaining lease term. Lenders will fund goodwill for an experienced operator with a clean regulatory history; a first-time buyer with no sector background will find the panel much narrower.
Equipment loan
Playground equipment, shade sails, commercial ovens and dishwashers, industrial laundry, cots and furniture, security and sign-in systems and centre IT are all financeable against the assets themselves. Bundling a planned refresh into a single three-to-five-year facility is cheaper than drawing from cash or a working-capital limit.
Unsecured business loan
Unsecured lending suits the short and specific: covering a January occupancy dip, funding a marketing campaign to lift enrolments, meeting a compliance rectification cost, or bridging to a subsidy adjustment. It funds quickly with light documentation and prices accordingly.
Business line of credit
A revolving limit gives a centre operator a buffer against the timing of subsidy payments and the predictable seasonal dip when families take January off while educators are still rostered and paid. Draw when occupancy softens, repay through the strong months from February onward.
Assets we finance for childcare centres
Lenders active in this space
Banjo Loans — among others on our panel of 48+. Your broker checks fit before anything is submitted.
Key terms
Childcare centre finance
Childcare centre finance is lending to an approved early education and care service, assessed on licensed places, occupancy, the National Quality Standard rating and the strength of the lease or freehold.
Licensed places
Licensed places are the maximum number of children a childcare service is approved to care for at one time, and they set the ceiling on the revenue a centre can generate.
How is a childcare centre purchase financed?
Centre acquisition finance funds the purchase of an operating service against its occupancy, Child Care Subsidy income and goodwill, and the freehold can be financed with a commercial property loan at the same time. Lenders look at licensed places, occupancy history, ratings and the operator’s experience.
Can playground, fit-out and equipment upgrades be financed?
Yes. Playground equipment, soft fall, shade, furniture, kitchen equipment and room fit-outs can be funded under one facility, with suppliers paid as the work is done and the loan repaid over three to seven years. Upgrades that lift ratings or add licensed places are well regarded by lenders.
How do centres manage cash flow over January and school holidays?
A line of credit sized to the seasonal dip covers award wages while occupancy is lower, and is repaid as enrolments return. Because Child Care Subsidy income is government-backed and predictable, lenders price childcare facilities well for established operators.
Can I finance building a new childcare centre?
Yes. Development finance funds land and construction of a new centre against the approved plans and the projected income, converting to a commercial property loan when the centre opens. Lenders look at demand in the catchment, the operator’s experience and pre-enrolments. It is a specialist area and a broker with childcare experience matters.
How much deposit do I need for a commercial property purchase?
Commercial lending is usually written to a lower loan-to-value ratio than residential, so expect to contribute more. Owner-occupied purchases commonly sit around 65% to 80% LVR depending on the property type and the strength of the business, meaning a deposit of roughly 20% to 35% plus costs. Specialised premises attract tighter LVRs than standard offices, warehouses or retail. Using equity in an existing property can reduce or replace the cash deposit.
How long does a commercial property settlement usually take?
Plan for six to twelve weeks from application to settlement in most cases. The steps that take time are the full financial assessment, a formal valuation of the property, legal documentation and any conditions the lender imposes before funding. Purchases with tight contract dates need the finance clause negotiated realistically at the outset. Refinances of an existing loan can be quicker where the property and the borrower are straightforward.
Can I have interest-only repayments on a commercial property loan?
Yes. Interest-only periods of one to five years are common on commercial property loans, particularly for investors who want to maximise cash flow and deductions, and some lenders will extend them on review. During the interest-only period you pay only the interest, so repayments are lower but the principal does not reduce. Owner-occupiers usually move to principal-and-interest so the debt is paid down over the term. Lenders assess an interest-only loan on the higher principal-and-interest repayment that follows, so the business or lease income still needs to support it.
What is the difference between an owner-occupied and an investment commercial property loan?
An owner-occupied commercial loan finances premises your own business will trade from, and lenders assess it largely on the strength of that business. An investment commercial loan finances a property leased to someone else, and lenders assess it on the lease income, the tenant and the lease term remaining. Owner-occupied loans often allow higher borrowing and can be structured through the trading entity, while investment loans lean on the quality of the lease. Both can include a residential-security top-up where more borrowing is needed.
What interest rates apply to commercial property loans?
Commercial property rates are usually a little higher than home loan rates and vary with the lender, the property type, the loan-to-value ratio and how the loan is documented. Full-doc loans with strong financials and a standard property attract the sharpest pricing; low-doc or lease-doc loans and specialised assets are priced higher. Loans can be fixed, variable or split, and interest-only periods are common for investors. Lyft Financial compares bank and non-bank lenders so you see the rate, fees and repayment side by side before you commit.
What is a lease-doc commercial loan?
A lease-doc loan is assessed on the rental income from a commercial lease rather than on the borrower’s full financial statements. Lenders check that the rent covers the interest by an agreed margin and that the lease term, tenant and property are sound. It suits investors whose tax returns do not reflect their position, or who want a faster approval, and it usually comes with a lower maximum loan-to-value ratio and a slightly higher rate than a full-doc loan.
Your business. Your decision.
See your options.
Know the costs.
Decide with confidence.
One broker to explain it. Clear numbers before you proceed.
No obligation to proceed.