
Industry guide
Finance for ndis providers, shaped around how you get paid.
NDIS providers pay support workers every fortnight and claim afterwards. The scheme pays reliably, but rarely on the same rhythm as payroll.
 340 client reviews



One broker from your first call through to funding.
See which options fit your business.
Tell us what you need. A Lyft Money broker who knows ndis providers compares 48+ lenders and explains the rate, fees and repayments before you decide.
Access to 57+ ndis providers lenders
Lenders on our panel that fund ndis providers.

































At a glance
NDIS providers: the numbers that matter.
- Typical amounts
- $5,000 – $500,000
- Typical speed
- 24–72 hours after documents are received
- Indicative rates
- 9.9% – 29.5% p.a.
- Finance options
- 6 structures compared
- Lenders active here
- 3+ on our panel
- Assets we fund
- Van, Business car, IT hardware and more
In plain English
Finance for ndis providers: how it works.
NDIS provider finance is lending to registered and unregistered disability service providers, funding modified vehicles, support worker wages ahead of claim payments, SDA and SIL property, and assistive equipment.
A disability support provider delivers services, records them, claims through the NDIS portal, and receives payment — a process that works but takes time, and takes longer where plan managers or self-managed participants are involved. Support workers are paid fortnightly under the SCHADS award with penalty rates for evenings, weekends and sleepovers. Growth means hiring more staff before the claims from their work arrive, so a provider expanding quickly consumes cash even while every service delivered is fully funded.
Capital needs centre on transport and property. Wheelchair-accessible vehicles with hoists or ramps cost far more than the base vehicle and are essential to community access supports. Providers delivering supported independent living need suitable housing, and Specialist Disability Accommodation is a distinct property class with its own funding stream and lender treatment. Price limits are set by the NDIA and reviewed annually, so margins cannot simply be raised to cover cost increases — which makes disciplined finance structuring more important in this sector than most.
The cash-flow pattern we plan around
Fortnightly SCHADS award wages with penalty rates against NDIS claims paid after service delivery, with plan-managed and self-managed participants adding further delay.
What ndis providers typically fund
- Wheelchair-accessible and modified vehicles
- Support worker wages ahead of claim payments
- SIL housing and SDA property
- Assistive technology and equipment
- Rostering, compliance and client management systems
Documents lenders usually ask for
- ABN and NDIS registration or provider details
- 6–12 months of bank statements showing claim receipts
- Vehicle and modification quotes, or property contract



A clear next step
How to get finance for ndis providers.
Our AI helps check lender fit across 48+ lenders. Your broker reviews the options and explains what they mean for you.
- 01
Tell us what you need
Purpose, amount, how long you have been trading and how cash moves through the business.
- 02
Share your documents
Usually ID and 6 months of business bank statements. Some lenders ask for BAS or financials above certain amounts.
- 03
Compare and decide
Your broker presents matching options with the rate, repayments, fees and total cost. You give the go-ahead before submission.
The lender makes the final credit decision. Available options depend on your business and the lender’s assessment.
Before you make a decision
Estimate unsecured business loan repayments.
Know what lands and what leaves. Adjust the amount, rate and term to see the repayment and total cost.
- Number of repayments
- 36
- Total interest (est.)
- $19,259
- Total repaid (est.)
- $94,259
This calculator is a guide only. It uses simplified assumptions, excludes fees and charges unless stated, and is not an offer or quote. Actual repayments are confirmed by the lender in its loan contract.
From Lyft Money clients
Clear advice.
People who stay in touch.
Rated 5.0 from 340 Google reviews across the types of finance we arrange. Read them on Google.
“keeping us informed every step of the way”
“He explained all the financing options clearly”
“helped out my business”
Finance options for ndis providers
Unsecured business loan
An unsecured term loan funds a defined growth step: onboarding a group of new participants, recruiting and training support workers ahead of the claims their work will generate, or covering the wage cost of a new SIL house before it is fully occupied. Funding is quick and documentation light.
Business line of credit
A revolving limit is the cleanest answer to the claim cycle. Draw to meet the fortnightly payroll, repay as claims are paid, and keep the headroom for the fortnights where plan managers are slow.
Business vehicle finance
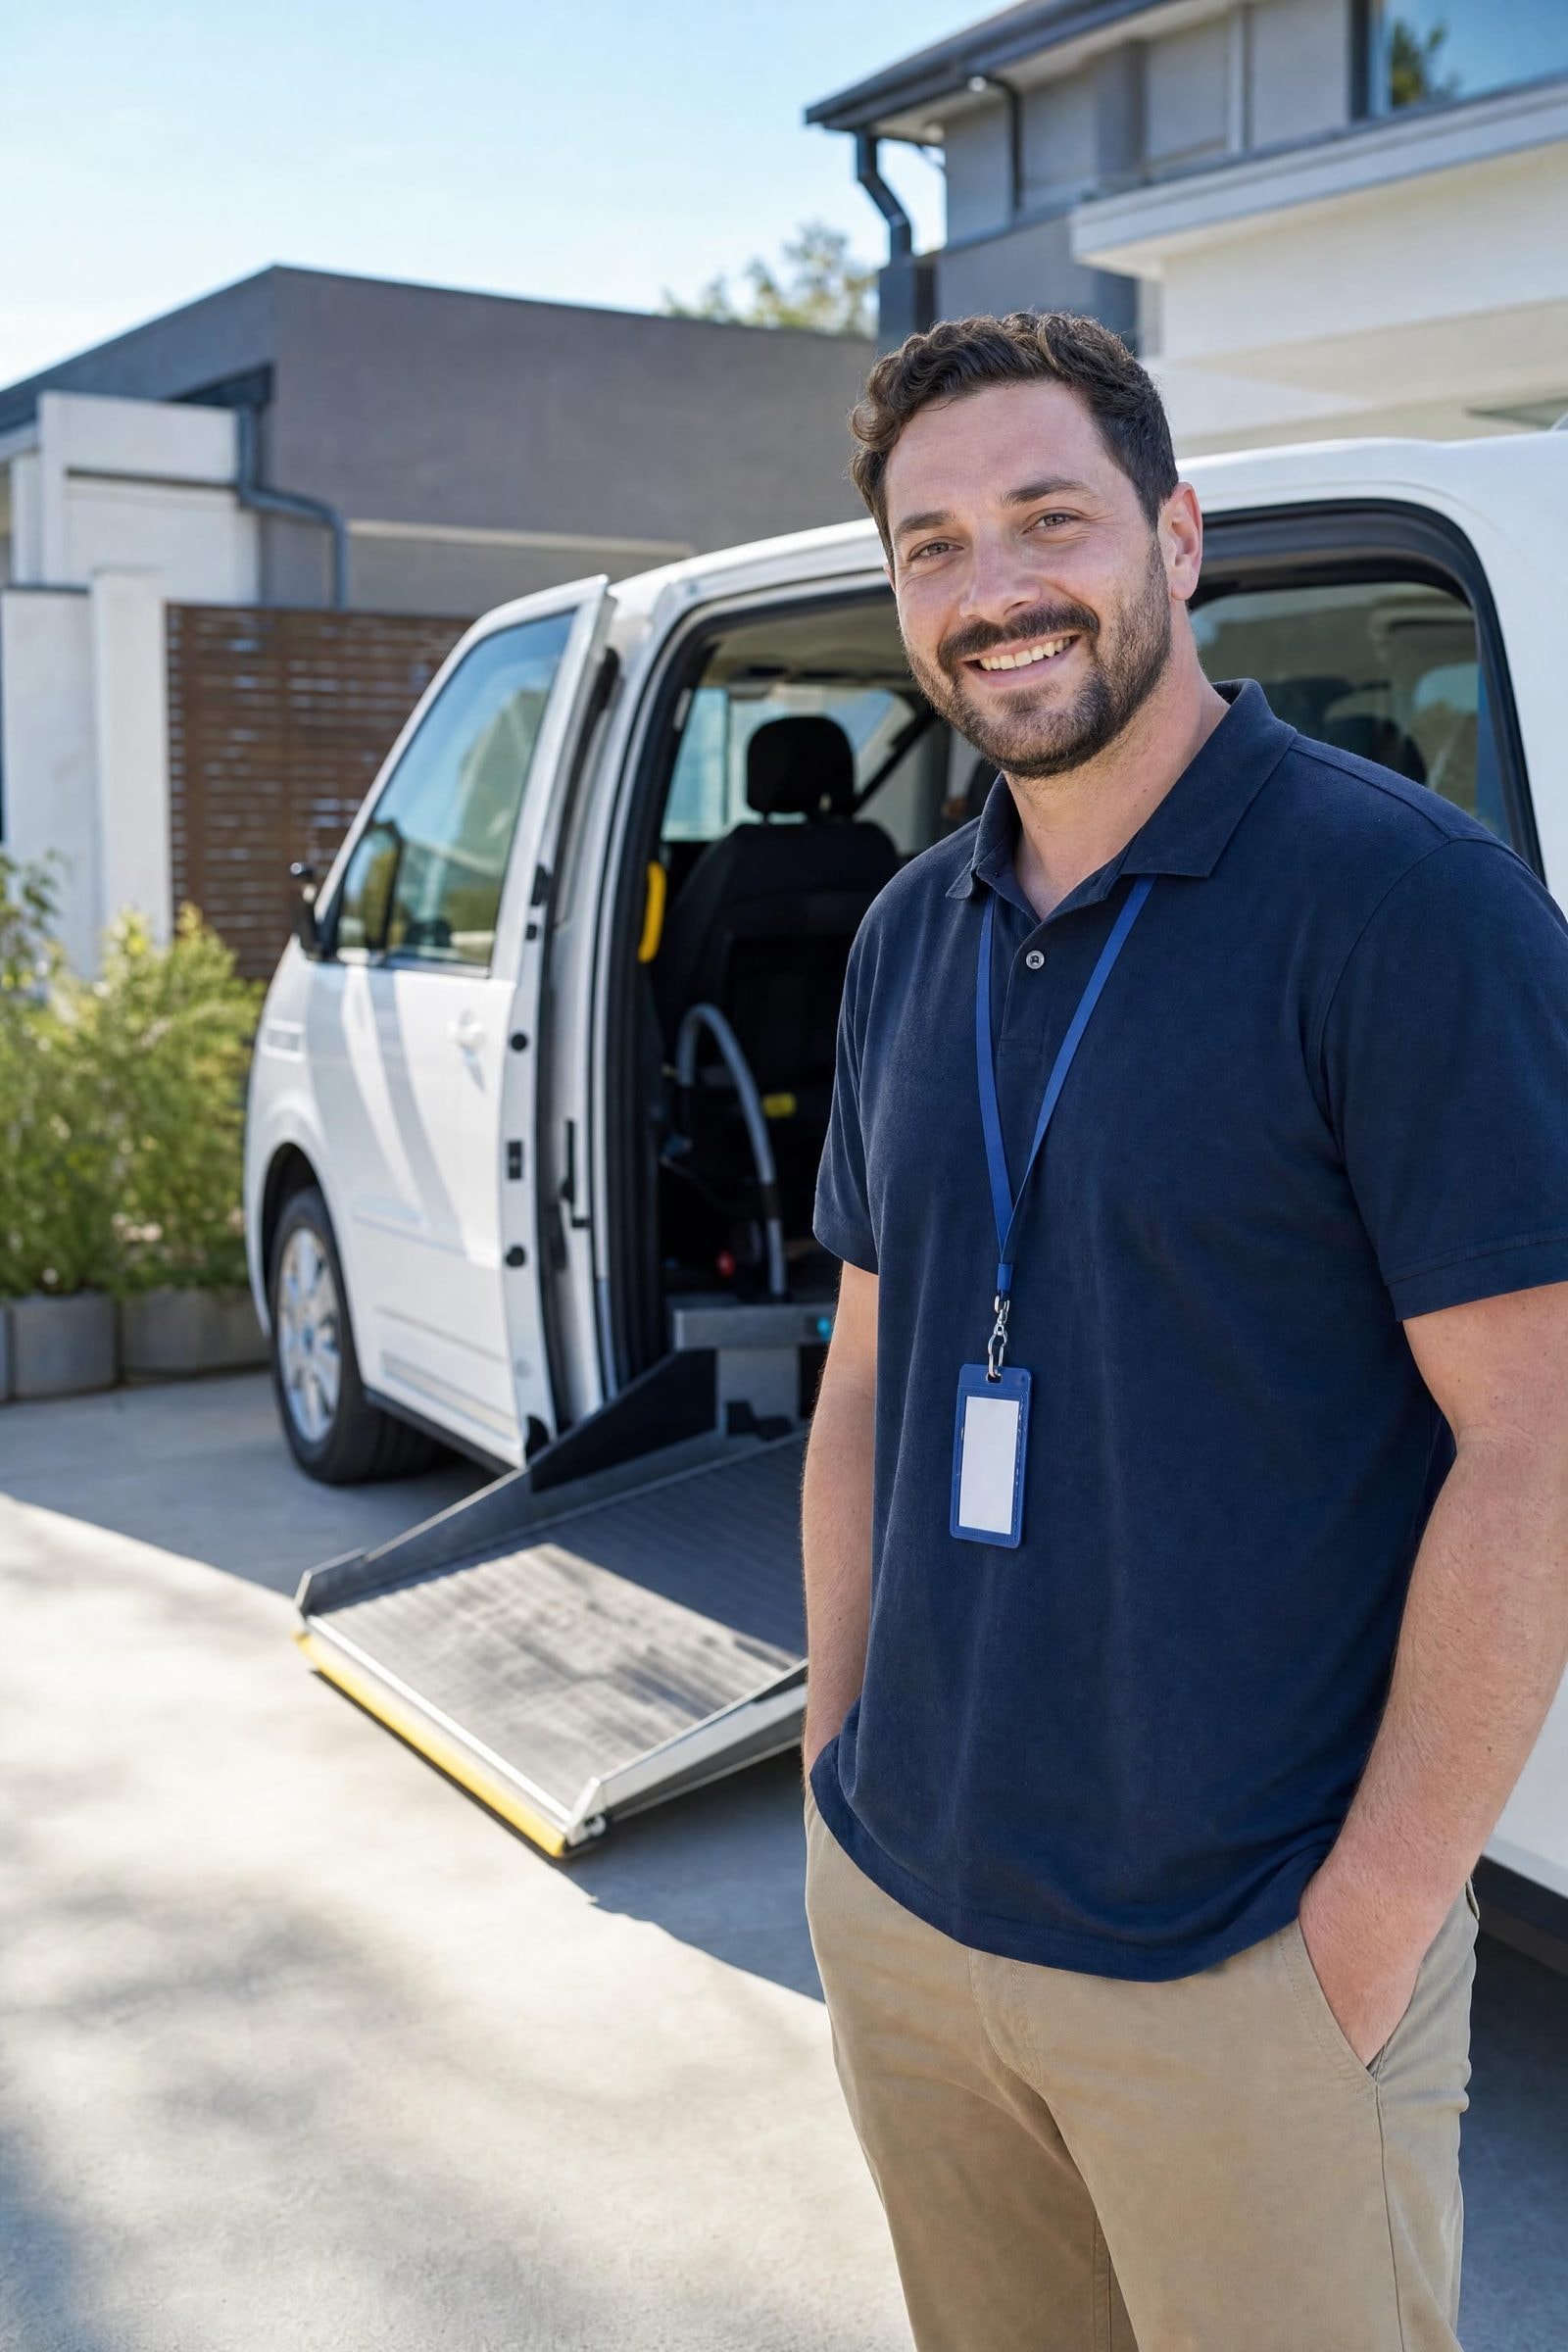
A wheelchair-accessible vehicle is a base van plus a conversion — floor lowering, ramp or hoist, restraints and certification — that can add fifty per cent or more to the price. Finance the vehicle and modification together as a single asset rather than paying the conversion cost from cash.
Chattel mortgage
For a GST-registered provider, a chattel mortgage over a vehicle means ownership from day one and, generally, a GST claim on the purchase price in the next BAS. Interest and depreciation are deductible to the extent of business use.
Commercial property loan
Providers delivering supported independent living need appropriate housing, and Specialist Disability Accommodation carries its own NDIA-funded income stream tied to design category and location. Lenders treat SDA as a specialised asset class: some understand it well, many do not, and valuations depend on the SDA payment as much as on comparable sales.
Equipment loan
Assistive technology, hoists, adjustable beds, therapy and sensory equipment, and the rostering, compliance and client management systems a registered provider must run are all financeable against the assets over three to five years. Bundling a year of planned purchases into one facility keeps the cash buffer intact for payroll, which is where a provider actually needs it.
Assets we finance for ndis providers
Lenders active in this space
Banjo Loans, Moneytech, Prospa — among others on our panel of 48+. Your broker checks fit before anything is submitted.
Key terms
NDIS provider finance
NDIS provider finance is lending to disability service providers, assessed on NDIS claim history and participant numbers, and used for vehicles, equipment, property and the working capital between service delivery and payment.
Claim cycle gap
The claim cycle gap is the period between paying support workers for delivered services and receiving the corresponding NDIS payment, which widens where participants are plan-managed or self-managed.
How do NDIS providers fund wages before claims are paid?
Invoice finance against NDIS claims and plan-manager invoices, or a line of credit, covers fortnightly SCHADS wages while claims are processed and plan-managed participants pay, and the facility grows with participant numbers. Because the NDIS is government-funded, lenders price these facilities well for registered providers.
Can wheelchair-accessible and modified vehicles be financed?
Yes. Vans and buses with wheelchair lifts, ramps and restraints are financed as business vehicles with the modification included when quoted with the vehicle, over terms of up to seven years. Established providers are usually approved on low documentation.
Can I finance SDA or SIL property?
Yes. Specialist disability accommodation and supported independent living properties are financed with commercial property and construction loans against the enrolled dwelling’s NDIS income, with lenders looking at SDA enrolment, participant demand and the provider’s experience. It is a specialist area and a broker with NDIS experience matters.
What do lenders look for in an NDIS provider?
Registration or evidence of participant agreements, consistent claim income in the bank statements, wage costs and staffing, tax up to date and a clean credit file. Established providers with steady claim income are often approved within a day or two on bank statements.
How much can my business borrow without security?
Most unsecured business lenders size a loan against turnover rather than assets, commonly to a share of monthly or annual revenue. On our panel, unsecured facilities generally run from around $5,000 to roughly $500,000, with larger amounts usually requiring security or stronger financials. The actual figure depends on your trading history, cash flow, existing commitments and credit profile. We can tell you the realistic range for your business before any application is submitted, but no amount is guaranteed until a lender approves it.
What is the difference between a business loan and a business overdraft?
A business loan advances a fixed amount that you repay over a set term. An overdraft is a limit attached to a transaction account that you draw on and repay as needed, with interest charged only on the balance used. A loan suits a defined purchase or a one-off cost; an overdraft suits timing gaps between paying suppliers and being paid. Overdrafts often carry a line fee whether or not you draw the limit, so compare the total cost of holding the facility.
How long does my ABN need to be active?
It varies by lender and product. Many unsecured business lenders want at least six to twelve months of trading, while some asset finance lenders will consider a new ABN where the director has industry experience, a clean credit file and often property ownership or a deposit. Registration for GST is frequently expected once turnover reaches the threshold. A short ABN history is not an automatic decline, but it narrows the panel and usually affects the rate and structure offered.
Do I have to own property to get business finance?
No. Plenty of finance is written for non-property owners, especially asset finance where the equipment itself is the security, and unsecured lending assessed on cash flow. That said, property ownership widens the panel and often improves pricing, because it gives a lender an additional avenue if things go wrong. If you do not own property, expect more weight on trading history, bank conduct and the quality of the asset being financed.
Why do two lenders quote such different rates for the same equipment?
Because they are pricing different levels of risk and using different funding. A bank with a long assessment process and full financials can price sharply; a fintech approving in hours from bank statements charges more for that speed and the lighter verification. Asset type, age, term, deposit, credit history and whether directors own property all move the number. That is the point of a panel — the same deal can land very differently, so it is worth comparing rather than accepting the first quote.
Can I pay a loan out early and will it cost me?
Most facilities can be paid out early, but the cost depends on the structure. Fixed-rate equipment finance often includes a break cost or an early termination fee that recovers part of the lender's expected interest, so paying out in year one rarely saves the full remaining interest. Some short-term unsecured loans have a fixed total repayable, meaning early repayment saves little or nothing. Ask for the payout figure in writing before you decide.
Your business. Your decision.
See your options.
Know the costs.
Decide with confidence.
One broker to explain it. Clear numbers before you proceed.
No obligation to proceed.