
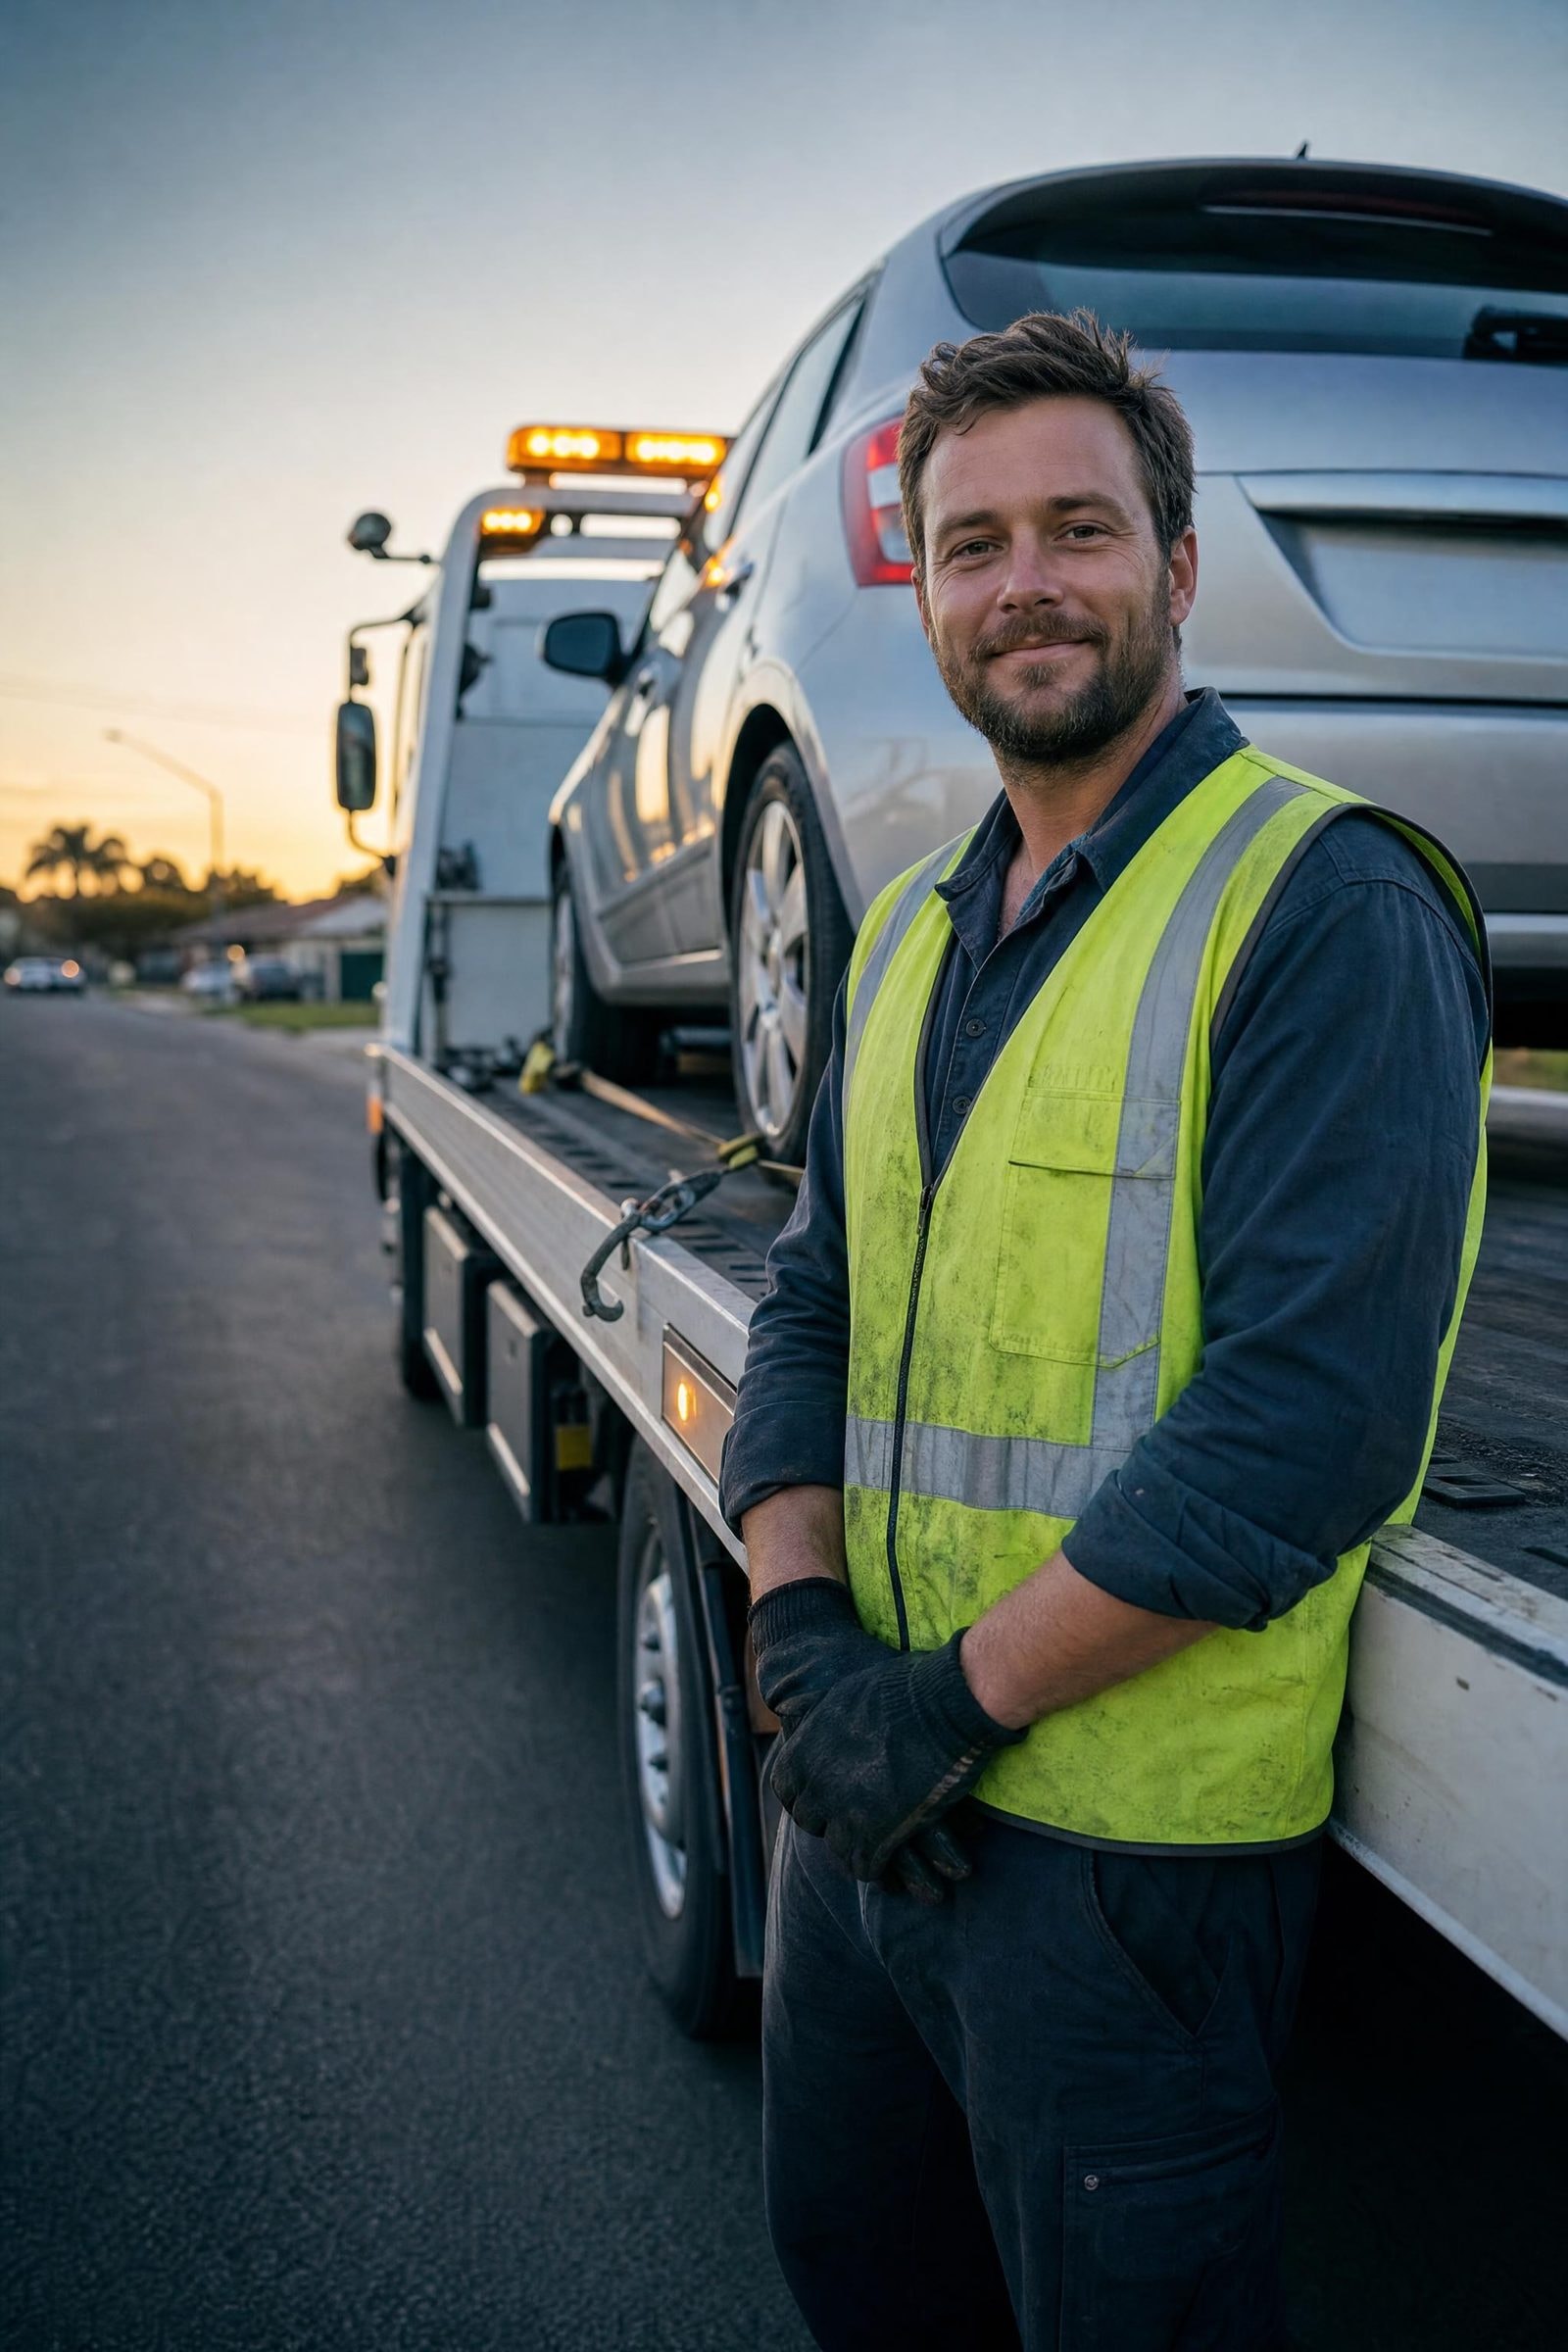
Trucks
Tow truck finance from 48+ Australian lenders.
Tow trucks are licensed, contracted and worked hard. We look at your accreditation and work source, then match the term to how long the truck will realistically last.
 340 client reviews



One broker from your first call through to funding.
See which tow truck finance options fit your business.
Tell us what you are buying. A Lyft Money broker compares 48+ lenders and explains the rate, balloon, fees and total cost before you decide.
Access to 21+ tow truck finance lenders
Lenders on our panel that fund tow truck finance.





















At a glance
Tow truck finance: the numbers that matter.
- Typical price
- $70,000 – $350,000
- Terms
- Up to 84 months
- Indicative rates
- 6.9% – 14.5% p.a.
- Typical speed
- 24–48 hours for low-doc up to $150k; longer for full-doc
- Usual structure
- Chattel mortgage
- Useful life
- About 14 years
In plain English
What is tow truck finance?
Tow truck finance is funding for a tilt tray, slide bed or wrecker used to recover and transport vehicles, secured against the truck. Tow trucks are licensed assets in most Australian states, and lenders will generally want to see the operator’s accreditation and contract arrangements alongside the usual credit assessment.
Tow truck operators fall into distinct groups. Some hold accident-towing allocations under a state scheme, some hold contracts with motoring clubs or insurers, and others do dealership deliveries, machinery transport and general recovery work. Each has a different revenue pattern, and lenders read the application accordingly: a truck backed by contracted work is a straightforward proposition, while an operator relying on casual call-outs alone will be asked more questions about income.
The build matters as much as the truck. A slide bed with a wheel lift and a decent winch handles far more work than a basic tilt tray, and the difference in capability usually pays for itself. Because the body is a major part of the value, get the whole build quoted and financed together. Your broker can arrange the funding to settle when the completed truck is delivered rather than at cab chassis stage.
How lenders assess tow truck finance
Tow trucks combine a chassis with a specialised body, so lenders value the two together and will ask for the full build specification. In states with tow truck licensing, evidence of the operator’s licence or accreditation is usually required before settlement. Businesses with a panel contract, motoring club work or dealership arrangements are viewed more favourably than speculative start-ups. Bodies fitted after purchase can be added to the same contract with the right invoicing. Age limits generally require the truck to be under 15 years at term end.
New or used
Used tilt trays on Japanese cab chassis are the most common purchase; new builds are typical where a specific bed length or capacity is needed.
Before you buy
- Check the bed, winch, cable and wheel-lift for wear — the body works harder than the chassis on a tow truck.
- Make sure the deck length and capacity suit what you tow; recovering utes and vans needs more bed than a small car carrier offers.
- Confirm licensing and signage requirements in your state before you commit, as they can affect what you are allowed to operate.
Commonly financed
- Isuzu FRR 110-260 tilt tray
- Hino 500 Series FE tilt tray
- Fuso Fighter 1024 tilt tray
- Jerr-Dan wrecker bodies
- Iveco Eurocargo tilt tray



A clear next step
How to finance a tow truck.
Our AI helps check lender fit across 48+ lenders. Your broker reviews the options and explains what they mean for you.
- 01
Confirm the asset
Dealer or private sale, new or used, price and age of the asset.
- 02
Structure the loan
Term, deposit and balloon matched to cash flow and asset life.
- 03
Settle and collect
Lender pays the supplier directly; you take delivery.
- ID and ABN
- Invoice or quote for the asset
- Bank statements or financials depending on amount
The lender makes the final credit decision. Available options depend on your business and the lender’s assessment.
Before you make a decision
Estimate your tow truck repayments.
Adjust the price, rate, term and balloon to see the repayment and the total cost over the term.
- Number of repayments
- 60
- Balloon at end of term
- $42,000
- Total interest (est.)
- $59,445
- Total repaid (est.)
- $269,445
This calculator is a guide only. It uses simplified assumptions, excludes fees and charges unless stated, and is not an offer or quote. Actual repayments are confirmed by the lender in its loan contract.
From Lyft Money clients
Clear advice.
People who stay in touch.
Rated 5.0 from 340 Google reviews across the types of finance we arrange. Read them on Google.
“keeping us informed every step of the way”
“He explained all the financing options clearly”
“helped out my business”
Ways to finance a tow truck
Key terms
What is tow truck finance?
Tow truck finance is a secured loan or lease used to buy a tilt tray, slide bed or wrecker, with the completed truck as security. Terms usually run 48 to 84 months and the specialised body is generally funded together with the cab chassis.
Do I need a licence to operate a tow truck in Australia?
Most states and territories regulate tow truck operators and drivers through a licensing or accreditation scheme, particularly for accident towing. Requirements differ by jurisdiction, and lenders commonly ask to sight the relevant licence before settling the finance.
Do I need a tow truck licence to get finance?
The lender does not issue it, but most states require an operator and driver licence for tow trucks, and lenders will usually ask for evidence that you hold or have applied for it, along with any accident allocation or roadside contracts. Having the licence sorted before you apply speeds up approval.
Can I finance a used tow truck?
Yes. Used tilt trays and wreckers are financed on age, kilometres, the condition of the body and hydraulics and the service history. Mainstream lenders take trucks up to about 12 to 15 years old at the end of the term; older units suit specialist lenders on shorter terms. Private and auction purchases are accepted with a PPSR clearance and inspection.
Can I finance a tilt tray with the tow rig included?
Yes. The tilt tray body, winch, underlift and hydraulics can be financed with the cab chassis when quoted together, so the complete tow truck settles on one contract. Lenders finance tilt trays, wreckers and heavy recovery units for licensed operators, with terms up to seven years on new trucks.
Can I finance a second truck to grow my towing business?
Yes. Established operators with a good asset finance history often get pre-approval for the next truck on low documentation, and roadside assistance or insurance contracts strengthen the case. A broker manages lender exposure across your fleet so each addition is approved without delays.
Do I need a deposit for equipment finance?
Often no deposit is required, particularly for established businesses buying standard assets from a dealer. A deposit is more likely where the business is new, the asset is older or specialised, the credit profile is weaker, or the amount is large relative to turnover. Deposits typically range from around 10% to 30% in those cases. Putting money in reduces the amount financed and can improve the terms offered, but it is not always necessary.
What fees are normally charged on equipment finance?
The common ones are an establishment or documentation fee charged at settlement, a monthly account-keeping fee, and a PPSR registration fee for recording the lender's interest in the asset. A brokerage fee may also apply, which we disclose to you in writing before anything is submitted. Some agreements include an early termination or break cost. Fees vary by lender and are typically a modest part of total cost compared with the interest, but they should still be compared.
How large a balloon can I set?
Lenders publish maximum residual or balloon percentages that fall as the term lengthens, because the asset is worth less at the end of a longer term. For a vehicle, a common pattern is up to roughly 50% on a two-year term, reducing to around 20% to 30% on a five-year term. The ATO also sets minimum residual values for finance leases. A larger balloon lowers monthly repayments but increases total interest and leaves a lump sum to deal with at the end.
Is hire purchase still used in Australia?
It is far less common than it once was. Under hire purchase the financier owns the asset and you hire it, with ownership transferring automatically after the final instalment. Since the GST changes that made chattel mortgage more attractive for businesses accounting on a cash basis, most equipment lending is written as a chattel mortgage or lease instead. Some lenders still offer commercial hire purchase, and your accountant can advise whether it suits your circumstances.
What is PPSR registration and why does the lender do it?
The Personal Property Securities Register is the national register of security interests in personal property, including vehicles and equipment. When a lender finances an asset, it registers its interest so the security is publicly recorded and its priority is protected if the asset is sold or the business fails. It also means a buyer searching the register will see the finance. The registration is released once the contract is paid out, and a small registration fee is usually passed on to you.
How does a balloon payment work on a chattel mortgage?
A balloon is a lump sum left to pay at the end of a chattel mortgage, which lowers the regular repayments during the term. For example, a 30 per cent balloon on a $100,000 vehicle leaves $30,000 to pay at the end, so the monthly amount is calculated on $70,000 plus interest on the full balance. Balloons are commonly set between 0 and 40 per cent depending on the asset and term, and at the end you can pay it out, refinance it or sell the asset to clear it. A balloon reduces monthly cost but increases total interest, so your broker shows both figures side by side.
Your business. Your decision.
See your options.
Know the costs.
Decide with confidence.
One broker to explain it. Clear numbers before you proceed.
No obligation to proceed.