
Personal and leisure assets
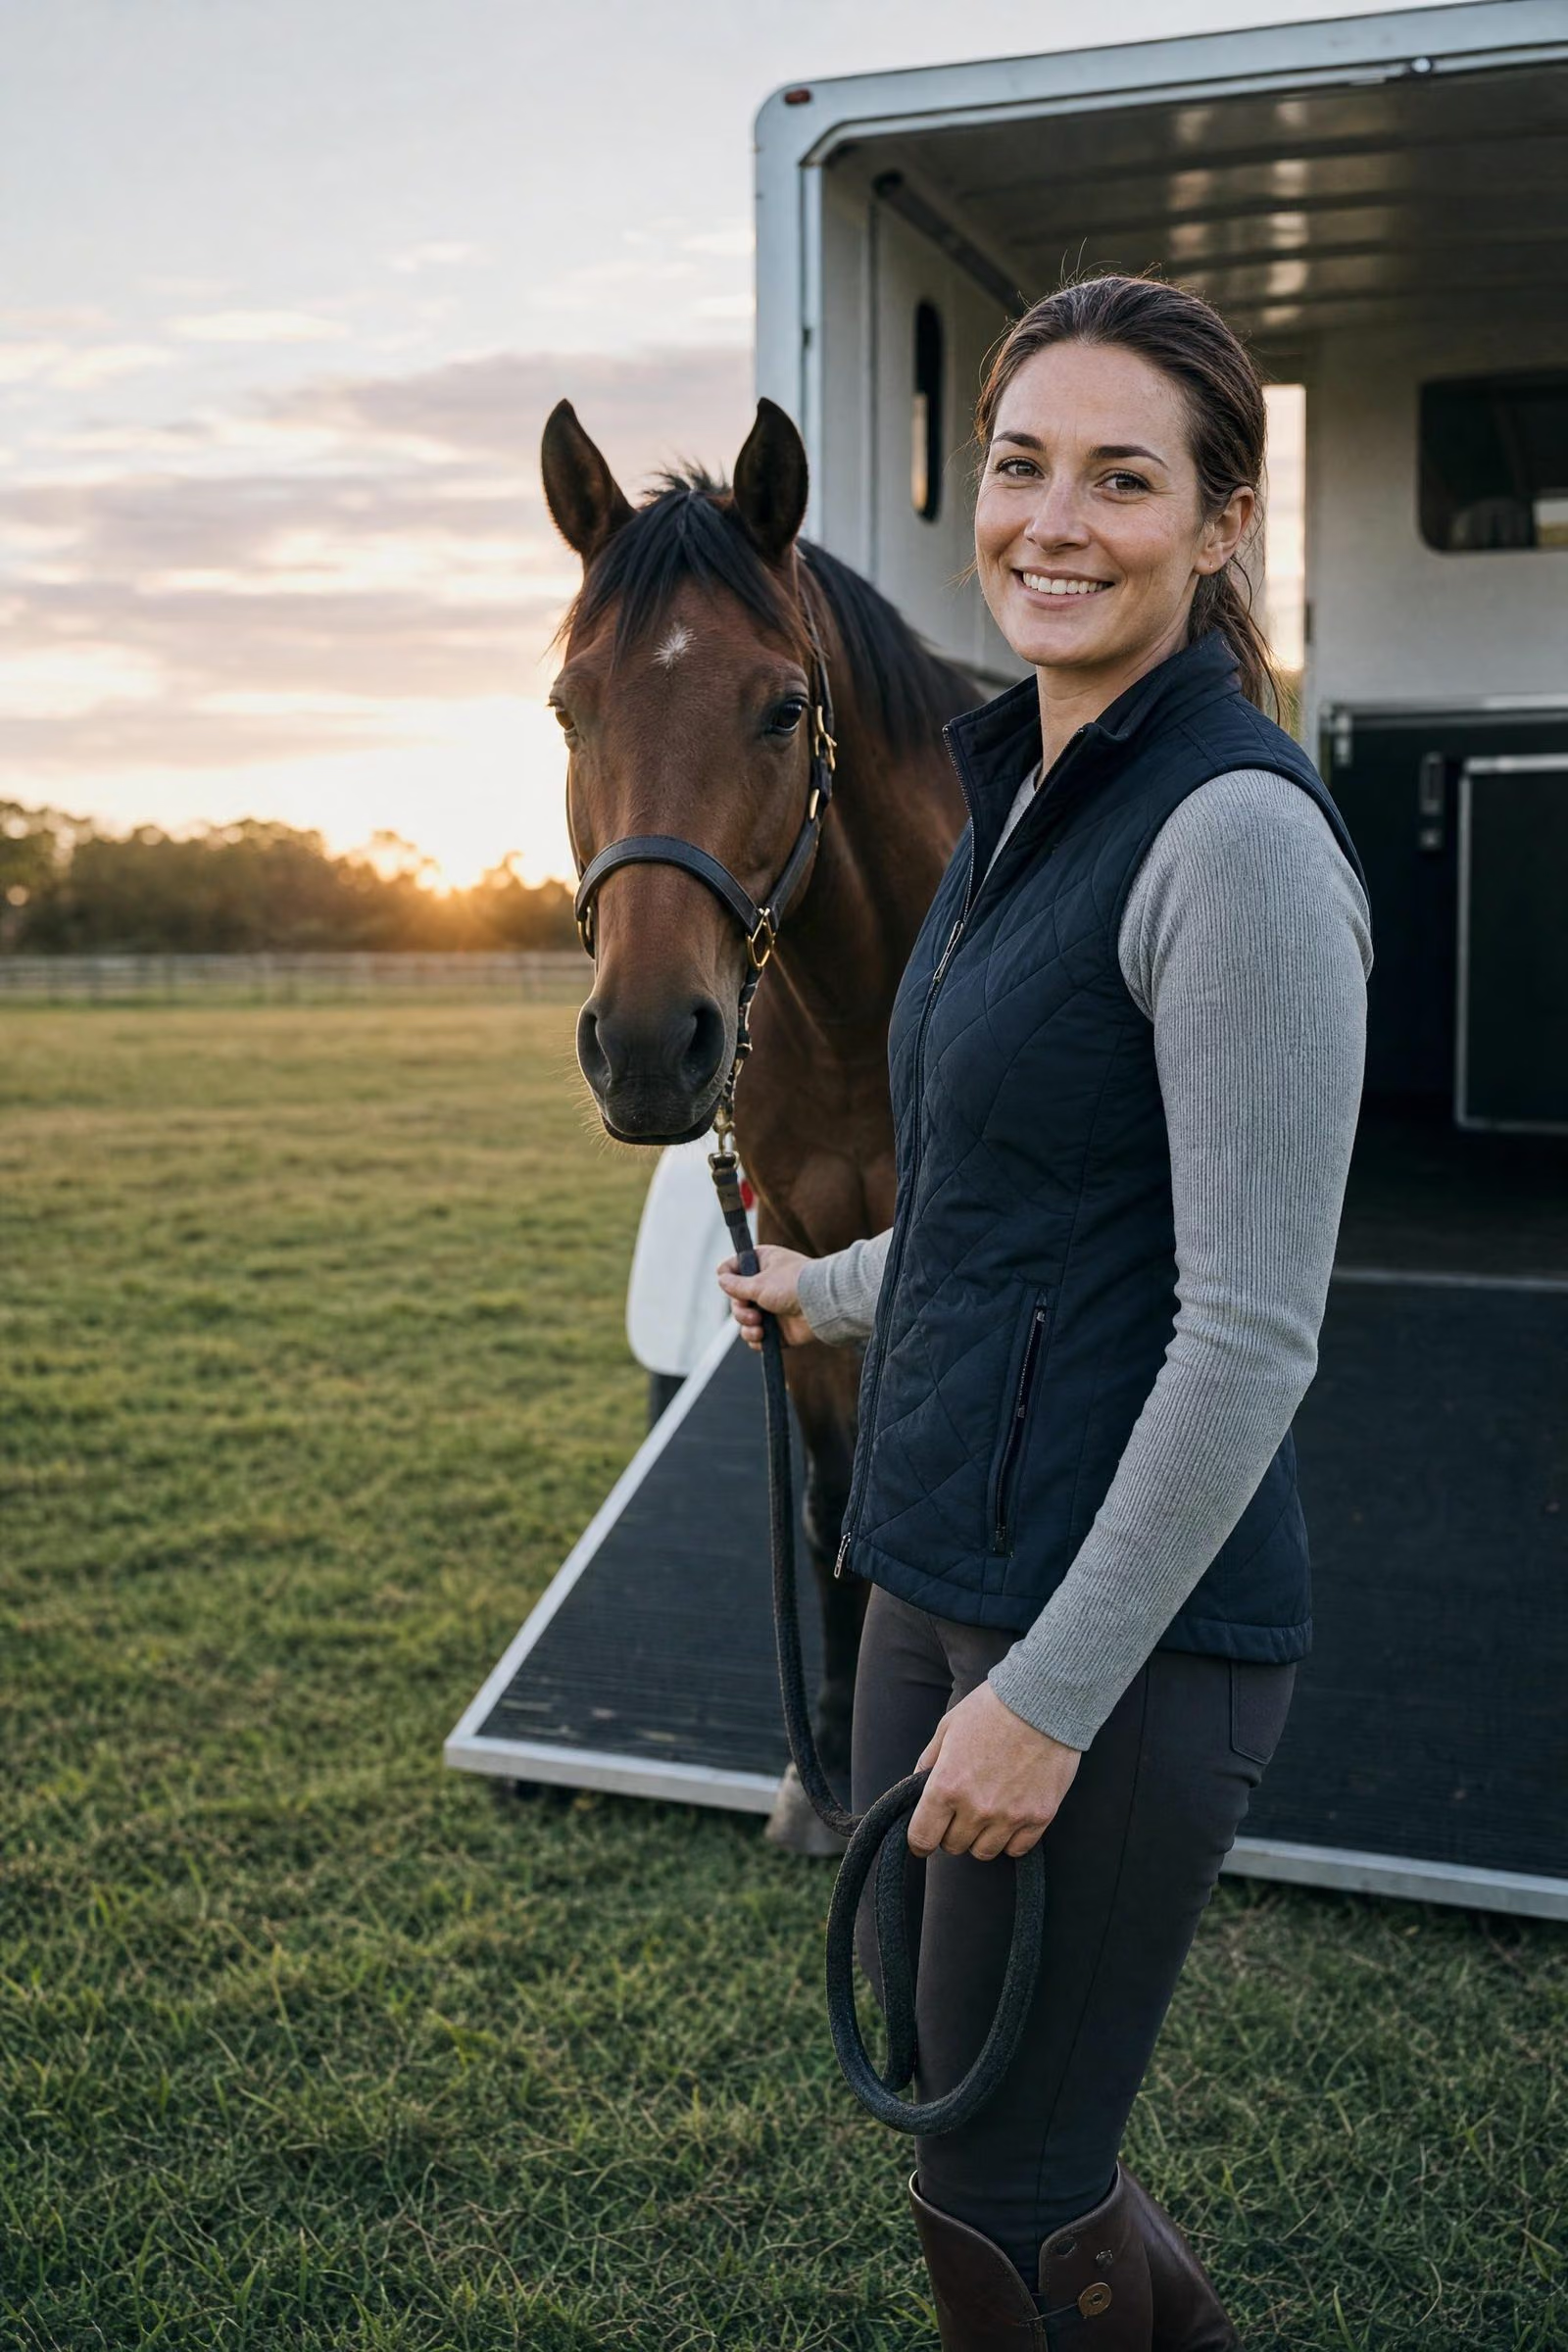
Horse float finance from 48+ Australian lenders.
Whether a float is consumer or commercial finance depends on how it is used. We ask that question first, because it changes the structure and the protections.
 340 client reviews



One broker from your first call through to settlement.
See which horse float finance options fit you.
Tell us what you need. A Lyft Money broker compares options across our lender panel and explains the comparison rate, fees and repayments before you apply. We are a credit assistance provider, not a lender.
Access to 37+ horse float finance lenders
Lenders on our panel that fund horse float finance.
























At a glance
Horse float finance: the numbers that matter.
- Typical price
- $8,000 – $90,000
- Terms
- Up to 72 months
- Indicative rates
- 8% – 22% p.a.
- Typical speed
- 2–5 business days
- Usual structure
- Leisure asset loan
- Useful life
- About 20 years
In plain English
What is horse float finance?
Horse float finance is a consumer loan used to buy a horse float or angle-load trailer, secured against the float. Where the float is used in a horse business it may instead be funded as commercial equipment, so the right structure depends on whether the use is recreational or income-producing.
Horse floats are a long-life asset that hold value unusually well, especially well-built Australian angle-loads with alloy or galvanised construction. The main sources of value loss are floor rot and chassis rust, both of which come from moisture and are hidden until inspected properly. A twenty-year-old float with a sound floor can be worth more than a ten-year-old one that has been neglected.
The finance question that matters most is use. If the float is for recreation, it is consumer credit and carries the protections that come with that — a suitability assessment, disclosure of the comparison rate and a cooling-off framework. If it is used in a horse business, it can generally be financed as commercial equipment with the tax treatment that follows. Your broker will ask about the intended use before recommending a structure.
How lenders assess horse float finance
A float bought for personal or recreational use is regulated consumer credit, with income and expense verification and full disclosure. A float used predominantly in a business — agistment, breeding, coaching, transport — is generally funded as commercial equipment, which can allow GST and depreciation claims. Floats hold value well and are straightforward security. Angle-load and larger multi-horse floats value better than small straight-loads. Private sales require a PPSR check and payment to the registered owner.
New or used
Used floats hold value well and are widely traded; new floats from established Australian builders suit buyers wanting a specific configuration and warranty.
Before you buy
- Check your tow vehicle capacity against the loaded float weight including horses, feed and water — floats are heavier loaded than buyers expect.
- Inspect the floor, chassis and suspension carefully; urine and moisture destroy timber floors and rust steel from the inside.
- Consider angle-load over straight-load for comfort and balance if you travel long distances regularly.
Commonly financed
- Olympic Horse Floats angle-load
- Bostock Horse Floats
- Frontier Horse Floats
- Extreme Trailers gooseneck floats
- Jayco and Sundowner horse transporters



A clear next step
How to finance a horse float.
Your broker checks lender fit across our panel, explains the comparison rate and total cost, and completes a responsible lending assessment before anything is submitted.
- 01
Identify the asset
Type, make, model, year and condition, and whether the purchase is from a dealer or a private seller.
- 02
Set deposit and term honestly
Your broker models negative equity across the term so the deposit and length reflect how long you will keep it.
- 03
Verify and settle
Income and expenses are verified under responsible lending rules, the PPSR is cleared, and the seller is paid directly.
- Photo ID and proof of address
- Payslips and 3 months of bank statements
- Sale contract or dealer invoice with HIN or VIN
The lender makes the final credit decision. Available options depend on your circumstances and the lender’s assessment.
Before you make a decision
Estimate your horse float repayments.
Adjust the price, rate and term to see the repayment and total cost. Consumer loans are quoted with a comparison rate that includes most fees; your broker provides it before you apply.
- Number of repayments
- 60
- Total interest (est.)
- $17,144
- Total repaid (est.)
- $66,144
This calculator is a guide only. It uses simplified assumptions, excludes fees and charges unless stated, and is not an offer or quote. Actual repayments are confirmed by the lender in its loan contract.
From Lyft Money clients
Clear advice.
People who stay in touch.
Rated 5.0 from 340 Google reviews across the types of finance we arrange. Read them on Google.
“keeping us informed every step of the way”
“He explained all the financing options clearly”
“helped out my business”
Ways to finance a horse float
Key terms
What is horse float finance?
Horse float finance is a loan secured against a horse float. Where the float is for personal use it is regulated consumer credit; where it is used predominantly in a business it is generally funded as commercial equipment finance instead.
Straight-load or angle-load float?
A straight-load float carries horses facing forward in individual bays and is usually lighter and cheaper. An angle-load positions horses diagonally, which many horses travel more comfortably in and which allows more horses in a similar length, but adds weight and cost.
Can I finance a horse float personally or through a business?
Both. Private buyers finance floats through a secured leisure or personal loan, while equine businesses such as trainers, agistment operators and riding schools can finance them as business equipment on a chattel mortgage with GST and depreciation benefits. Your broker chooses the structure that fits how the float is used.
Can I finance a used or imported horse float?
Yes. Used floats need a PPSR check, registration and often an inspection, and lenders look at the builder, age and condition of the floor and suspension. Imported floats are financed once complied and registered in Australia. Floats from recognised Australian builders hold value and are easiest to finance.
What does horse float finance cost per month?
As a guide, a $35,000 two-horse float over five years costs roughly $700 to $780 a month depending on the rate and your credit profile, and a seven-year term brings that down further. Use the calculator on this page and your broker firms up the number with a real quote.
Can a gooseneck or horse truck be financed the same way?
Yes. Goosenecks and horse trucks with living quarters are financed as leisure assets or, for businesses, as vehicles or equipment, with terms up to seven years given their long lives. Fit-out such as living areas and tack rooms can be included when quoted with the float or truck.
Can I finance a caravan, boat or motorbike for private use?
Yes. Leisure asset lending is available for caravans, camper trailers, boats, jet skis, motorbikes and horse floats, secured against the asset itself. Because these are bought for private use, the loan is regulated consumer credit with responsible lending obligations and a comparison rate. Terms are commonly up to seven years, sometimes longer for larger caravans and boats. Lenders consider the asset's age and type as well as your income and existing commitments.
How does boat or caravan finance work?
A leisure asset loan is a secured consumer loan where the boat, caravan, motorbike, jet ski or camper trailer is the security, which keeps the rate lower than an unsecured personal loan. Terms run from one to seven years, repayments are fixed, and a balloon can be set to lower the monthly cost. Lenders quote a comparison rate and assess affordability under responsible lending rules, and the asset must be insured for the term.
What leisure assets can be financed?
Boats and outboard engines, caravans, camper trailers and motorhomes, jet skis, motorbikes and scooters, off-road buggies and quad bikes, and trailers. New assets from dealers are the simplest; used assets from dealers and private sellers are financed with a PPSR check and usually an inspection or valuation. Boat packages with the trailer and motor can be financed together.
How much can I borrow for a boat, caravan or motorbike?
Leisure asset loans commonly range from $5,000 to $150,000 or more for large caravans and boats, with lenders financing up to the full purchase price for well-qualified borrowers and often including registration, insurance and accessories. The amount depends on your income and commitments under responsible lending rules and on the asset’s value. A deposit lowers the repayment and can improve the rate.
Why does depreciation matter for leisure asset finance?
Boats, caravans and jet skis can lose value faster than cars, particularly in the first few years, so lenders are careful that the loan balance does not sit above the asset’s value for too long. That influences the maximum term, whether a deposit is asked for and how large a balloon they will allow. A modest deposit and a term that matches how long you will keep the asset keeps you ahead of the depreciation curve, which your broker explains for the specific asset.
Can I finance a used boat or caravan from a private seller?
Yes. Private-sale boats, caravans and bikes are financed with a PPSR check to confirm no finance is owing, verification of the seller, and usually an inspection or valuation. Most lenders set an age limit at the end of the loan, which varies by asset type and is often longer for caravans than for jet skis. Allow a few extra days compared with a dealer purchase for the checks.
Your money. Your decision.
See your options.
Know the costs.
Decide with confidence.
One broker to explain it. Clear numbers before you proceed.
No obligation to proceed.